Upbeat performance, strong growth guidance …
About the stock: Gland Pharma is one of the largest generic injectable-focused B2B / CDMO company, with a global footprint including the US, Europe, Canada, Australia, India and RoW markets.
• Along with its partners, (As of 31st March 2026) Gland owns 1,828 products registrations globally of which ~527 in US, Europe, Canada, Australia, and New Zealand, ~77 in India, and ~1,224 in the rest of the world.
• Q1FY27 revenues breakup- B2B: CDMO- 50: 50. Geography wise – US- 54%, Europe- 22%, RoW- 17%, India- 4%, Other core markets – 3%.
Investment Rationale:
• Strong growth in US and Europe driven by new launches : Consolidated Revenues grew ~19% YoY to ₹ 1800 crore, as mainly driven by 32% growth in the US and 20% growth in Europe (together accounts for ~76% of the revenues). India Domestic grew 12% YoY and RoW grew 2% YoY while. Business wise CDMO pie grew 20% YoY to ₹891.5 crore and B2B business grew 19% YoY to ₹908.8 crore. Consol. EBITDA grew ~33% YoY to ~₹ 489 crore and margins stood at 27.2% (276 bps growth). PAT -grew ~47% to ~₹ 317 crore. Cenexi delivered a revenue of € 48 million tracking flat YoY with € 2 million EBITDA (~4% EBITDA margins).
• Healthy pipeline, long term agreements to steer growth – Q1 numbers were a significant beat across the parameters owing to higher volume despite pricing pressure in the base business. The management has also announced a capex of ₹2000+ crore to be spent over the next 5 years for capacity addition as the existing facilities are at 80-90% utilisation. Overall, the management is looking to deliver a revenues CAGR of 18-20% (earlier guidance- 15%) over the next 3-4 years. Focus on complex products will be the main lever for growth for the base business. This includes six already launched products plus three waiting for approvals. Besides these, 15 complex products are under co- development (7-505(b)(2) products and 8 ANDAs). Additionally, the company has filed 21 Ready-to-Use infusion bag products and received approval for 18 so far. An additional 11 are currently under development. The total RTU bag portfolio has the addressable market of ~ US$ 644 million in the US.
• The new CDMO agreement with a global Pharma is for both oncology and non-oncology products and hence could be a good margin generator. The deal is expected to fructify from FY30 onwards with an annual revenue potential of US$ 90-100 million. Similarly, the deal with Neuland Laboratories is for long-term strategic collaboration for the manufacturing of sterile APIs for microparticle depot products. The company has also struck an in-licensing deal with a Chinese company to develop, manufacture and commercialise an innovative liposomal product for the US and European markets. Gland continues to grow in stature with its 100% injectables offerings across the globe and with different clients.
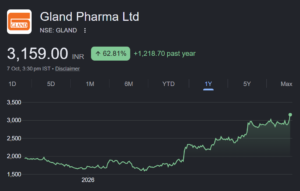
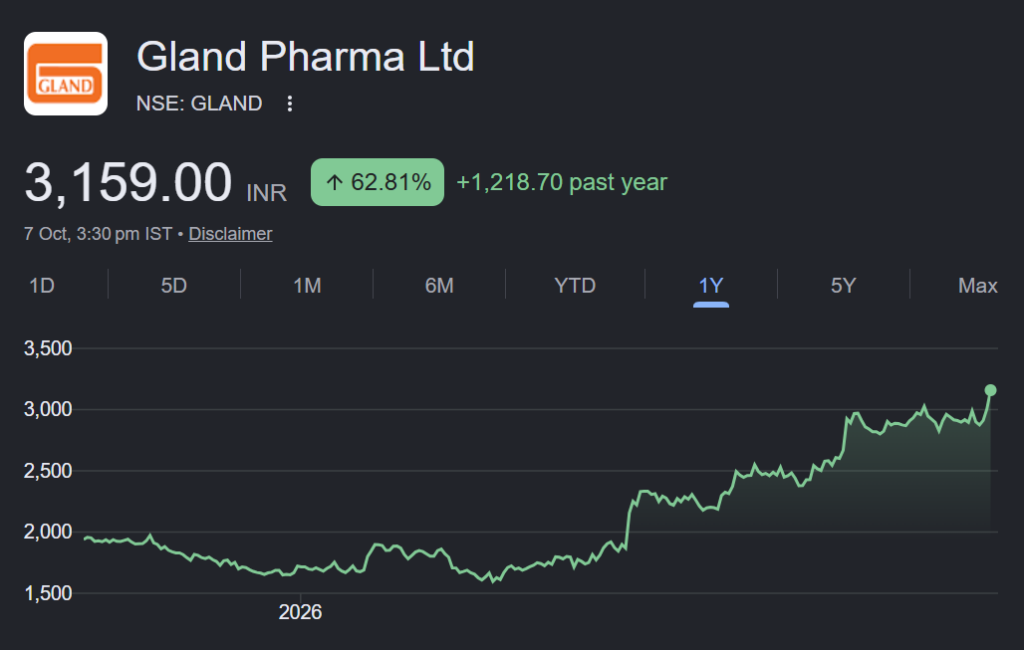
Rating and Target Price: We value Gland at ₹3430 per share based on 22x FY28E EBITDA of ₹2367 crore.