Moving beyond recycling to unlock higher growth…
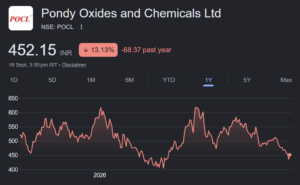
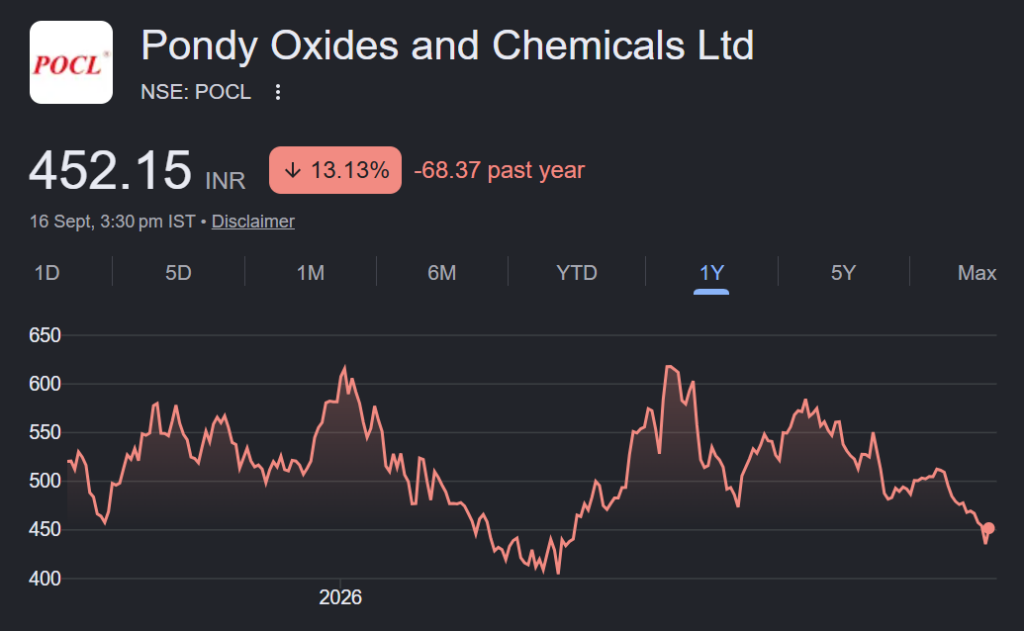
About the stock: Pondy Oxide and Chemicals (POCL), est. in 1995, is engaged in recycling & production of non-ferrous metals (Copper, Lead, Aluminium, and others). It is one of the largest recyclers operating in non-ferrous space in India.
• Operates 2 manufacturing complexes located in Tamil Nadu and Andhra Pradesh with combined annual production capacity of ~2.4 lakh tons. • Consol. FY26 Sales: Lead and lead alloy ingots (~76%), Copper and copper ingots (~23%), Aluminium alloys and engineering plastic granules (~1%)
Investment Rationale:
• Industry tailwinds enabling long term growth opportunities for POCL: India’s recycled metal demand has witnessed healthy growth prospects, supported by rising demand for sustainable raw materials, and stringent environmental regulations. As per industry sources, secondary/recycled Aluminium volumes have increased from ~1.3 MTPA in 2020 to ~1.9 MTPA in 2024 and is projected to reach ~3.4 MTPA by 2029. Secondary lead volumes have increased from ~1 MT in 2020 to ~1.2 MT in 2024 and is projected to grow to ~1.7 MT by 2030. Recycled copper volumes on the other hand have increased from ~300 KT in 2020 to ~650 KT in 2024 and is projected to reach ~1.2 MTPA by 2029. It is also aided by Government initiatives, including the Non-Ferrous Metal Scrap Recycling Framework, EPR and Battery Waste Management Rules. The government’s target of achieving at least 10% recycled content in aluminium, 20% in copper and 25% in zinc by FY31 is expected to further strengthen the organised recycling ecosystem and create long-term growth opportunities for POCL.
• Aggressive expansion towards higher value-added product to enhance growth: POCL has aggressively expanded its capacity with recently commissioning of 72 KTPA facility, thereby increasing total installed lead capacity by 55% to 204 KTPA. Further, its higher focus on value-added product, accounted for ~70% of lead revenue, supports superior conversion margins. Meanwhile, copper is emerging as next structural growth driver, with transitioning from a small recycling operation (12 KTPA capacity) towards higher-value-added products by setting up 36 KTPA of copper cathode capacity in two phases with capex of ₹200 crore. This will move further up the value chain, enabling it to capture higher value from recycled copper, thereby generating EBITDA/tonne of ~₹60,000-65,000 vs current~₹40,000 levels. We expect POCL to deliver revenue and EBITDA CAGR of ~31%/26% over FY26-29E. Notably, POCL’s long-term growth strategy remains encouraging, by diversifying into lithium-ion recycling and other recycling facilities, supported by its 123-acre Mundra land bank and targeting 15%+ volume and 20%+ revenue/profitability growth by 2030. Moreover, the target of increasing share of value- added products (>60%), improving EBITDA margins (>8%) and +20% RoCE, thereby makes a compelling case of re-rating for POCL.
Rating and Target Price: We have a positive view on Pondy Oxide, supported by strong industry tailwinds, favourable government regulations, capacity expansion across lead and copper segments, increasing value-added products, controlled B/S (0.2x D:E) and healthy return ratios profile of >20%. On that note, we assign a BUY rating on stock with a target price of ₹625, i.e. 20x PE on FY28E.