Imperial Blue getting apt support
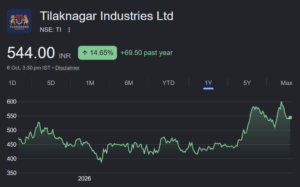
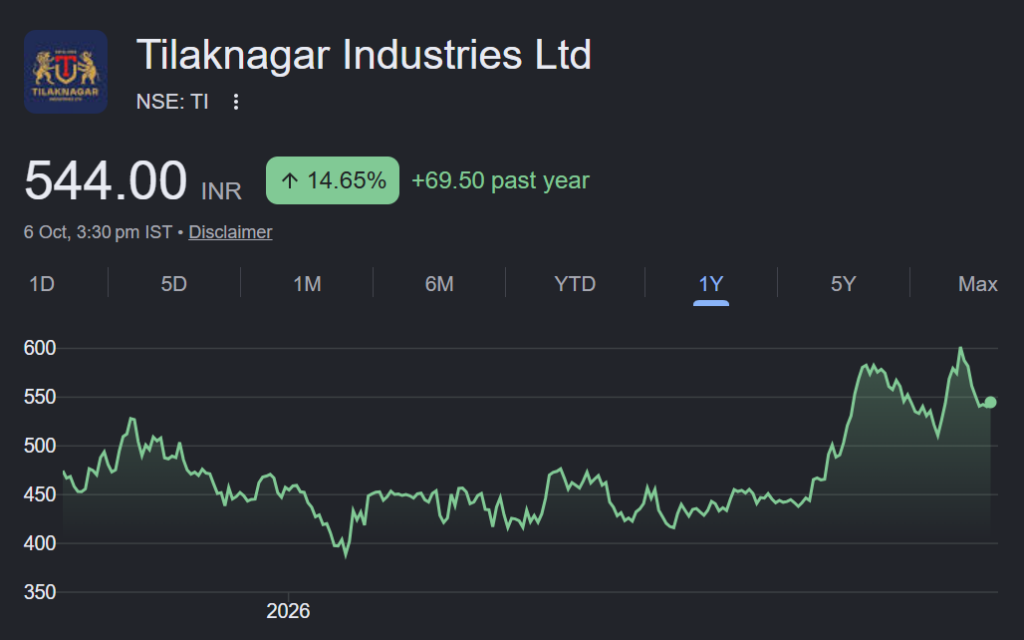
We maintain BUY, with a Sep‑27 TP of INR700, on 35x P/E. In our meeting, management reiterated its focus on strengthening the Imperial Blue franchise in FY27E, which will bolster pan‑India presence — a critical enabler for upcoming launches and for achieving mid‑teen volume growth over FY28‑30E (we estimate low-teen growth, in the absence of visibility on new launches). On margins, while the acquisition is initially dilutive, several initiatives are underway to drive improvement. Management’s 16-18% margin guidance for FY29E factors in synergies, productivity gains, new launches, and scale benefits. With a ballooned payout structure on borrowings, management may explore creeping acquisitions in disruptive craft businesses to balance bandwidth and funding needs, further reinforcing its positioning in the luxury segment. Near‑term catalysts include potential price hikes in Telangana and relaxed rules for national brands in Tamil Nadu — neither of which is factored into our estimate or management guidance.
▪ Ground checks indicate improving growth for Imperial Blue: Our ground checks indicate that Tilaknagar is addressing state-specific requirements effectively to strengthen the Imperial Blue franchise. Karnataka remains a key growth market, where the brand has seen its strongest traction, supported by agile price cuts implemented immediately after-tax changes. This has been followed by share gains in Andhra Pradesh, Uttarakhand, and Rajasthan. Tilaknagar has also improved SKU availability and broadened market supplies. These progressive actions should help absorb pressure in Maharashtra and West Bengal (following the discontinuation of the low-priced SKU). On the supply side, the company is engaging with local bottlers to enhance market availability, while Scotch requirements are secured through a long-term renewable contract with Chivas. It has launched Imperial Black, positioned between the low and mid-prestige price segments.
▪ Premiumization efforts with new actions: To tap the opportunity in luxury segments, the company has expanded its organic portfolio with Monarch Legacy Brandy and Seven Island. Through strategic investments, it is steadily widening its luxury and super-premium presence — supported by the Spaceman portfolio (current stake 21.36%, expected to rise to ~51% over the next 2–3 years, offering premium play across gin, vodka and rum) and Black Tiger Distilleries (where it has taken a 30% strategic stake, providing a foothold in tequila). Management remains open to additional partnerships. As Imperial Blue progresses on its market-share rebuild, we expect it to broaden its category and portfolio participation. Given the rapid growth in the vodka segment, we also see scope for incubating an organic vodka brand.
▪ Improving leverage position to aid rerating; Tamil Nadu opening can boost prospects: Tilaknagar’s net debt stood at INR21bn as of Jun‑26, largely due to the Imperial Blue acquisition. We expect net debt to moderate to INR17bn by Mar‑27, supported by internal cash generation and promoter conversion of warrants. Management aims to bring net‑debt‑to‑EBITDA below 1x, which we believe is achievable by FY29E. Any opening up of Tamil Nadu to national brands could materially enhance its prospects and strengthen its financial position. Key risks include adverse regulatory actions in core states that could affect its already- leveraged profile.