GPHG Exhibition Reinforces India’s Luxury Watch Opportunity
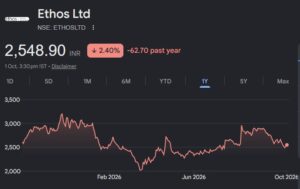
Ethos Ltd hosted an exhibition showcasing some of the world’s finest timepieces nominated by the Grand Prix d’Horlogerie de Genève (GPHG) Academy, in the presence of Mr. Raymond Loretan, President, GPHG Foundation. The event was followed by an interaction with the management, which outlined its long-term growth strategy and expansion plans. The discussions reinforced Ethos’ confidence in the structural growth opportunity for luxury watches and accessories in India.
India is gaining increasing relevance on the global luxury map, with international watch brands stepping up their focus on the country. This is reflected in India’s improving position in global Swiss watch exports, moving to 14th in CY26TD from 20th in CY25. Against this backdrop, Ethos remains focused on expanding its retail footprint, widening its addressable market and scaling its lifestyle and manufacturing businesses.
Key Takeaways
• Management Remains Confident of a 10x Growth Opportunity: Ethos remains committed to 10x revenue growth over the next 10 years and expects to potentially achieve the target 1–2 years ahead of schedule. Management expects FY27 to be its fastest-growing year, supported by a growing luxury market and improving retail infrastructure.
• Boutique Expansion Provides Significant Headroom for Growth: Ethos plans to expand its boutique network from ~100 stores currently to ~300 stores over the next 5– 6 years. With key constraints around talent, training and premium retail locations largely addressed, the company is well placed to accelerate expansion and improve store productivity.
• New Formats to Broaden the Addressable Market: Ethos is expanding beyond its traditional luxury watch positioning through differentiated retail formats. The upcoming Hour Studio format will target the relatively larger Rs 25,000–200,000 price segment, thereby opening access to a broader customer base. At the other end of the spectrum, Ethos Haute Horology will focus on watches priced above Rs 5 Mn, strengthening its presence in the ultra-luxury segment. Ethos is also strengthening its after-sales network to support the expanding luxury watch base.
• Favre Leuba Gaining Traction; Manufacturing Capacity to Scale Up: Favre Leuba has seen encouraging initial traction, with production reaching ~3,000 watches vs. the initial plan of ~1,800 units. Production is targeted at ~8,000 units this year, with capacity expected to double over the next two years, supported by a healthy product pipeline.
• Lifestyle Portfolio Gaining Momentum: Rimowa and Messika have delivered better than-expected traction. Ethos plans to open its third Rimowa boutique in October and launch its e-commerce channel, while evaluating additional global lifestyle brands.
• Valuation and Recommendation:
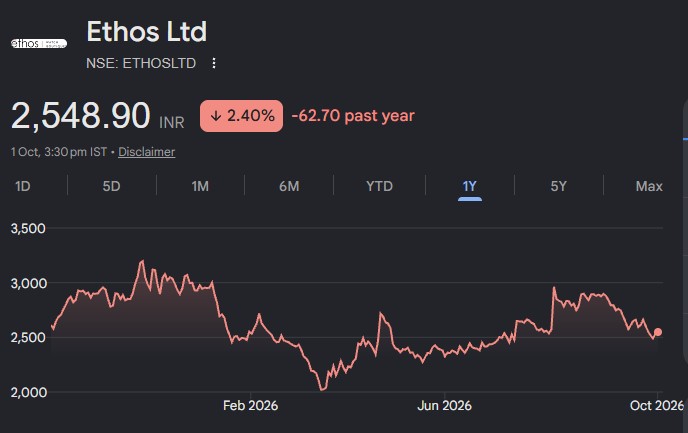
• Ethos has largely addressed the key operational bottlenecks that had constrained its pace of expansion, particularly around talent, frontline training and access to premium retail locations. With these investments now in place, we expect the company to gradually benefit from a larger store network and improving productivity. The combination of rapid boutique expansion, a widening product and price portfolio, scaling of Favre Leuba, growth in pre-owned watches and increasing traction in luxury lifestyle provides multiple avenues for sustained growth. The company’s strong cash position further reduces the funding constraints associated with this expansion. Hence, we maintain our BUY rating, valuing the company at 38x Jun’28E EPS, to arrive at a TP of Rs 3,360/share, implying an upside of 33% from the CMP.