Driving growth through regulation and premiumisation …
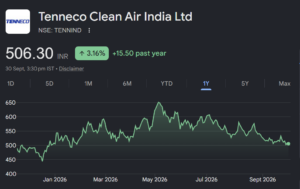
About the stock : Tenneco Clean Air India (Tenneco) is an automotive component supplier, manufacturing critical, highly engineered & technology intensive clean air, powertrain & suspension solutions for Indian OEMs & export markets.
• FY26 Sales Mix: PV: 65%, CV: 21%, Industrial: 7% & Aftermarket: 4%
• FY26 Product Mix: Clean Air: 49% & Advanced ride technologies: 51%.
Investment Rationale:
• Clean Air business segment: tightening emission norms should drive content per vehicle : In clean air space, Tenneco provides fully integrated exhaust & aftertreatment systems, which are designed to reduce pollution & optimize engine performance and acoustic tuning. It holds leading position in this domain, with ~58% market share in CV space, ~68% in off- highway (ex-tractors) space & ~20% in PVs. The biggest structural opportunity for Tenneco in this domain comes from increasing technological content required in vehicles as emission and fuel-efficiency regulations become more stringent. The transition from BS-VI to the next generation of emission regulations is expected to increase the complexity of exhaust after-treatment systems, particularly for CV’s and off-highway applications. Content per vehicle (CPV) is expected to increase by ~30- 50% as OEMs adopt more stringent emission-control systems. This allows Tenneco to potentially grow faster than underlying OEM volume growth. This segment however is susceptible to EV risk as EV’s don’t require clean air solutions. We bake in 12% sales CAGR in this domain over FY26-29E, supported by CPV improvement, new program wins & market-share gains.
• Advance Ride Technologies (ART): most exciting proposition, premiumisation to the core : Tenneco’s ART/Suspension business provides an important counterbalance to Clean Air business and gives the company exposure to the structural premiumisation of Indian PV space. Indian PV vehicle market has undergone a significant shift toward SUVs, larger vehicles and higher-value variants. Premium vehicles require more sophisticated ride handling technologies, including advanced shock absorber, electronically controlled suspension & higher-performance damping systems. Tenneco is already a major supplier of shock absorbers and struts to Indian PV OEMs with a leading ~55% market share. A key recent innovation led development was the selection of Tenneco’s DaVinci DCx technology by M&M for XUV 7XO. The solution is mechanical in nature and does not depend on software, electronics, sensors, etc., thereby broadening its applicability while increasing value of suspension content. Premiumisation therefore creates an opportunity for Tenneco to grow not only through increasing vehicle volumes but also through higher content per vehicle. We bake in 20% sales CAGR in this domain over FY26-29E.
Rating and Target Price
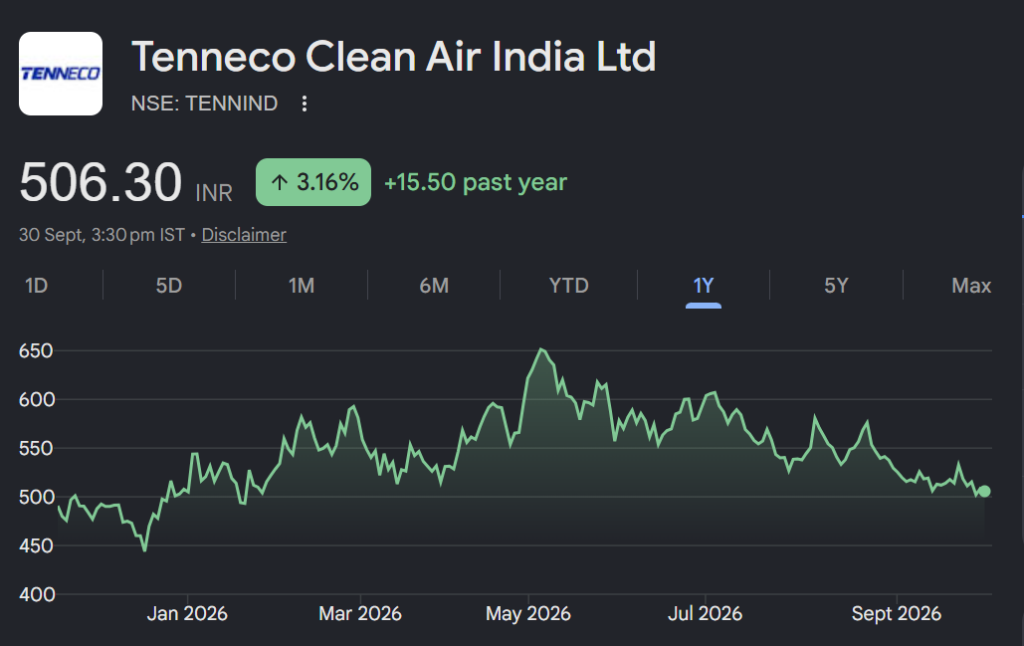
• We have a positive view on Tenneco supported by strong growth visibility amid premiumization & regulation led content expansion, a healthy order book, and robust financials (healthy 50%+ return ratios & debt free b/s). We assign BUY Rating & value it at ₹650 i.e. 30x P/E on FY28 – 29E avg. EPS