Motilal Oswal initiates coverage with BUY rating and ₹6,150 target price, implying 37% upside
SPR Auto Technologies (SPR) is undergoing a significant transformation—from being primarily known as a leading piston manufacturer to becoming a diversified, technology-driven and powertrain-agnostic auto component platform.
According to a Motilal Oswal research report, SPR combines a highly profitable and cash-generative piston business with a growing portfolio of precision-engineered businesses acquired through strategic inorganic expansion. The brokerage has initiated coverage with a BUY rating and a target price of ₹6,150, based on 30x September 2028E earnings. At the cited CMP of ₹4,494, this represents an upside of about 37%.
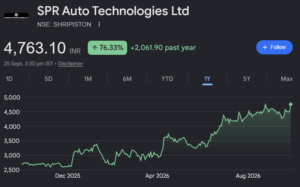
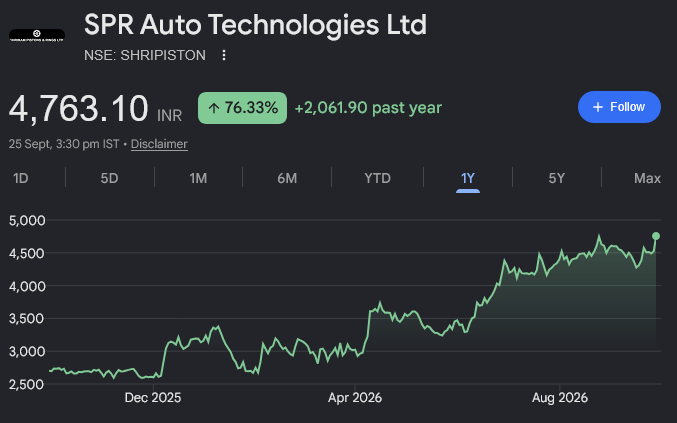
With a market capitalisation of approximately ₹22,000 crore, the stock has already delivered a strong 76% return over the past year, reflecting increasing investor interest in its transformation and growth prospects.
From piston manufacturer to diversified mobility platform
SPR’s core piston business remains the foundation of the company.
The company operates in a high-entry-barrier precision-engineering segment and has an estimated market share of more than 45%. Its technological capabilities, long-standing relationships with major OEMs and manufacturing scale have helped it establish a strong position in the market.
Importantly, Motilal Oswal highlights that the piston business generates margins around 500 basis points higher than the next peer, while core RoCE is above 50%. This makes the business a significant cash generator for SPR.
Rather than treating the piston business as an ageing internal-combustion-engine (ICE) franchise, SPR is leveraging its cash generation and balance sheet to build businesses that can participate across different vehicle technologies.
Pistons could remain relevant for longer
The transition towards electric vehicles has raised concerns about the long-term prospects of traditional engine components. However, SPR’s opportunity extends beyond conventional petrol and diesel engines.
The company is positioned to benefit from increasing adoption of CNG, ethanol, hydrogen and hybrid powertrains, all of which continue to require internal-combustion or hybrid engine technologies.
The aftermarket provides another avenue for growth, while opportunities in non-auto applications could further expand the addressable market.
SPR could also benefit from the gradual exit of some global competitors from the ICE component ecosystem. This creates the possibility of market-share gains for established suppliers with strong technology, manufacturing capabilities and OEM relationships.
As a result, the piston franchise could continue generating substantial cash even as the automotive industry gradually diversifies its powertrain mix.
Acquisitions are changing SPR’s growth profile
The more important part of the investment story is SPR’s aggressive diversification through acquisitions.
The company has acquired businesses including Antolin, Takahata, TGPEL and EMFi. According to Motilal Oswal, these businesses together contribute approximately 35% of consolidated revenue.
These acquisitions take SPR beyond its traditional powertrain-focused portfolio and into areas such as precision plastic moulding and other high-value automotive components.
The strategic objective is not simply to add revenue. SPR is attempting to increase its content per vehicle substantially—from its earlier levels to more than ₹30,000, representing an estimated 6x expansion.
This could materially increase the value captured by SPR from each vehicle while simultaneously reducing its dependence on any single component or powertrain.
Building a powertrain-agnostic business
One of the key attractions of the strategy is that several of the acquired products are relevant across both ICE and EV platforms.
This gives SPR exposure to multiple technological pathways rather than requiring the company to correctly predict which powertrain technology will dominate in the future.
The company is becoming diversified across:
- Products
- Powertrains
- Customers
- Vehicle segments
- Distribution channels
- Geographies
No single customer or vehicle segment contributes materially to overall revenue, according to the research report.
This diversification can potentially reduce customer concentration and cyclicality while creating multiple avenues for growth.
Strong balance sheet supports the transformation
SPR’s ability to pursue this strategy is supported by its strong cash generation and relatively efficient working-capital management.
The company has a working-capital cycle of approximately 63 days, while consolidated core RoCE stands at around 20%.
Its long-term cash-flow record is also noteworthy. Motilal Oswal estimates that the company’s 10-year net CFO-to-EBITDA conversion is approximately 80%, while FCF-to-PAT conversion is around 57%.
Consistent dividend payouts further demonstrate the company’s ability to generate and distribute cash while simultaneously investing in growth.
The company has also recently completed a ₹1,000 crore QIP, providing additional financial resources for future organic and inorganic opportunities.
Subsidiaries could become the next growth engine
While the piston business continues to provide stability and cash flow, the acquired businesses could increasingly become the growth engine.
Motilal Oswal estimates a 21% PAT CAGR, supported by the combination of a stable standalone business and rapid scaling of subsidiaries.
The brokerage expects consolidated core RoCE to improve from approximately 20% in FY26 to 28% in FY29, driven by better margins and improving scale within the subsidiaries.
Importantly, the growth is not expected to require excessive capital expenditure. The brokerage expects limited growth capex requirements and gradual balance-sheet improvement from the FY26 base.
This creates the possibility of earnings growth being accompanied by improving capital efficiency.
Valuation could reflect the transformation
At the cited CMP of ₹4,494, SPR trades at approximately 23.7x FY28E earnings and 20.4x FY29E earnings, according to Motilal Oswal.
The brokerage values the company at 30x September 2028E EPS and arrives at a target price of ₹6,150.
The valuation argument rests on the expectation that SPR will increasingly be valued not merely as a traditional piston manufacturer, but as a diversified auto-component company with exposure to multiple products and powertrain technologies.
The successful integration and scaling of acquisitions, therefore, becomes critical to the investment thesis.
What could drive the next phase of growth?
Several factors could potentially act as catalysts:
1. Scaling of acquired businesses: Antolin, Takahata, TGPEL and EMFi could contribute increasingly to consolidated earnings as their operations scale.
2. Margin expansion: Improvement in subsidiary margins could lift consolidated profitability.
3. Powertrain diversification: Increasing demand for CNG, ethanol, hydrogen and hybrid vehicles could extend the growth runway for the piston business.
4. Market-share gains: The exit of some global competitors from the ICE ecosystem could create opportunities for SPR.
5. Higher content per vehicle: The move towards ₹30,000+ estimated content per vehicle could significantly expand SPR’s revenue opportunity.
6. Capital deployment: The ₹1,000 crore QIP provides additional capital for future acquisitions and organic expansion.
Risks investors need to monitor
The transformation also brings its own risks.
Competition could intensify in the acquired businesses, while fluctuations in commodity prices could affect margins. Rapid technological changes in the automotive industry remain another risk, particularly if the pace of powertrain transition differs from expectations.
The company also needs to successfully integrate its acquisitions and scale them profitably. Any loss of key customers could affect growth given the importance of OEM relationships.
Conclusion
SPR Auto Technologies is attempting to create a new identity for itself.
Its 45%+ estimated piston market share, superior margins, strong cash generation and 50%+ core RoCE provide a robust foundation. At the same time, acquisitions such as Antolin, Takahata, TGPEL and EMFi are taking the company into precision components that are less dependent on a particular powertrain.
The combination is potentially significant: a cash-generating piston franchise funding the creation of a diversified, powertrain-agnostic auto-component platform.
Motilal Oswal expects this transformation to drive a 21% PAT CAGR and improve consolidated core RoCE from around 20% in FY26 to 28% in FY29. With a ₹6,150 target price versus the cited ₹4,494 CMP, the brokerage’s thesis is that the market could increasingly value SPR on the earnings potential of its broader component platform rather than solely on its traditional piston business.
At a market capitalisation of around ₹22,000 crore and after a 76% YoY rise in the stock, the key question for investors is therefore not merely whether SPR can grow its piston business, but whether it can successfully execute and scale its transformation into a diversified mobility-components company.
Target Price: ₹6,150 | CMP: ₹4,494 | Potential upside: ~37% | Rating: BUY (Motilal Oswal)
The above article is based on the research points provided from the Motilal Oswal report. The target price, estimates and investment view are those of the brokerage and should not be construed as an independent recommendation.