Valuation and view
◼ 2QFY27 marked another quarter of strong operational performance for JFSL, reflecting the compounding momentum across its full-stack financial services ecosystem. Growth remained broad-based, driven by disciplined loan book expansion at Jio Credit, rapid scaling of asset management offerings under the BlackRock JVs, and steady growth in payments.
◼ The company’s strategic playbook is taking shape, with marquee partnerships across lending (Bank of America), investments (BlackRock) and insurance (Allianz Group) bringing global expertise, institutional capabilities and best practices to the platform. Supported by a robust capital base, expanding digital reach and improving customer engagement, JFSL remains well-positioned to scale its businesses and drive long-term sustainable growth.
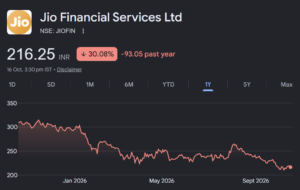
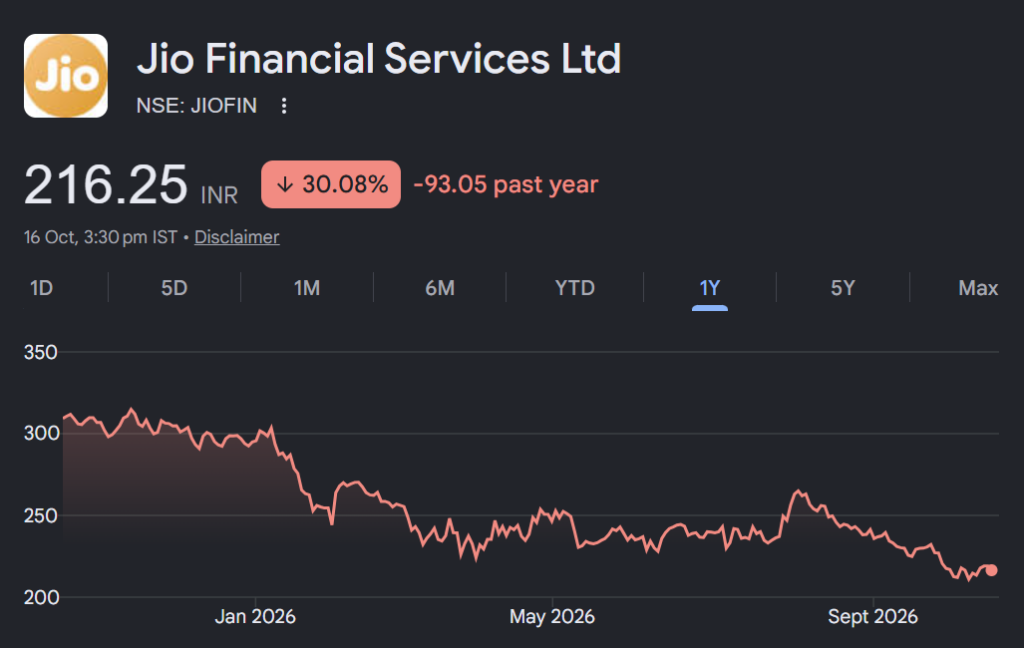
◼ We cut our FY27 EPS estimate by ~6.6% to factor in higher provisions, while we raise our FY28 EPS estimate to reflect the improvement in NII. The stock trades at 0.9x FY27E P/BV. We model a consolidated PAT CAGR of 54% over FY26-FY28 and reiterate our BUY rating on the stock with a TP of INR300 (based on Sep’28E SoTP). Our SoTP does not factor in valuation from businesses like insurance manufacturing, wealth management, broking and marketplace, which are still in their incubation phase.