Ashish Kacholia’s Bet on ARDEE
Ace investor Ashish Kacholia, known for identifying emerging businesses with strong growth potential, holds 2.58% of ARDEE. His investment has brought the company into the spotlight as investors look for lesser-known businesses capable of delivering sustained earnings growth.
ARDEE operates in the lead recycling industry and supplies recycled lead to battery manufacturers, including Amara Raja. Its business is linked to the demand for lead, which is widely used in automotive batteries and industrial applications.
Recycling also plays an important role in resource efficiency by recovering valuable metals from used batteries and other lead-bearing materials. For battery manufacturers, recycled lead can form an important part of the raw-material supply chain.
IPO Journey: From Blockbuster Listing to Post-Listing Correction
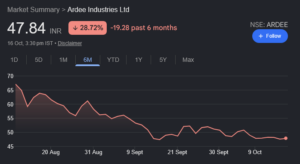
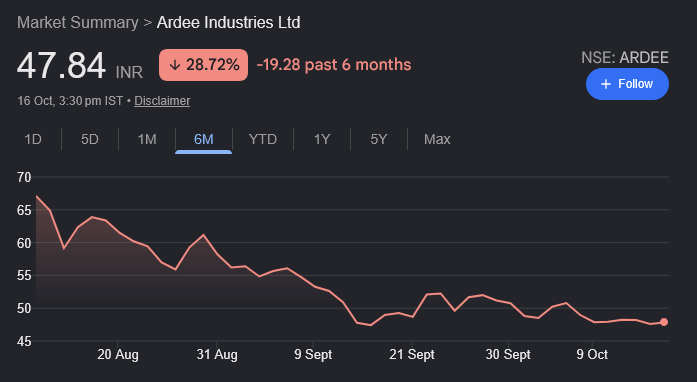
ARDEE’s initial public offering was priced at ₹53 per share, and the stock made a strong debut at ₹74, a listing gain of approximately 39.6% over the issue price.
However, the initial enthusiasm has subsequently cooled. The stock is now trading around 10% below its IPO price, according to the figures provided.
This reversal presents an interesting contrast. While the company’s financial performance has expanded rapidly, the stock market’s initial enthusiasm has not translated into sustained price appreciation.
The correction may prompt investors to examine whether the current valuation adequately reflects the company’s growth prospects, business risks and future earnings potential.
Among India’s Leading Lead Recyclers
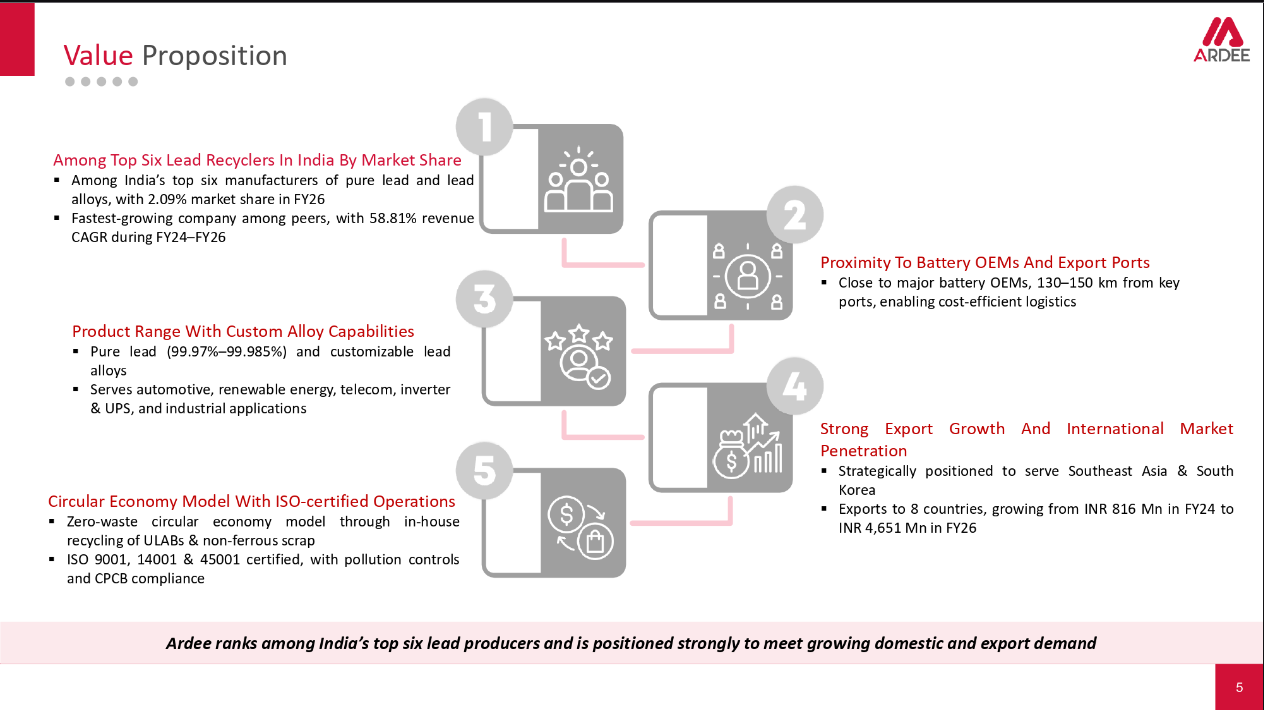
ARDEE is reported to be among the six largest lead recyclers in India by market share. More importantly, it has emerged as one of the fastest-growing companies among its peers.
Its growth over FY24–FY26 has been particularly striking:
| Financial metric | CAGR, FY24–FY26 |
|---|---|
| Revenue | 58.8% |
| EBITDA | 129.0% |
| Profit after tax (PAT) | 207.5% |
The figures suggest that profitability has grown substantially faster than revenue. EBITDA growth of 129% and PAT growth of 207.5% indicate a potentially powerful combination of operating leverage, improving profitability and earnings expansion.
However, these growth rates need to be interpreted carefully. A high CAGR over a two-year period can partly reflect a low starting base. Investors should also examine the absolute revenue and profit figures, margins, cash flows and working-capital requirements to determine whether the growth is sustainable.
Why the Lead Recycling Business Matters
Lead recycling is an established industrial activity supported by demand for batteries across automotive and other applications. Recycled lead can be an important input for battery manufacturers, making the ability to supply consistent-quality material a key part of the value chain.
ARDEE’s reported relationships with battery manufacturers such as Amara Raja provide context for its position in this ecosystem. Its ability to expand capacity, secure raw materials and maintain customer relationships will be important determinants of future growth.
The investment case rests on several factors:
- Industry position: A reported presence among India’s six leading lead recyclers gives ARDEE a meaningful position in its market.
- Rapid growth: Revenue CAGR of 58.8% between FY24 and FY26 points to a significant expansion in business scale.
- Operating leverage: EBITDA has grown faster than revenue, suggesting the potential for improved operating economics.
- Earnings momentum: PAT CAGR of 207.5% indicates substantial profit expansion, although the absolute numbers and sustainability need verification.
- Battery-industry linkages: Supplying recycled lead to battery manufacturers connects the company to an established industrial supply chain.
Valuation: Is the Growth Already Priced In?
At the upper IPO price band of ₹53, ARDEE was valued at approximately 19.7 times earnings, based on the figures provided.
A P/E multiple of 19.7 times can appear reasonable for a business delivering rapid earnings growth. However, the appropriate valuation depends on whether the company can sustain its growth trajectory and convert accounting profits into cash.
Investors should examine the following before drawing conclusions about the stock’s attractiveness:
- Earnings sustainability: Can the company maintain strong profit growth as its business expands?
- Margin trajectory: How much of the historical EBITDA growth came from structural improvements rather than temporary factors?
- Cash-flow generation: Are operating cash flows keeping pace with reported profits?
- Capital requirements: How much investment is required to expand recycling capacity and support working capital?
- Debt and raw-material exposure: How sensitive are earnings to lead prices, procurement costs and financing requirements?
The IPO valuation also needs to be distinguished from the stock’s current valuation. A share price 10% below the issue price does not automatically mean that the company is undervalued; investors must assess the latest earnings and market capitalisation.
What Should Investors Watch?
ARDEE’s next phase will depend on its ability to translate exceptional historical growth into a durable business model. Sustained customer demand, efficient capacity utilisation, disciplined capital allocation and strong cash conversion could support its long-term prospects.
At the same time, lead recycling businesses can face volatility in raw-material prices, inventory valuation, working-capital requirements, environmental compliance and competition. These factors may affect margins and cash flows even when revenue continues to grow.
Ashish Kacholia’s 2.58% holding makes ARDEE a company worth examining, but an investor’s presence should be treated as a starting point for research rather than proof of future returns.
The Bottom Line
ARDEE combines a reported position among India’s leading lead recyclers with exceptional FY24–FY26 growth in revenue, EBITDA and profit. Its supply-chain links with battery manufacturers and the presence of Ashish Kacholia on its shareholder list add to investor interest.
Yet the stock’s fall below its IPO price underlines an important distinction: a fast-growing business is not necessarily an attractive investment at every price.
Investors should assess the latest financial results, cash-flow performance, balance sheet, current valuation and sustainability of earnings growth before making an investment decision. ARDEE’s ability to maintain its growth while generating healthy cash flows will ultimately matter more than its IPO performance or the identity of its shareholders.
Disclaimer: This article is for informational and educational purposes only and is not investment advice. Shareholding, financial growth rates, valuation and price-performance figures are based on the information provided and should be independently verified against company disclosures and exchange filings.