Topline gaining momentum, margin improvement to follow
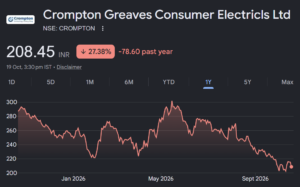
About the stock: Crompton Greaves Consumer Electricals (CGCE) is one of the leading fast moving electrical goods (FMEG) companies with presence in electrical consumer durables (ECD). With a legacy spanning over 85+ years and robust distribution backbone of 2800+ distributors, 2,75,000+ retail touchpoints and over 860 service centres, CGCE is well positioned to capitalize its network for existing segments as well as provide a runway for its newer businesses to scale.
Q2FY27 performance: CGCE reported healthy Q2FY27 with consolidated revenue growth of 18.2% YoY (+1.3% QoQ) to ₹2,263 crore, marking the third consecutive quarter of double-digit revenue growth along with signs of profitability revival. EBITDA increased 24.3% YoY to ₹205 crore, with margins expanding ~45 bps YoY to 9%. Adjusted PAT up 38.3% YoY. ECD revenue grew 19.4% to ₹1,634 crore, led by 40% growth in BLDC fans, double-digit growth in conventional pumps and water heaters, and over 20% growth in small domestic appliances. Lighting revenue increased 14.3% to ₹298 crore, while Butterfly revenue grew 15.9% to ₹331 crore. Commodity inflation continued to pressure gross margins, which declined to 29.8% from 31.6% a year ago.
Investment Rationale:
• Growth trajectory improving: The company has steadily improved revenue growth trajectory from single digit 3 quarters back to mid-high teens now. Double digit growth across all the businesses is noteworthy. Considerable part of the growth is supported by price hikes of 11-15% over the last 6 months. Volume growth although not very strong, is holding firm considering the hikes. The proportion of new businesses including solar products, wires and water purifiers shall increase from ~10% currently to 14-15% over medium term. Exports (largely fans currently) although a small portion in low single digit, has grown 70% YoY in Q2 with significant potential seen by management. Overall, core categories to deliver steady growth while new products to push overall growth in mid-teen trajectory.
• Margins currently impacted by commodity volatility; but shall eventually stabilise : Currently, geo-political tension led commodity inflation has impacted CGCE’s gross margin (Q2 at 29.8%: down 146 bps QoQ & 181 bps YoY) just as seen at industry level. CGCE expects ~80% of inflation to pass through price hikes and balance margin impact shall be offset by operating leverage and efficiencies. The fan segment has taken 17-18% price hike since last year while margin in B2B lighting is impacted owing to pre-contracted prices. Globally, the situation remains volatile while we believe CGCE is relatively better placed considering its market leadership, diversified product basket and strong balance sheet.
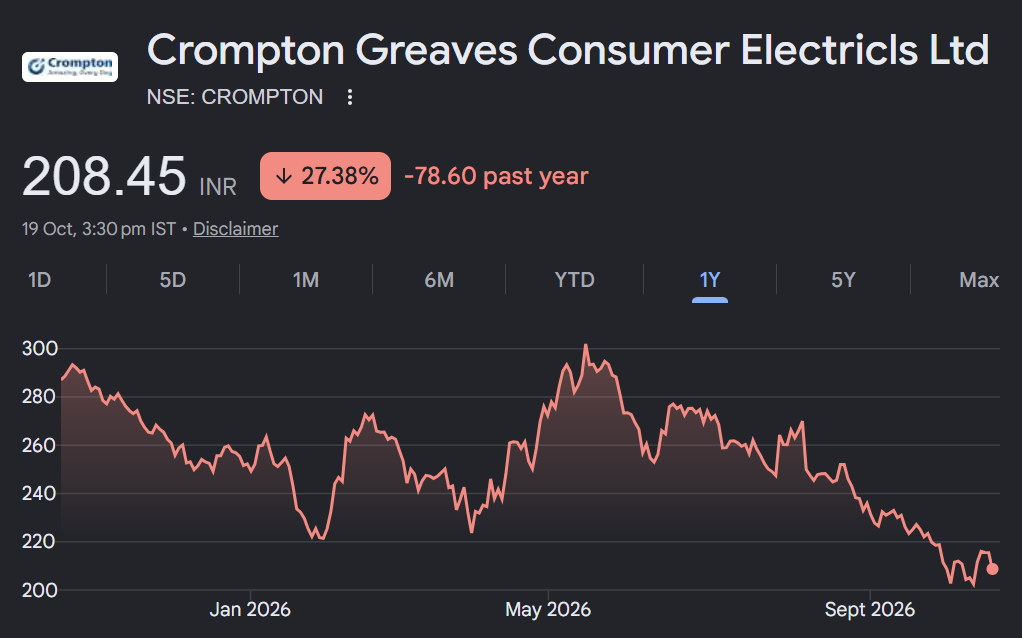
Rating and Target Price: Growth performance has been healthy across categories which remains key for long term business outlook. The capital employed in new segments is limited as manufacturing is largely outsourced which coupled with debt free balance sheet enables company to navigate current challenges effectively. Margin recoup remains key for profitability & return ratios improvement. We Maintain BUY rating on the stock with target price of ₹275 valuing the stock at 24x PE on FY28E EPS.