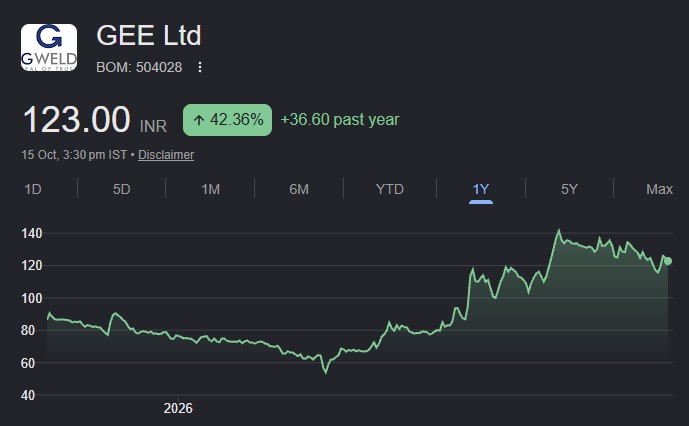
From recovery to high growth trajectory … About the company – GEE Limited is a leading manufacturer of welding consumables, with a diversified product portfolio spanning electrodes, MIG/TIG wires, submerged arc welding (SAW) wires and fluxes, and specialised welding consumables.
• GEE operates manufacturing facilities in Maharashtra and West Bengal, with an installed capacity of 59,075 MTPA, and is expanding its product portfolio into SAW and flux-cored wires to capture emerging opportunities in specialised welding applications.
Investment Rationale
• Capacity expansion and operating leverage to drive strong earnings growth : GEE is well positioned to deliver a strong earnings recovery, supported by the expansion of installed capacity from 59,075 MTPA to 71,339 MTPA and improving utilisation of its existing manufacturing facilities. Capacity utilisation improved from 48% in FY25 to 57% in FY26 and is estimated to increase to 60% in FY27E and 74% in FY28E. The company’s expanded capacity is estimated to support revenue potential of around ₹850 crore at a mature utilisation level, while planned capex of ₹30–40 crore over the next 3–4 years, including ₹5–10 crore in FY27, is expected to support capacity enhancement and operational efficiencies. We estimate revenue to grow from ₹369 crore in FY26 to ₹493 crore in FY27E and ₹614 crore in FY28E, implying a ~29% CAGR over FY26–28E. EBITDA is projected to increase from ₹33 crore to ₹61 crore over the same period, translating into ~36% CAGR, with margins improving from 9.0% to 10.0%.
• New product verticals to unlock incremental revenue potential : GEE is broadening its product portfolio through SAW wires, SAW fluxes and flux-cored wires, enabling it to address specialised welding requirements across heavy engineering, infrastructure and industrial applications. The company is establishing an initial flux-cored wire capacity of around 250 MT per month to be operationalise by Q3FY27 and plans to scale it to 1,000 MT per month by FY28, with management indicating potential revenue of over ₹150 crore from this vertical. Management targets revenue of ₹1,000 crore by FY29–30, with new product verticals expected to supplement the revenue potential of the expanded base capacity.
• Specialised welding capabilities to unlock nuclear and defence opportunities: GEE’s NPCIL approval strengthens its access to the highly regulated nuclear power segment, where technical qualifications create entry barriers. Management expects nuclear to contribute at least 10% of revenue in the coming years. In defence, GEE has supplied welding consumables for INS Dunagiri, INS Agray and INS Sanshodhak, reinforcing its credentials in naval shipbuilding. Shipbuilding-related opportunities are expected to contribute around 3–5% of revenue as flux-cored wire consumption scales up. These opportunities offer potential to improve product mix and diversify growth, although the timing of contribution will depend on order conversion and execution.
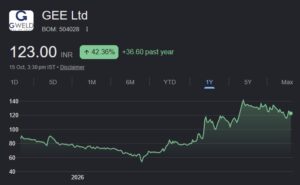
Rating and Target Price : We expect Revenue and PAT to grow at 29% and 66 % CAGR over FY26 – FY2 8E. We initiate BUY on GEE with a Target Price of ₹170 (based on 25x on FY28E EPS)