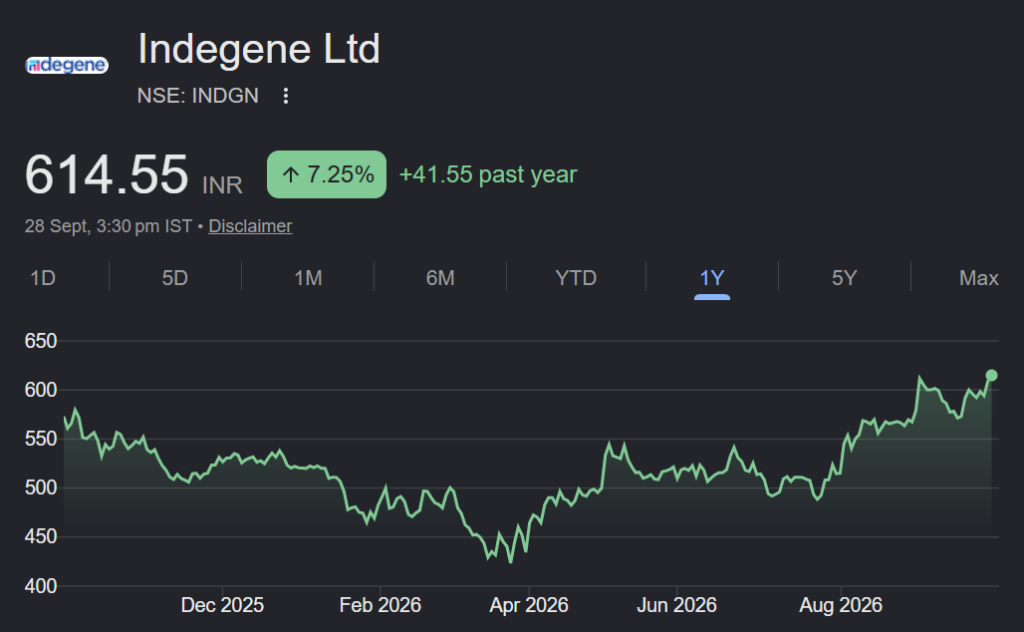
A life sciences workflow outsourcing growth story…
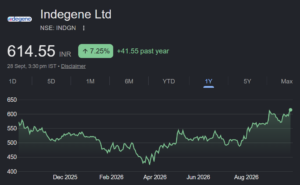
About the company – Indegene, founded in 1998, is a digital-first commercialization partner focused on the global life sciences industry. It serves 20/20 top biopharma companies and operates across 80+ markets through 17+ delivery and operational centres in 11+ countries.
Investment Rationale
Structural outsourcing opportunity in life sciences provides a growth runway: Indegene addresses a US$135bn+ life – sciences operations market across Marketing & Sales (US$55bn), Drug Discovery & Clinical Trials (US$36bn), Regulatory & Medical Affairs (US$24bn) and Pharmacovigilance (US$21bn) and Indegene estimates that outsourcing operations across these verticals grew at ~9– 14% CAGR during 2022–26. Marketing & Sales represents the largest component of the addressable TAM and is currently outsourced to the extent of 15-20% which is expected to increase to 25-30% by 2030, resulting in a ~6% CAGR growth in the outsourced marketing and sales spend pool. The underlying pharma market is also supportive, with global revenues expected to rise from ~US$1.4tn to >US$2tn by 2030. Going forward, management expects the global pharma industry to grow at 5 –8% CAGR during 2026 –28. Patent expiries, pricing pressure and productivity requirements should further support outsourcing adoption in Life Sciences operations. Thus, w e expect US$ revenue to grow at ~14% CAGR over FY26 –29E.
Deep domain expertise and embedded client relationships create a differentiated competitive EDGE: Indegene’s competitive positioning is supported by 27+ years of exclusive life – sciences experience, 5,500+ employees, 1,500+ life – sciences specialists and relationships with all 20 leading global biopharma companies . Its expertise across commercial, medical, regulatory and safety workflows, coupled with embedded client relationships, supports customer retention and account expansion. Net revenue retention has remained above 100% for the past five years, highlighting the potential to deepen existing customer relationships and expand wallet share. The delivery workforce comprises ~29% healthcare – qualified professionals and 25% technology professionals, supporting the execution of specialised life – sciences engagements . The Indegene EDGE is underpinned by four pillars – i) Embedded in Revenue, ii) Domain-Led Work, iii) GenAI Disruptor & iv) Outcome-Aligned Engagement Model.
A I led improving revenue productivity and operating leverage to support margin recovery : AI is increasingly becoming a differentiator in Indegene’s delivery model as it is embedding AI across content, medical writing, regulatory, pharmacovigilance & commercial workflows. This can improve employee productivity & reduce incremental cost of delivering services while expanding the addressable revenue pool by shifting previously internal or fragmented workflows toward technology- enabled operating partners. Early productivity indicators are encouraging. Revenue per employee increased from approximately US$56k three years ago to US$75k in FY26 and US$77.1k in Q1FY27. Management has indicated that AI – related revenue currently stands at ~ US$400mn, with a near – term opportunity exceeding US$500mn . We thus bake in EBITD A margins of 17.7%/19%/19% in FY27E/FY28E/FY29E , led by operating leverage & improving revenue productivity.
Rating and Target Price: We initiate our coverage on Indegene with a BUY rating and target price of ₹750 based on 27x FY2 8E EPS.