Multiple legs to the growth story: Key takeaways from our Singapore NDR
Offline to break-even soon; K12 to unlock the next phase of growth
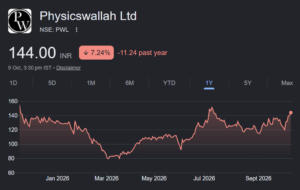
We hosted the Physicswallah’s (PWL) Co-founder, Mr. Prateek Maheshwari, for a three-day NDR in Singapore. Discussions centered around five themes: 1) online growth drivers, 2) the K-12 opportunity, 3) the path to offline profitability, 4) AI and the TUTO launch, and 5) capital allocation. PWL reiterated its FY27 guidance of 30% YoY total revenue growth and 100% YoY pre-Ind AS EBITDA growth. The team highlighted that online growth is no longer tied to JEE/NEET, as newer categories, including K-12 and state boards, scale at high margins. Offline is expected to near break-even in FY27, and admissions for the year are already closed. For online, we expect pre-IND AS EBITDA margins to remain in the 30-35% range over the next 4-5 years, with the potential to reach upwards of 40% over the medium term. Management also showcased several new initiatives, such as an AI-driven one-on-one tutor.
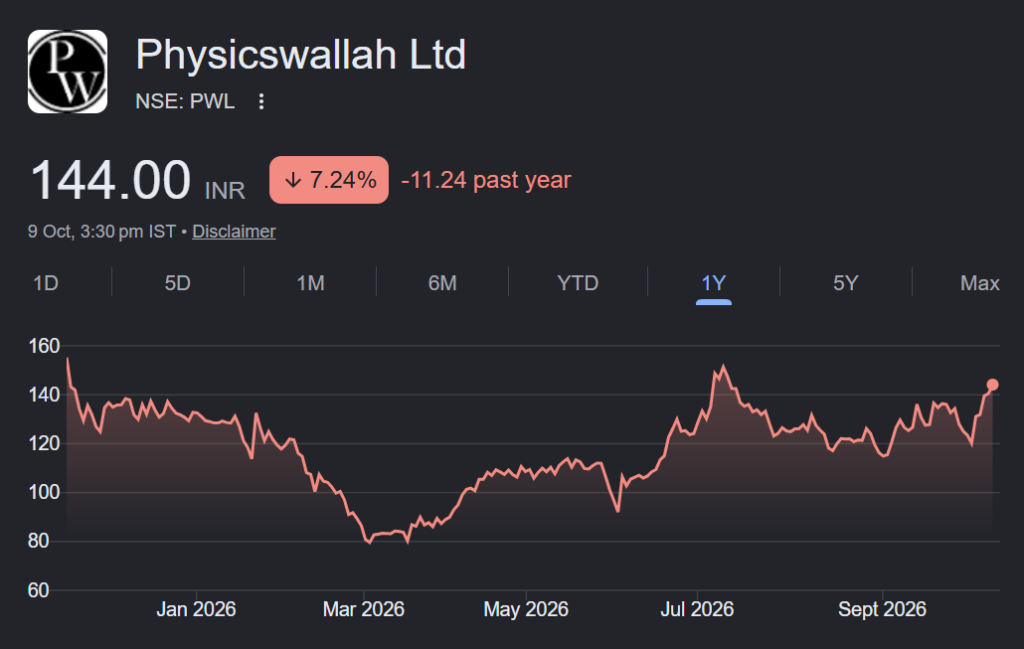
We believe PWL’s multiple independent growth legs provide comfort on ~30% online CAGR for the next 3-4 years, with a clear path toward sustained EBITDA improvement over the same period. We value PWL on an SoTP basis. We assign a multiple of 50x FY28E EV/EBITDA to the online business, reflecting its market leadership, scalable business model, and superior unit economics. We value the offline business at 15x FY28E EV/EBITDA to reflect its execution intensity, time to maturity, and lower margin profile. We value other businesses at 1x FY28E EV/sales. Adjusting for cash, we arrive at a TP of INR200, implying a 43% upside. We reiterate our BUY rating on the stock.