Strategic development towards long-term growth…
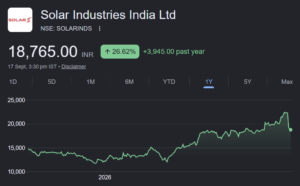
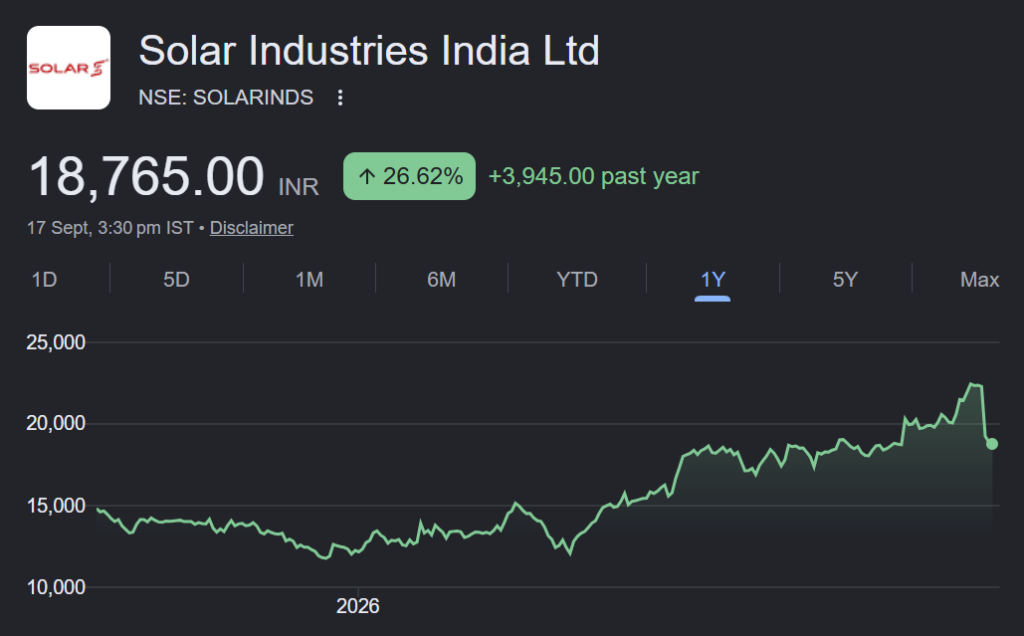
About the stock: Solar Industries (SIL) is one of the largest domestic manufacturers of bulk and cartridge explosives, detonators, detonating cords and components which find applications in the mining, infrastructure, construction industries
• Product range includes packaged explosives, initiating systems, UAS drones, ammunitions, military explosives, rocket integration, bombs etc.
Investment Rationale:
• Omnia acquisition strengthens Solar’s global explosives platform and opens a new leg of growth: The proposed US$1.35 billion (~₹12,951 crore) acquisition of Omnia materially strengthens Solar’s international explosives franchise, with combined annual revenue expected at ₹31,000-32,000 crore post-acquisition. The acquisition brings BME’s (blasting & metallurgy solutions segment) established presence in bulk emulsions, packaged explosives, initiation systems etc. across Africa and other global markets, while Omnia’s nitric acid and ammonium nitrate capabilities provide greater raw-material security and vertical integration. Solar can also leverage BME’s distribution network to expand its packaged explosives and initiating systems, while Problast’s down-the-hole capabilities add further synergies. With distribution reach increasing from ~90 to ~110 countries and manufacturing presence from 11 to 25+ countries, we believe the transaction as an extension of Solar’s existing global expansion strategy rather than a standalone diversification. The company is also benefiting from a favourable tailwind in global explosives & high-energy materials industry, with shortages of these key materials supporting higher realisations across both domestic and international markets
• Defence remains the key growth engine, now complemented by global scale-up: Solar’s defence business continues to scale up, with management reiterating that the ₹12,000+ crore defence capex programme remains on track and allocation towards defence will not decline. The company’s expanding portfolio across UAVs, counter-drone systems, missiles and other advanced munitions, along with a strong defence order pipeline, provides visibility for sustained growth. Management expects Solar standalone revenue at ~₹14,000 crore in FY27 with 28-29% EBITDA margin. Importantly, the Omnia acquisition is not at the expense of defence investments, while the enlarged global footprint could also create additional avenues for exporting Solar’s defence and explosives products.
Rating and Target Price:
• We have not factored in the Omnia’s acquisition in our financials for FY27E and FY28E, as we wait for its completion post all the required approvals. Though the margins and EPS of SIL would dilute by some extent after the full consolidation in FY29E (due to lower margins of Omnia), we believe that this acquisition would generate sizable opportunities for SIL in global explosives market and would be a value-accretive deal in longer-term
• We maintain BUY on Solar Industries with target price of ₹23,200 (based on 70x P/E on FY28E EPS)