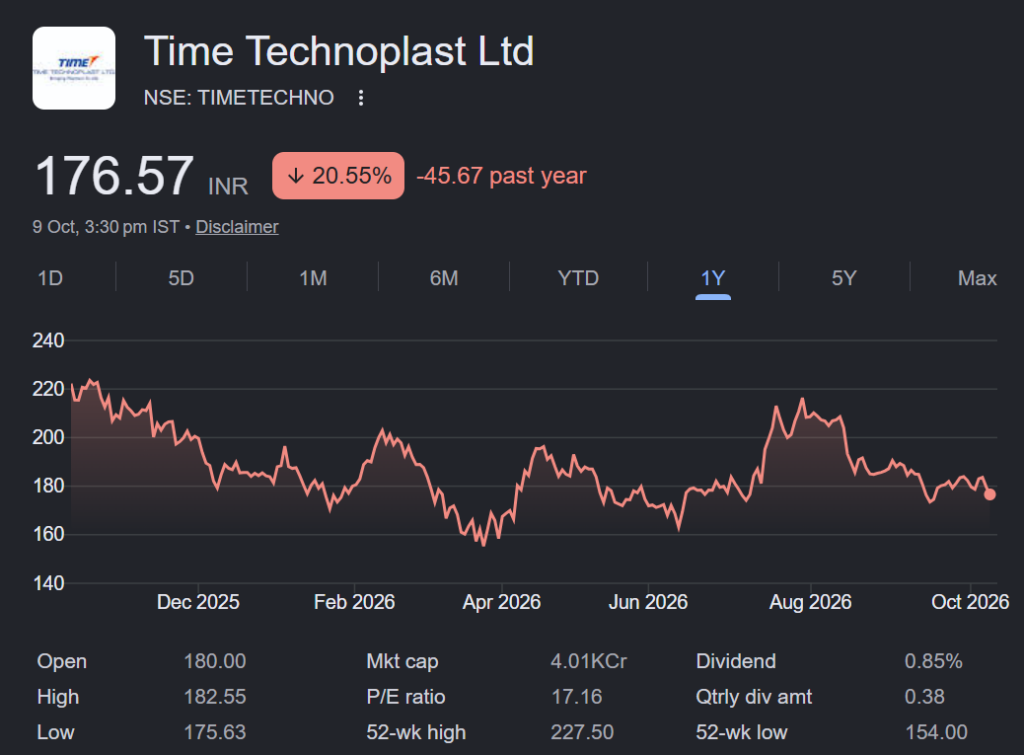
A Strong Core, with VAPs Driving the Next Leg of Growth – Initiate with BUY
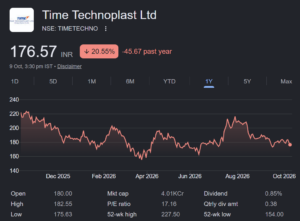
➢ Established in 1992, Time Technoplast (TIME) is a technology-driven polymer and composite products company with ~Rs 61bn of FY26 revenue. The company operates across Industrial Packaging, IBCs, Composite Cylinders, PE Pipes and other technical products. It has 24 manufacturing plants in India and 10 overseas facilities, exports to 66+ countries and serves 900+ institutional customers, with ~92% of revenue coming from institutional clients. Industrial Packaging contributes ~61% of revenue, while Value-Added Products have steadily increased their contribution to ~28% in FY26 from ~20% in FY21. This mix shift is gradually increasing the company’s exposure to higher-growth and higher- margin businesses.
➢ TIME is well positioned to benefit from (a) continued growth in industrial packaging and steel-to- polymer conversion, (b) rising contribution from higher-margin VAPs such as IBCs and Composite Cylinders, (c) increasing CNG infrastructure and adoption of Type-IV CNG cascades, (d) growth in PE Pipes and other technical applications, and (e) higher utilization, moderating capex, deleveraging and working-capital improvement, which together can support earnings growth and RoCE expansion. We expect revenue/EBITDA/PAT to grow at 13%/14%/19% CAGR over FY26-29E.
➢ We Initiate coverage with BUY rating and Dec’27 TP of Rs 275 set at 18x on 1Y fwd. EPS