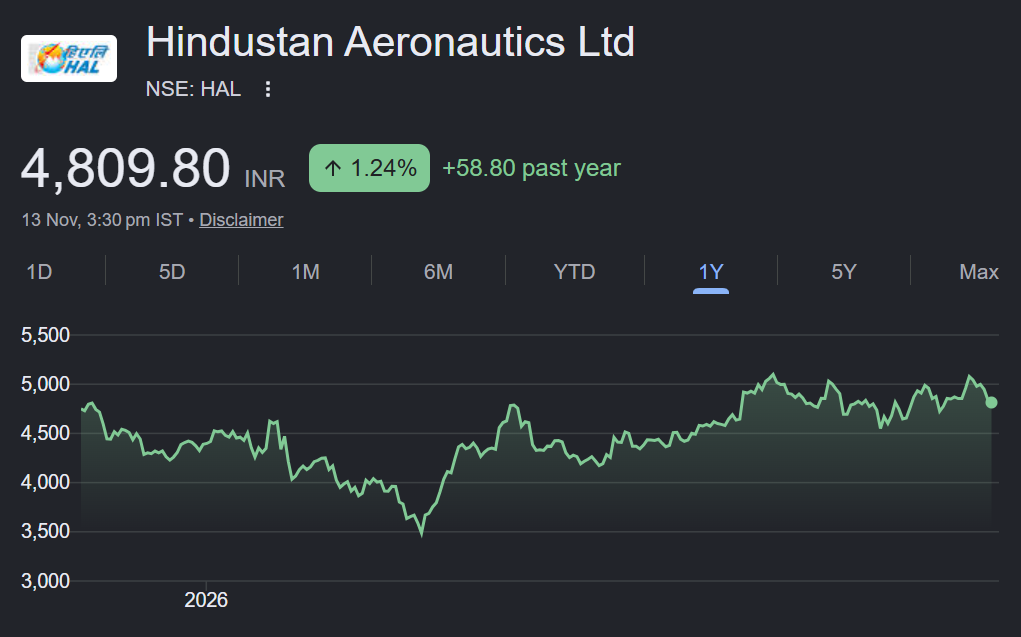
Improving execution and expanding capabilities to drive growth…
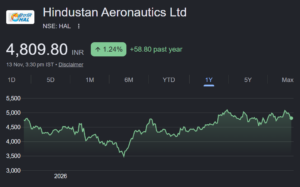
About the stock : Hindustan Aeronautics (HAL), one of the largest Defence PSU in India, is engaged in design, development, manufacture, repair, overhaul, upgrade and servicing of a wide range of products including, aircraft, helicopters, aero- engines, avionics, accessories and aerospace structures. • Company’s order backlog is expected to be at ~₹ 2.5 lakh crores
Investment Rationale:
• Improving execution across aircraft and helicopter programmes to drive growth: HAL reported revenue growth of ~15% YoY in both Q2FY27 and H1FY27. We believe execution across LCA Tejas, helicopters, engines and other manufacturing programmes should support growth as company is entering a stronger execution phase. HAL has commenced production of 156 Prachand LCHs with manufacturing 90 fuselage structures (partnering with BEML and Adani Defence). Company also partnered with Safran to develop and manufacture the Aravalli engine for its future IMRH and DBMRH helicopter programmes. Further, HAL handed over the final two LCA Tejas Mk1 FOC twin-seat trainers, three HTT-40 trainers and four Dhruv NG helicopters during Sept-26. On the Tejas Mk1A programme, HAL has prepared 27 aircraft airframes, while GE engine supplies have improved to 14 units (GE targets to deliver 28 by FY27E), with management aiming to deliver 10 jets by Mar-27 and 24+ jets annually post engines supply stabilisation. Revenue guidance for FY27 is at 10–12% with EBITDA margin at ~30–31%, going ahead improving execution and operating leverage provide earnings recovery
• Large order backlog and expanding engine capabilities support long-term growth visibility: HAL’s consolidated order backlog stands at ~₹2.5 lakh crore (7.5x TTM revenue) providing strong revenue visibility, while the pipeline across Tejas Mk2, helicopters, Su-30MKI upgrades and other next- generation platforms offers opportunities beyond the current programmes. HAL is increasing annual production capacity for AL-31FP engines from 30 to 50 units with an investment of ₹335 crore and is setting up a second Shakti engine production line with an investment of ₹218 crore, targeting capacity of up to 100 engines annually by FY29. Further, GE has been placed an order for 113 additional F404 engines for the second batch of 97 Tejas Mk1A aircraft, with deliveries scheduled in 2027-32. HAL has also acquired the remaining 50% stake in HATSOFF Helicopter Training, making it a wholly owned subsidiary and strengthening its presence in helicopter training and simulation. These initiatives are expected to strengthen HAL’s manufacturing capabilities and support its long-term growth.
Rating and Target Price:
• We believe that HAL is strongly placed to benefit from pick-up in execution of existing strong order backlog and robust pipeline. We estimate revenue CAGR of ~16% over FY26-28E with EBITDA margin sustaining at ~30% (in- line with management’s guidance). We maintain BUY on HAL with a target price of ₹ 5820 per share (based on 32x FY28E EPS)