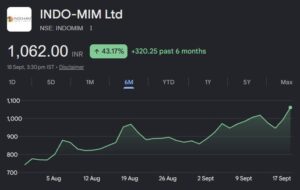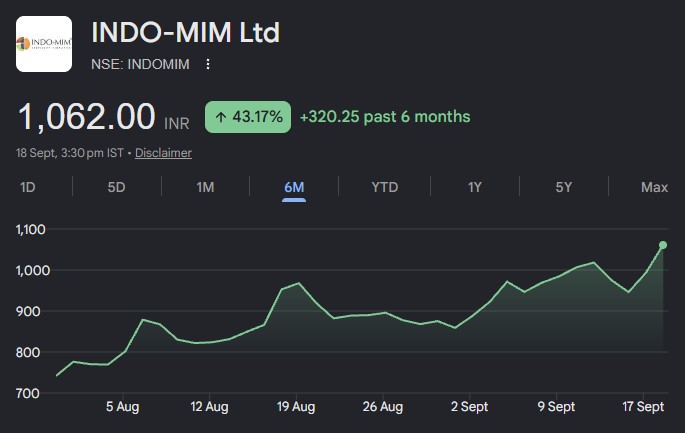
HDFC Securities has initiated coverage on Indo-MIM Ltd with a Buy rating and a target price of ₹1,407, implying an upside of around 42% from the level considered in its report. The brokerage believes Indo-MIM is emerging as a differentiated advanced manufacturing player, with its leadership in metal injection moulding (MIM), strong relationships with global OEMs and increasing exposure to next-generation manufacturing opportunities.
According to HDFC Securities, Indo-MIM has a ~7% share of the global MIM market, making it the world’s largest manufacturer of precision engineering components using MIM technology.
The brokerage believes the company has “only scratched the surface” of its opportunity as demand increases for complex, miniaturised and high-precision components across industries ranging from aerospace and defence to data centres, automation and space technology.
Global leader in metal injection moulding
Metal injection moulding is a specialised manufacturing technology used to produce complex, small and precision components at scale. It can be particularly valuable where conventional machining or manufacturing processes are less efficient.
Indo-MIM has built significant capabilities around MIM over several decades and has supplemented this technology with a broader manufacturing portfolio that includes investment casting, precision machining, ceramic injection moulding and metal 3D printing.
This combination allows the company to act as a one-stop advanced manufacturing partner for OEMs looking for complex and mission-critical components.
HDFC Securities believes this diversified technology stack is an important competitive advantage because customers can potentially source multiple types of precision components from the same manufacturing partner.
Deep presence in the US manufacturing ecosystem
One of the key pillars of the Indo-MIM investment thesis is its presence in the US manufacturing ecosystem.
The company has developed relationships with leading US multinational corporations and enjoys significant wallet share with some of its customers. HDFC Securities believes Indo-MIM is well-entrenched in the innovation and manufacturing ecosystem in the US, creating opportunities for deeper engagement with existing customers as well as new programs.
The brokerage sees high customer wallet share, onsite presence and deep involvement in innovation programs as important entry barriers.
For an advanced manufacturing supplier, winning an initial program can require substantial engineering collaboration, qualification, tooling and process development. Once a supplier becomes embedded in a customer’s product development and manufacturing process, replacing it can become difficult.
Tariff insulation could be a major advantage
The ongoing shift towards supply-chain diversification and manufacturing outside China is another major opportunity for Indo-MIM.
HDFC Securities believes the company is relatively well-insulated against tariff-related disruptions because of its onsite manufacturing capabilities.
This is particularly relevant as global OEMs seek to diversify their supply chains and establish manufacturing ecosystems closer to end markets.
The brokerage expects Indo-MIM to benefit from the broader “ex-China” supply-chain opportunity for US manufacturing, potentially creating additional business opportunities with American customers.
Defence spending provides another growth avenue
The report also highlights increasing US defence spending and efforts to strengthen domestic and allied manufacturing capabilities.
HDFC Securities expects Indo-MIM to potentially benefit from increased capex by the US Department of Defence, including opportunities linked to drone programmes and other defence applications.
The company’s ability to manufacture lightweight, complex and precision components could make its technology relevant to several emerging defence applications.
However, the opportunity extends beyond defence.
Humanoids, satellites, space and data centres
HDFC Securities believes several emerging industries could become meaningful growth drivers for Indo-MIM over the next few years.
These include:
- Humanoid robots
- Satellite internet
- Space travel and aerospace
- Data centres
- Automation equipment
- Advanced manufacturing systems
- Defence and drone programmes
The common denominator is the increasing requirement for components that are compact, complex, lightweight, precise and capable of meeting stringent performance requirements.
As these industries move from development into commercial-scale production, suppliers with established precision-manufacturing capabilities could see their addressable market expand.
Extremely high entry barriers
A major part of the investment case rests on the barriers to entry in MIM and advanced manufacturing.
According to HDFC Securities, Indo-MIM’s competitive moat is not simply its manufacturing capacity. It includes its technology capabilities, engineering expertise, customer relationships, onsite presence and participation in customer innovation programmes.
The company has spent years developing processes and capabilities that can be difficult for new entrants to replicate.
The brokerage believes high share of client wallet, stringent qualification requirements and close customer integration create significant barriers to competition.
This could also provide Indo-MIM with greater visibility as customers scale new products.
Capacity could be the key constraint
Interestingly, HDFC Securities believes that the biggest limitation to Indo-MIM’s growth may not be demand but rather how quickly the company can add capacity and convert emerging opportunities into commercial production.
If new programmes in aerospace, defence, automation, data centres and other advanced industries scale up, the company may need to continuously invest in manufacturing capacity.
This creates a potentially attractive operating environment: increasing customer demand combined with high entry barriers could allow existing players such as Indo-MIM to capture a disproportionate share of incremental business.
Valuation rerating potential
HDFC Securities expects Indo-MIM’s valuation multiple to potentially rerate as investors increasingly recognise the company’s position in advanced manufacturing and its exposure to emerging technology themes.
The brokerage believes Indo-MIM could eventually trade in line with or at a premium to multinational capital-goods companies, given its differentiated manufacturing capabilities and exposure to high-growth end markets.
HDFC Securities has valued the company at 54x September 2028 estimated EPS and arrived at a target price of ₹1,407.
The target represents approximately 42% upside, according to the report.
Investment thesis
The Indo-MIM story is therefore moving beyond being simply a play on metal injection moulding.
Its broader proposition combines advanced manufacturing technology, global OEM relationships, US manufacturing exposure and participation in emerging industries.
The company’s ~7% global MIM market share provides scale, while its capabilities in precision machining, investment casting, ceramic injection moulding and 3D printing broaden its addressable market.
The potential acceleration of US defence spending, ex-China supply-chain diversification and emerging applications such as humanoids, space technology, satellite communications, data centres and automation could provide additional growth opportunities.
The key monitorable, according to the HDFC Securities thesis, is the company’s ability to add capacity fast enough to capture the opportunities emerging across these markets.
HDFC Securities’ key investment points
| Factor | HDFC Securities’ view |
|---|---|
| MIM market share | ~7% globally |
| Market position | World’s largest MIM manufacturer |
| Customer base | Leading US MNCs |
| Technologies | MIM, investment casting, precision machining, ceramic injection moulding, 3D printing |
| Key opportunity | Ex-China manufacturing shift |
| Emerging markets | Defence, drones, aerospace, space, humanoids, data centres, automation |
| Competitive advantage | Customer integration, technology, qualification barriers and onsite presence |
| Tariff exposure | Relatively insulated due to onsite manufacturing |
| Target price | ₹1,407 |
| Upside | ~42% |
| Valuation | 54x September 2028E EPS |
| Rating | Buy |
Bottom line
Indo-MIM is increasingly positioning itself as an advanced manufacturing partner rather than merely a component manufacturer. Its global scale in MIM, deep relationships with US multinational customers and ability to combine multiple precision-manufacturing technologies provide a differentiated proposition.
HDFC Securities believes the company is still in the early stages of monetising opportunities in next-generation manufacturing. If emerging applications such as defence, drones, aerospace, humanoids, data centres and space translate into meaningful production programmes, the addressable opportunity could expand significantly.
With HDFC Securities initiating coverage with a Buy rating and ₹1,407 target price, the brokerage’s central thesis is that Indo-MIM’s combination of high entry barriers, customer stickiness, US exposure and multiple structural growth opportunities could support both earnings growth and a valuation rerating over the coming years.
The above article is based on the investment thesis and estimates contained in the HDFC Securities research report. Investors should independently evaluate the company’s financials, valuation, risks and suitability before making investment decisions.