Building a distinct lending model – funding the INR 0.15–0.5mn micro-enterprise space
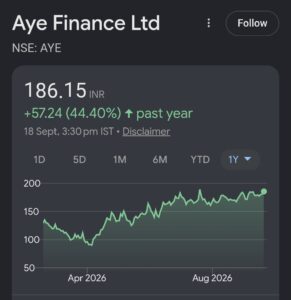
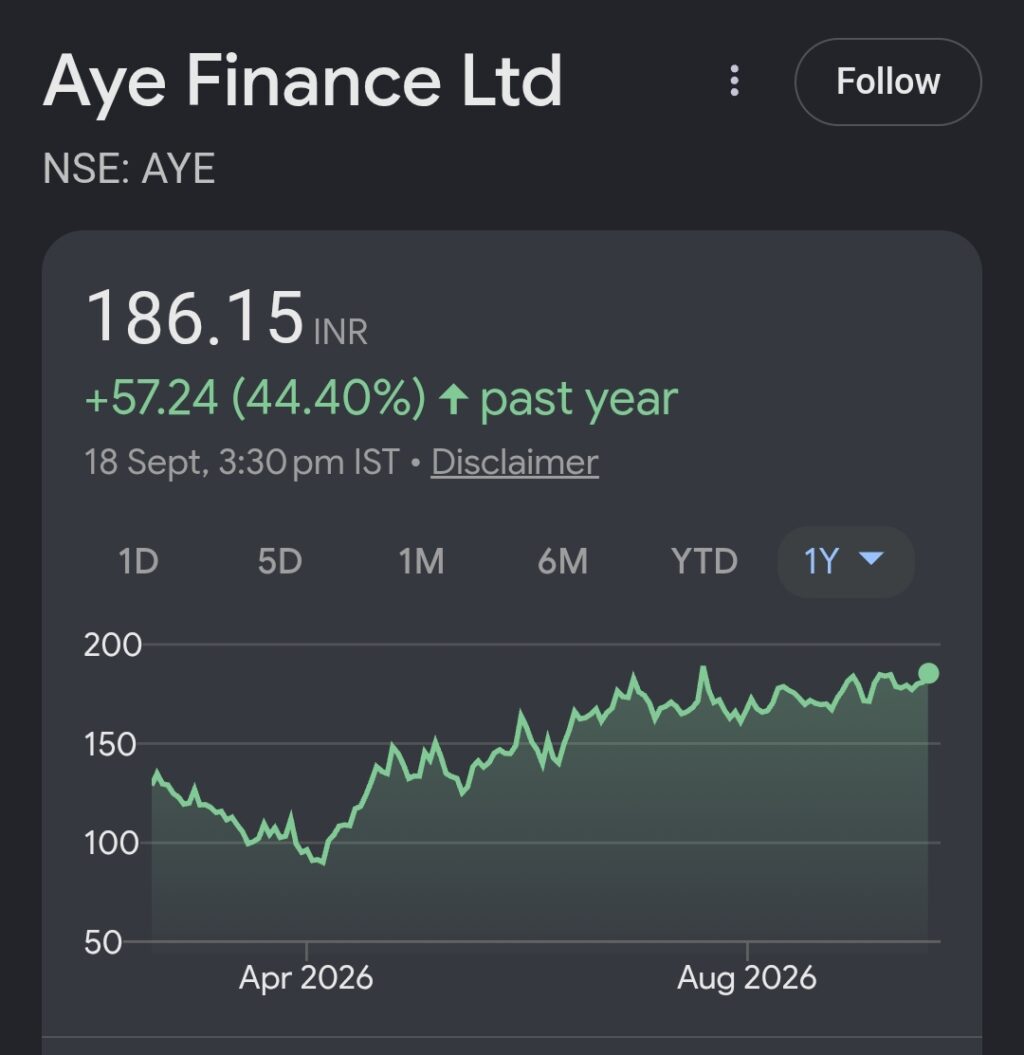
Aye Finance (Aye) has a formidable presence in India’s mass-affluent lending market. Aye is anchored by its niche funding offerings in the INR 0.15mn–0.5mn ticket size segment. Typically, a customer’s financial (fund seeking) lifecycle formally begins with microfinance/digital loans (<INR 0.15mn). As the customer’s income grows, the need graduates (>INR 0.5mn) to micro-LAP, affordable mortgage and vehicle loans. Yet, a sizeable white space exists in the INR 0.15mn–0.5mn funding bracket. Most of its peers operate either below INR 0.15mn (MFIs/digital lenders) or above INR 0.5mn (S-LAP/AHFC). Aye lays emphasis on bridging this gap. The company’s distinct business model is helping propel it as one of the fastest- growing NBFCs (FY20–26 AUM CAGR of ~26%) with improving earnings (2.7% RoA in FY26 vs. 2% in FY23).
Bridging the INR 0.15mn–0.5mn gap
While most competitors approach SME lending with traditional security (immovable property leading to ticket size exceeding INR 0.5mn), Aye focuses on MSE lending with unconventional security (inventory hypothecation keeping ticket sizes aligned with customer requirement). Its unique customer base (NTC customers) at ~37% reflects an under-penetrated micro-enterprise market. The company benefits from a dual advantage of: 1) cherry-picking quality customers; and 2) outpacing systemic credit growth. This dominant position in the INR 0.15–0.5mn ticket size segment is supported by its cluster- based underwriting capabilities – a key competitive moat providing strong pricing power – asset yields sustain at >22% cross cycle.
Improving earning trajectory to continue
We initiative coverage with a BUY rating and target price of INR 285, valuing at 2x FY28E P/BV. Notably, Aye is gradually emerging from an asset quality (AQ) cycle and has demonstrated a steady improvement in core earnings in recent quarters. Credit cost has consistently declined from 5% in FY26 to sub- 4% in Q1FY27. Spread expanded to 11.6% by Jun’26, from 10.9% in Jun’25, supported by a reduction of >45bps in the Cost of Funds (CoF), alongside an incremental CoF that remains at 10.2% (book cost at 10.8%), which could further support spreads. Driven by enhanced operating efficiency, overall RoE
improved to 16% by Q4FY26, from ~9–10% in the past seven quarters.