Execution discipline: The real differentiator
▪ NAM India posts highest market share growth amongst top 10 AMCs over 3 years
▪ NAM India climbs to 4th largest HNI player on back of active-passive combination
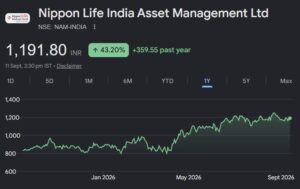
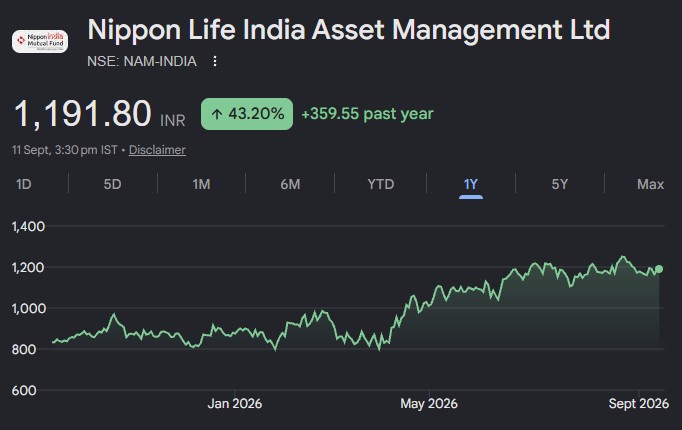
▪ We maintain BUY with TP of Rs 1,395, valuing stock at 37x Sept’28E EPS, and reaffirm NAM as our top pick in the sector
A multi-year investment opportunity from Japan: The management flagged a structural, longer duration opportunity stemming from Japan where one-third of Japanese financial assets are invested outside Japan while only 1% of the investments is flowing to India – framing this as a multi-year opportunity to capture incremental flows as and when that shift occurs. At present, Japanese investment into India is channeled primarily through FDIs. As Japanese allocations to India expand over time, however, NAM India’s parentage could give it an edge in capturing these incremental cross-border flows relative to domestically owned AMCs.
Real strength lies in execution: NAM’s strategy is characterized less by the ambition of its plans and more by the consistency of execution on the ground. Strategic intent translates reliably into measurable outcomes: MFD partners with AUM exceeding Rs 250 mn have grown 3.5x (from ~300 to 1,050+) since 2022, while partners above Rs 500 mn AUM have expanded 4.7x, supported by sustained engagement and capability-building initiatives such as Ascend and the Learning Edge Academy. This execution discipline extends to investor communication, particularly in retention management, reinforced by an early-warning system for distributors following a structured email-then-call escalation protocol. This diversified, execution-led approach is also evident in distribution resilience – NAM India has scaled successfully without being a bank-backed AMC, with no single distributor, including its 102 banking partners, contributing more than 5% of assets.
Maintain BUY: NAM India continued to report a strong performance with steady market share gains, reporting overall market share gains of 54bps YoY in Q1FY27. It continues to benefit from the consistent long-term fund performance, aiding steady flows and thereby better-than-industry performance. Hence, aided by industry-leading AUM growth, highest investor base with steady SIP flows and market share gains coupled with favourable product mix, we maintain positive view on the company with BUY and TP of Rs 1,395 (Rs 1,339 earlier), valuing the stock at 37x Sept28E EPS, and reaffirm NAM as our top pick.