Large scale dialysis player with global aspirations…
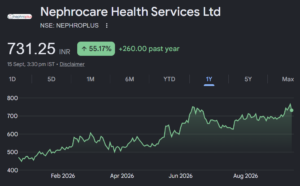
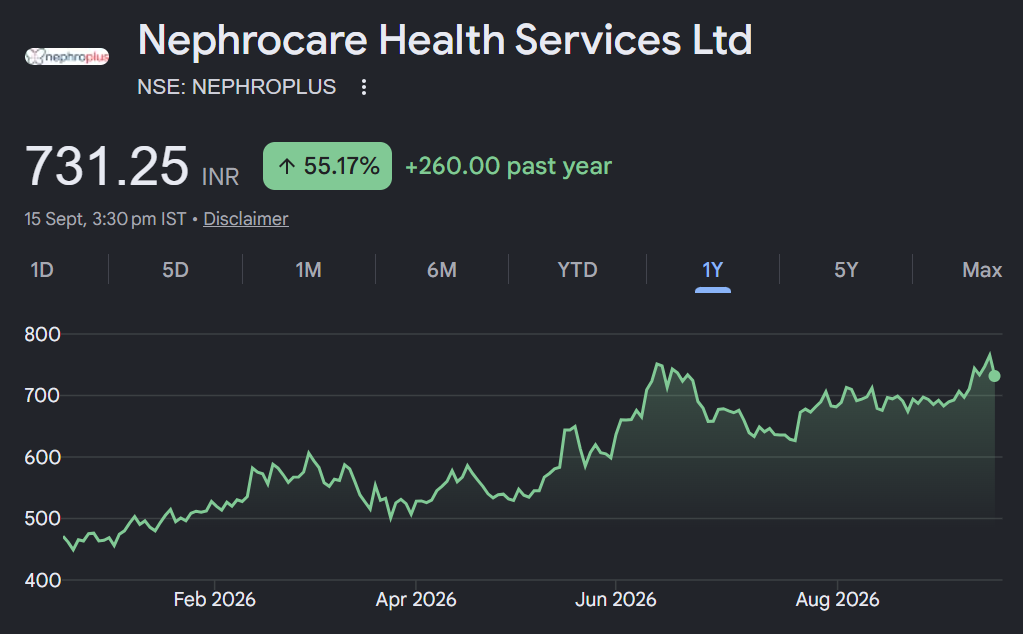
About the stock : Established in 2009, Nephrocare Health Services Ltd (Nephrocare) is the largest dialysis services provider in India and Asia, delivering end-to-end renal care through a network of 550 clinics. It owns the NephroPlus brand, through which it operates clinics across three formats- captive setups in hospitals, standalone clinics and public private partnerships.
• Outside India, Nephrocare has presence in the Philippines, Uzbekistan, and Nepal, and has recently entered Saudi Arabia and Kazakhstan.
• FY26 Revenues Mix – India – 58%; International – 42%
Investment Rationale:
• Time tested dialysis chain model with high potential – From one clinic in 2010 to 468 clinics in 2026, Nephrocare has come a long way to establish itself as one of the fastest growing healthcare providers with focus on dialysis care. Chronic Kidney Disease (CKD) has emerged as an important chronic disease in India due to growing diabetes and hypertension instances. However, only 15% of the CKD patients have access to dialysis (only cure besides kidney transplant) due to constraints such as accessibility and affordability. To cater to the unmet needs, India needs to nearly double the existing dialysis infrastructure. With~50% market share in the organised space, Nephrocare is well placed to capture the opportunity. We expect India sales to grow at a CAGR of 12% to ₹727.1 crore, during FY26-28E.
• Asia expansion based on similar potential with better unit economics : Identifying similar potential in the Philippines and Uzbekistan (only ~30% CKD patients having dialysis access), the company entered into these markets during the last 5-6 years. It operates 44 clinics in the Philippines and 6 in Uzbekistan including the world’s largest 165-bed dialysis centre. The realisation per dialysis session is far better in both these countries. Encouraged by the success with its ability to offer prices at a significant discount compared to local players and an efficient cost management, the company is targeting new geographies. We expect international revenues to grow at a CAGR of 24% to ₹ 641.2 crore, during FY26-28E.
• Asset – Light model to enable expansion and profitability with scalability – The company’s asset-light model enables rapid expansion, with most greenfield clinics achieving breakeven within 3–4 months whereas captive/Brownfield -led rollout (~52% of current clinics) supports breakeven from Day 1. A cluster-based strategy drives operating leverage and deep penetration in tier II/III markets, which contribute over 77% of the revenues. The economics and demand underpin planned addition of ~150 new centres in India with ~60% being Brownfield. We believe the scale advantages and backward integration to continue to support strong unit economics.
Rating and Target Price : Maintain a BUY with a TP of ₹900 based on 27x FY28E EBITDA of ₹325 crore.