FY30 Vision: Scaling revenues, margins and capacity …
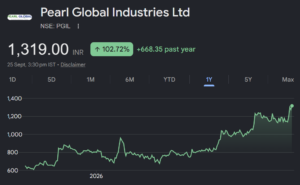
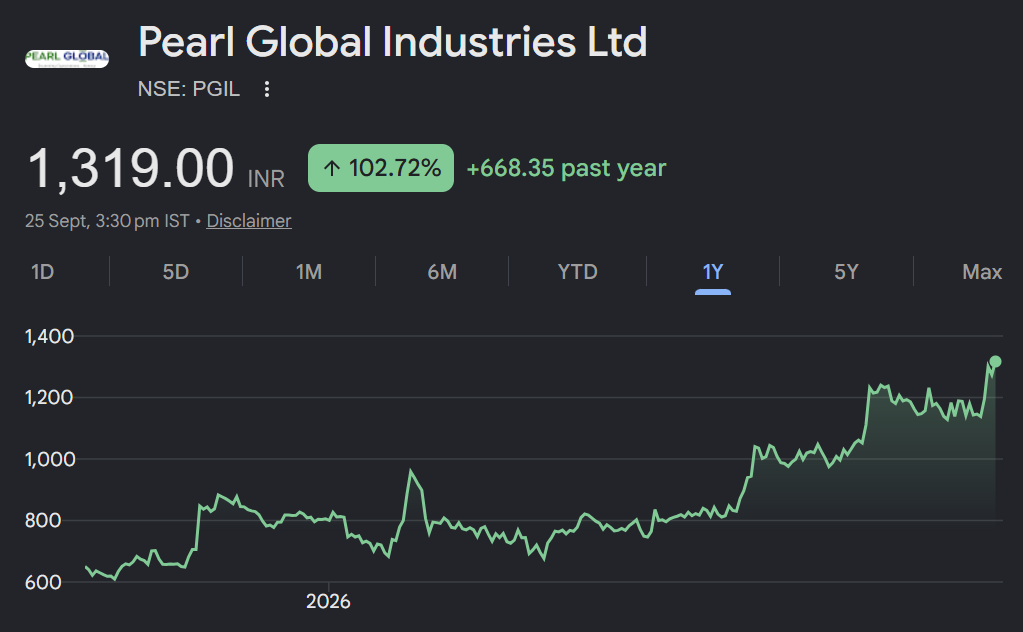
About the stock : Pearl Global Industries Ltd. (PGIL) is a multi-national apparel manufacturer offering end-to end sustainable solutions across the fashion value chain. It has 25 manufacturing facilities with capacity of ~108mn pieces across multiple locations such as India, Bangladesh, Vietnam and Indonesia, etc.
Investment Rationale:
Capacity expansion to 170 – 175mn pieces by FY30 to maximise growth opportunities: Diversification of production base provides strategic advantage to PGIL over its domestic peers to improve its export share in the key international markets. Considering it as an opportunity, the company is planning to expand its apparel manufacturing capacity to 170-175mn pieces from 101mn pieces in FY26. Barring India, its capacities in Bangladesh, Vietnam, Indonesia and Guatemala are operating at a capacity utilisation of 80-90%, which compels to expand capacities in this region considering the growth opportunities ahead. Though India’s utilisation level is currently at 62%, FTA with various countries and incentive benefits provided by various states to set-up textile units are attractive enough to expand capacity in the coming years. Out of 70-75mn pieces of capacity expansion around 30mn pieces expansion is approved by board. Around 20mn pieces approved expansion will come-in in FY27. The company planning to spend Rs350cr for capacity expansion, which will be funded through internal accruals.
Targets revenues of Rs90 – 100bn by FY30; to grow at CAGR of 16 – 18%: Diversified production base and customer base aided the company to sail through global uncertainties including Russia-Ukraine/west Asia war and higher US tariff rates. Its revenues at a CAGR of 17% over FY23-26 to Rs5,025cr in FY26. Management targets its revenues to reach Rs9,000-10,000cr by FY30 (growing at 16-18% over FY26-30). This will be driven by adding new customers, strengthening relationship with existing customers, entering new categories and improved efficiencies along with better utilisation. PGIL’s apparel capacity to expand at ~14% over FY26-30. On FTA front, UK revenues are expected to grow 2-3x over the next three years. Thus, revenue contribution from UK is expected to increase to ~10% by FY30 from 4% in FY26. Similar opportunities are expected from FTA with EU in the coming years.
Operating leverage and backward integration projects to drive margin expansion: PGIL’s EBIDTA margin expanded by 110bps to 9.2% over FY23-26 despite various uncertainties. Management expects EBIDTA margins to expand by 300-500bps over FY26-30 to 12-14% to FY30. This will be driven by improved EBIDTA margins in India business (currently ~6%), better utilisation in high margin export countries such as Vietnam and Bangladesh, 40-50bps margin expansion because of newly operational washing unit in Bangladesh and backward integration through setting up of high margin Knitting unit.
Rating and Target Price: We have increased our earnings estimates by 3-4% for FY27 and FY28 while we have introduced FY29 estimates through this note. We upgrade our recommendation to Buy from Hold earlier with a revised price target of Rs1,600 (valuing at 26x FY29E EPS of Rs .61.6).