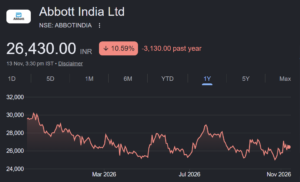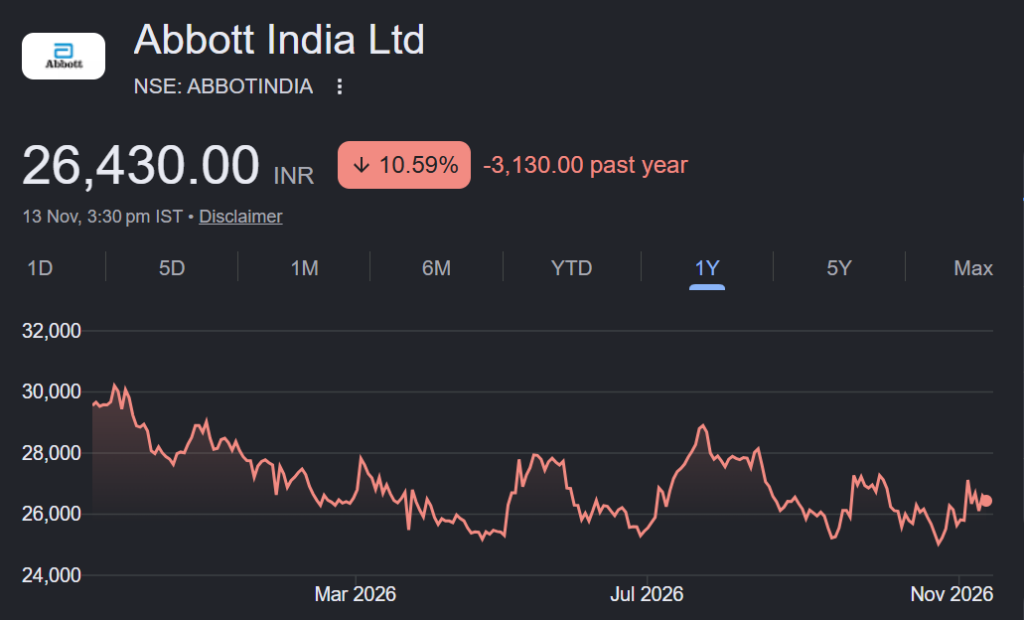
ICICI Direct has recommended a Buy on Abbott India, setting a target price of ₹32,810, implying an upside potential of approximately 24% from the prevailing market price. The brokerage believes that the company’s strong portfolio of established brands, consistent new product launches and resilient profitability justify its premium valuation.
In its latest research report titled “Ex-Novo Power Brands Continue to Deliver”, ICICI Direct highlighted Abbott India’s ability to sustain market-aligned growth despite some moderation in select legacy and marketed brands.
Strong portfolio of over 140 brands
Abbott India is among the fastest-growing multinational pharmaceutical companies in the Indian market. It has a strong therapeutic presence across Gynaecology, Gastroenterology, Hormones, Pain Management and Central Nervous System (CNS), supported by a portfolio of more than 140 brands.
Some of its leading brands include Thyronorm in the hormones segment; Udiliv, Duphalac and Cremaffin Plus in Gastroenterology; Duphaston in Gynaecology; and Vertin in CNS.
The company also markets selected leading brands of Novo Nordisk and Abbott Healthcare, earning distribution margins from these arrangements.
Q2FY27: Revenue grows 11%, EBITDA rises 13%
Abbott India reported a steady performance in Q2FY27, with revenue growing 11% year-on-year to ₹1,951 crore.
According to IQVIA data, several of the company’s key brands continued to deliver healthy growth. These included Udiliv, Ryzodeg, Influvac and Cremaffin Plus.
However, growth in Thyronorm moderated during the quarter, while certain marketed brands, including Novo Nordisk’s Rybelsus, Mixtard and Novomix, registered a decline.
Despite these variations across individual brands, the company’s operating performance remained resilient.
EBITDA increased approximately 13% year-on-year to ₹568 crore, while EBITDA margins expanded by around 53 basis points to 29.1%. Profit after tax (PAT) grew 9% to approximately ₹453.5 crore.
The expansion in margins indicates that Abbott India has been able to maintain profitability even while navigating changes in its product portfolio.
Legacy and new power brands continue to deliver
ICICI Direct believes that Abbott India’s underlying brand performance remains encouraging. The company is adopting a calibrated approach to portfolio management, including an optical adjustment in slower-moving Novo brands and the induction of newer products in the GLP-1 segment, including Wegovy.
The brokerage notes that the company’s legacy and new power brands have consistently delivered growth of around 12-15%, according to IQVIA data.
Its analysis suggests that the reported growth of the top 10 brands does not fully capture the underlying momentum because of the performance of certain products undergoing portfolio transitions.
Excluding Mixtard, which is being gradually discontinued, and Rybelsus, which is being replaced by newer semaglutide brands, the top 10 brands could have delivered a CAGR of approximately 13% over MAT September 2023-26, with year-on-year growth of around 14% in MAT September 2026.
This compares with the reported CAGR of approximately 9% and year-on-year growth of 4%.
ICICI Direct believes this adjusted performance provides a better indication of the underlying strength of Abbott India’s key brands.
Focus on new launches and emerging therapies
An important element of Abbott India’s growth strategy is its consistent product launch momentum.
The company has introduced more than 100 products over the past 12 years and has another 75 launches planned over the next five years.
ICICI Direct considers this launch trajectory a significant competitive advantage, particularly given the company’s established distribution network and strong brand recognition among doctors and patients.
The company is also focusing on emerging therapeutic areas with significant unmet medical needs. It is adapting its go-to-market strategy to changing healthcare delivery models and strengthening its presence across institutional channels, corporate hospitals and specialty networks.
These initiatives, supported by targeted capability building and more market-specific execution, are expected to help the company sustain growth while improving operating efficiency.
Target price of ₹32,810 based on 36x FY28E earnings
ICICI Direct has valued Abbott India at 36 times its estimated FY28 earnings per share of ₹911.30, arriving at a target price of ₹32,810.
The brokerage believes that the premium valuation is justified by the company’s strong brand franchise, customer stickiness, consistent product launches and ability to deliver relatively stable growth.
With legacy brands continuing to perform well, newer power brands gaining traction and a healthy product pipeline, Abbott India remains a standout performer among multinational pharmaceutical companies, according to the brokerage.
Investment outlook
ICICI Direct’s positive outlook rests on Abbott India’s ability to combine the strength of its established brands with a steady pipeline of new products. While certain marketed brands have experienced temporary weakness or portfolio adjustments, the brokerage believes that the underlying growth momentum remains healthy.
The company’s strong margins, consistent profitability and expansion into emerging therapeutic segments provide further support to its investment case.
ICICI Direct has therefore maintained a positive view on Abbott India, recommending Buy with a target price of ₹32,810, representing an upside potential of approximately 24%.
Source: ICICI Direct Research Report.