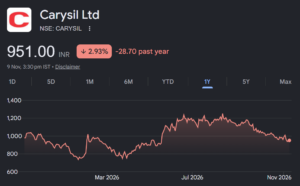
The positive outlook is underpinned by healthy volume growth, increasing demand in domestic and international markets, new customer additions, capacity expansion and the planned launch of premium products.
Healthy revenue growth in Q2FY27, led by volumes
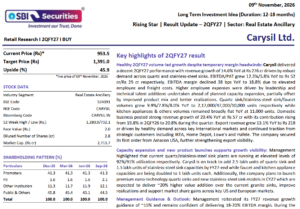
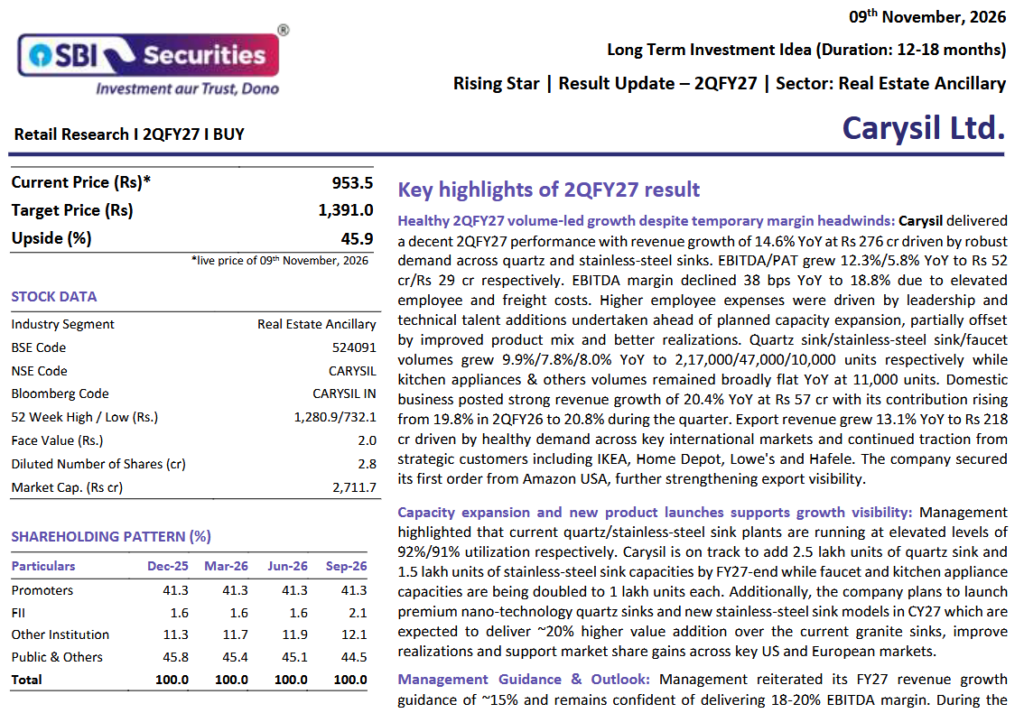
Carysil reported revenue of ₹276 crore for the second quarter of FY27, registering year-on-year growth of 14.6%. The performance was supported by robust demand across its quartz and stainless-steel sink businesses.
EBITDA increased by 12.3% year-on-year to ₹52 crore, while profit after tax (PAT) rose 5.8% to ₹29 crore. EBITDA margin, however, moderated by 38 basis points to 18.8%, primarily due to higher employee and freight costs.
According to SBI Securities, the increase in employee expenses was partly attributable to the addition of leadership and technical personnel in preparation for the company’s planned capacity expansion. Improved product mix and better realisations provided some cushion against these cost pressures.
The company’s volume performance remained encouraging. Quartz sink volumes increased 9.9% year-on-year to 2.17 lakh units, while stainless-steel sink volumes grew 7.8% to 47,000 units. Faucet volumes also increased 8% to 10,000 units. Volumes in kitchen appliances and other products remained broadly flat at 11,000 units.
Domestic business grows 20.4%; exports remain the principal growth driver
Carysil’s domestic business recorded strong revenue growth of 20.4% year-on-year to ₹57 crore. Its contribution to total revenue increased from 19.8% in Q2FY26 to 20.8% in Q2FY27, reflecting improving traction in the Indian market.
Export revenue grew 13.1% to ₹218 crore, supported by healthy demand across key international markets. The company continues to benefit from business relationships with established global customers, including IKEA, Home Depot, Lowe’s and Hafele.
An important development during the quarter was Carysil securing its first order from Amazon USA. The addition of Amazon as a customer is expected to strengthen the company’s international business prospects and broaden its customer base.
Exports continue to account for a substantial proportion of Carysil’s business, making international demand and customer additions important factors in its future growth trajectory.
Capacity expansion to support the next phase of growth
A key positive highlighted by SBI Securities is the company’s ongoing capacity expansion programme.
Carysil’s existing quartz sink and stainless-steel sink manufacturing facilities are operating at elevated utilisation levels of approximately 92% and 91%, respectively. This indicates strong utilisation of existing manufacturing infrastructure and the need to augment capacity to accommodate anticipated demand.
The company is on track to add:
-
2.5 lakh units of additional quartz sink capacity by the end of FY27.
-
1.5 lakh units of additional stainless-steel sink capacity by the end of FY27.
-
Faucet manufacturing capacity will be doubled to 1 lakh units.
-
Kitchen appliance capacity will also be doubled to 1 lakh units.
The expansion is expected to provide the company with greater operating flexibility and enable it to service incremental demand from both domestic and international customers.
Premium nano-technology sinks to improve realisations
Apart from expanding manufacturing capacity, Carysil is preparing to strengthen its product portfolio through new product launches.
The company plans to introduce premium nano-technology quartz sinks and new stainless-steel sink models in calendar year 2027. According to the brokerage report, these premium products are expected to offer approximately 20% higher value addition compared with the company’s existing granite sink offerings.
The proposed launches could help Carysil improve product realisations, move towards higher-value products and strengthen its competitive position in key markets, particularly the United States and Europe.
The focus on premiumisation is also expected to support margins over the medium term, provided the company successfully executes its product launch and market penetration strategy.
Management retains FY27 revenue growth guidance of 15%
Carysil’s management has reiterated its FY27 revenue growth guidance of approximately 15% and remains confident of achieving EBITDA margins in the range of 18–20%.
During Q2FY27, profitability was affected by elevated raw material prices and higher freight costs, which together had an estimated adverse impact of approximately 150–200 basis points on margins.
To mitigate these pressures, the company implemented a 5% price increase across product categories in September 2026. Management expects profitability to improve as freight rates and input costs normalise and the benefit of the price increases flows through.
The company remains optimistic about its growth prospects, supported by healthy domestic demand, new customer additions, capacity expansion and improved export visibility following the US mid-term election.
SBI Securities raises earnings estimates and maintains ₹1,391 target
Following the Q2FY27 performance, SBI Securities has marginally upgraded its earnings estimates for Carysil.
The brokerage has increased its FY27 and FY28 earnings per share (EPS) estimates by 3.9% and 3.6%, respectively, to ₹40.2 and ₹49.8.
The revisions factor in the anticipated benefits from recent price increases, additional export order wins, expansion of the retail gallery network and upcoming launches of premium nano-technology sinks.
SBI Securities has retained its valuation methodology of assigning 30 times the rolling one-year forward earnings per share. Based on this valuation, the brokerage has maintained its target price at ₹1,391.
At the target price, the stock offers an estimated upside potential of 45.9% over the next 12–18 months, according to the brokerage.
Prominent investors Ashish Kacholia and Sunil Singhania hold stakes
Carysil also attracts attention because of the presence of two well-known investors in its shareholding.
Ashish Kacholia holds a 2.72% stake in the company, while Sunil Singhania’s Abakkus Emerging Opportunities Fund holds 5.34%.
Their presence adds to investor interest in the company, although institutional and individual shareholding should be considered alongside the company’s financial performance, valuation and business prospects rather than as an independent investment rationale.
Outlook: Growth, premiumisation and capacity expansion remain key triggers
Carysil’s Q2FY27 performance reflects sustained demand across its principal product categories, with both domestic and export businesses recording healthy growth. The addition of Amazon USA as a customer, continued relationships with major international retailers and the proposed expansion of manufacturing capacity provide visibility for the next phase of growth.
The key factors to monitor will be the successful commissioning and utilisation of additional capacity, the ability to pass on higher input and freight costs, recovery in EBITDA margins and the commercial success of its premium product launches.
SBI Securities’ decision to retain its Buy rating and ₹1,391 target price reflects its confidence in these growth drivers. With revised earnings estimates and an anticipated 45.9% upside over 12–18 months, the brokerage sees considerable potential in Carysil.
The target price and upside mentioned above represent SBI Securities’ research assessment and are not assured returns. Investors should independently evaluate the company’s financial performance, valuation, risks and their investment objectives before making any investment decision.