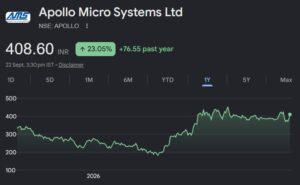
Transitioning into complete integrated weapon systems OEM…
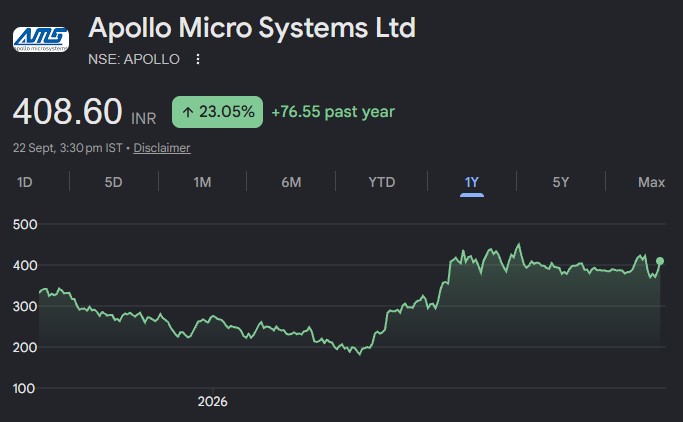
About the stock : Apollo Micro Systems Ltd (AMSL) is an electronic, electromechanical, and engineering design, manufacturing, and supplies company. It designs, develops, and sells high-performance, mission and time-critical along with COTS solutions to Aerospace, Defence, Space, MoD and the private sector • Consolidated order backlog stands at ₹ 1704 crore as of Jun-26
Investment Rationale:
• Strong capabilities in developing niche products: AMSL is an electronic, electromechanical, and engineering design, manufacturing, and supplies company. It designs, develops, and sells high-performance, mission-critical, and time-critical solutions to Aerospace, Defence, Space, and Homeland Security for the Ministry of Defence, government-controlled public sector undertakings, and the private sector. They offer custom-built COTS (Commercially off-the-shelf) solutions based on specific requirements to defence and space customers. We believe AMSL is well placed in terms of capturing upcoming opportunities in existing and new markets.
• Deep technology base and programme participation create entry barriers: With proprietary design capabilities, 700 technological innovations and involvement in 150+ indigenous defence initiatives, company has distinctive competitive advantages built over 4 decades in defence electronics. It holds production-phase qualification under the DcPP framework and approved vendor credentials with DRDO and DPSUs. The company already demonstrates exceptional capability in missile systems and underwater systems through a range of products. Going forward, we believe that company would be able to capitalise on its capabilities to expand its contribution in existing programs and upcoming projects including loitering munitions, UAVs, Directed Energy Weapons, Hypersonic vehicles etc
• Expanding order pipeline and vertical integration can drive the next leg of growth: Apollo’s order book has improved sharply from ₹735 crore in Q1FY26 to ₹1,704 crore by Q1FY27. Management expects ₹2,500-3,000 crore of additional orders during FY27, while major opportunities are emerging across missile programmes. Meanwhile, the acquisition of IDL Explosives and acquisition of a 41.33% stake in Premier Explosives (followed by open offer of 26%) are expanding capabilities beyond electronics into explosives, warheads, propellants and rocket motors. With several programmes expected to move into production we expect Apollo to grow from a subsystem supplier towards a broader weapon-systems platform
Rating and Target Price:
• Company’s earnings growth is expected to remain robust in the coming period, led by strong execution, consistent order inflows and rising contribution in key defence systems. We have not factored in the consolidation of Premier explosives in our estimates for FY27E/FY28E as we wait for completion of mandatory open offer of additional 26% stake in PEL
• We recommend BUY on AMSL with a TP of ₹ 485 (based on 60x P/E to consolidated FY28E EPS & ₹ 67/share to Premier Explosives)