Strong Revenue Momentum, with Margins Set for H2 Recovery…
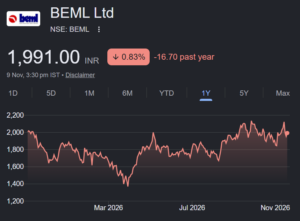
About the stock : A BEML is a diversified engineering PSU operating across Rail & Metro, Defence & Aerospace and Mining & Construction. The company has evolved from a conventional mining and rail equipment manufacturer into an indigenous mobility and defence platform, with products spanning Vande Bharat Sleeper, metro coaches, High Mobility Vehicles, Armoured Recovery Vehicles, mining equipment and strategic defence systems.
Q2FY27 performance : BEML reported revenue of ₹1,192 crore in Q2FY27, up 42.0% YoY, supported by improved execution. However, gross margin declined 770 bps YoY to 44.1% (vs. 51.8%), as higher cost of revenues weighed on profitability. EBITDA increased to ₹79 crore from ₹73 crore (+8.5% YoY), but EBITDA margin contracted to 6.6% from 8.7%. PAT declined 30.6% YoY to ₹33.3 crore. company also reported order inflows of ₹6,229 crore during the quarter, taking the closing order book to ₹21,388 crore as of September 30, 2026. Of this, ₹3,421 crore is executable in FY27 and ₹17,967 crore in subsequent years.
Investment Rationale:
• Rail & Metro to drive growth, supported by strong order pipeline : – BEML is transitioning towards a Rail & Metro-led growth profile, with the segment contributing around 75% of H1FY27 order inflows and over 40% of revenue. The opportunity is supported by a strong pipeline across metro rolling stock, commuter rail and other railway programmes. The company is currently participating in metro rolling-stock tenders worth ~₹6,000 crore, with another ₹3,000–4,000 crore of commuter-rail opportunities expected. BEML reported H1FY27 order inflows of ~₹7,500 crore and an order book of ₹21,388 crore as of September 2026, providing multi-year revenue visibility, with ₹17,967 crore executable beyond FY27. Management is targeting FY27 order inflows of ₹20,000 crore, with Rail & Metro expected to contribute around 50%. Gradual stabilisation of the domestic supply chain and improving execution are expected to support the next leg of growth.
• Exports and mining recovery to support profitability, while defence provides additional growth optionality : BEML is witnessing improving traction in exports, with an export order book of around US$120 million and an additional US$25 million of orders where it is L1. Management is targeting an export order book of US$200 million by FY27-end, with exports expected to contribute 6–7% of FY27 revenue. Export execution is particularly important given its higher profitability contribution. In parallel, mining execution is expected to recover in H2FY27 after a subdued first half, while defence execution is also expected to improve. Management is targeting around 30% of FY27 order inflows from defence, supported by a healthy opportunity pipeline.
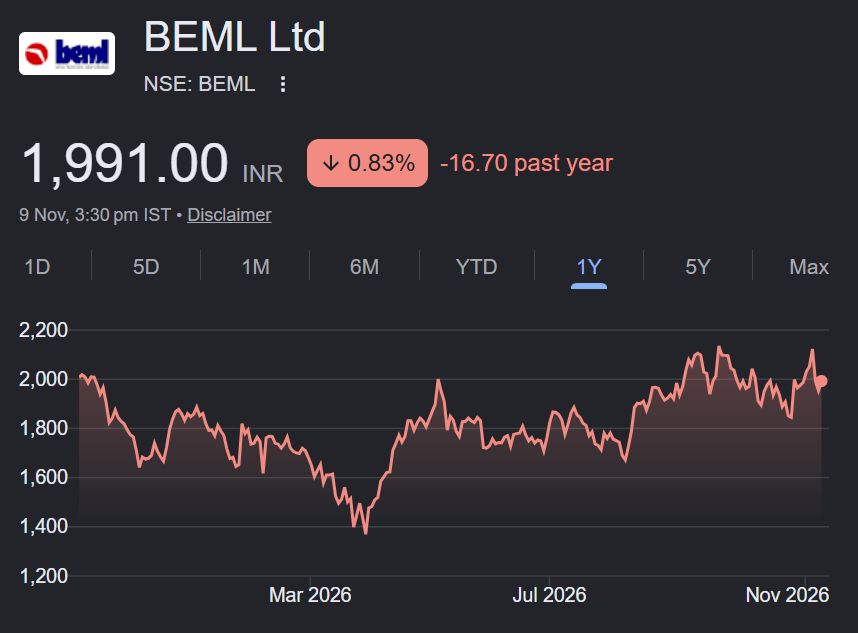
Rating and Target Price : We expect Revenue and PAT to grow at ~26% and ~102% CAGR over FY26-FY28E.We recommend BUY on BEML with a target price of ₹2765 per share (based on 40 x FY28E EPS)