Strong order pipeline; execution momentum sustains growth
About the stock : Bharat Electronics (BEL) is a leading aerospace and defence electronics company. It primarily manufactures advanced electronics products
• Multi-product, multi-technology – diverse product range including radar, missile systems, electronic warfare & avionics, electro-optics, homeland security, civilian products, etc
Investment Rationale:
• Healthy order book and strong pipeline provide sustained execution visibility: BEL ended Q2FY27 with an order backlog of ₹68,717 crore (~2.5x FY26 revenue), providing healthy medium-term revenue visibility. The order book remains diversified across electronic fuses, LRSAM, LCA Mk1, BMP-2 Upgrade, Ashwini Radar and EW systems. Management expects orders worth ~₹20,000 crore from the NGC programme, while the ₹30,000 crore QRSAM order remains a key near-term trigger. Alongside these, expected orders from Shatrughat, Samaghat and HAMMER support the company’s FY27 order inflow target of ₹25,000 crore excluding QRSAM ~₹30,000 crore
• Technology leadership and indigenous capabilities support sustainable growth: BEL’s strong R&D base, with planned investments of ₹2,200+ crore in FY27, continues to strengthen its position across complex defence electronics. The company has developed capabilities across radars, electronic warfare, communication systems, missile electronics and seekers, with management indicating that electronics account for 60-70% of missile costs. Its combined seeker manufacturing capacity of 1,000+ units annually, with scope to scale up 2-3x, provides an opportunity to increase its participation in missile programmes. Continued investments in R&D and manufacturing infrastructure, alongside capex of ₹1,200+ crore, are expected to support higher indigenisation and new product development
• Emerging opportunities across drones, counter-drone systems and exports provide additional growth levers: BEL is strengthening its presence in high-growth areas such as surveillance and kamikaze drones, counter-drone systems, directed-energy weapons and cybersecurity. The company is working with 6-8 startups to develop reliable drone solutions and expects larger orders to emerge over the next 1-2 years. Its counter- drone solutions, including hard-kill capabilities and high-power microwave technology, have received encouraging responses in overseas demonstrations, creating export opportunities. Further, its AMCA partnership with L&T and growing participation in missile programmes provide additional avenues for growth beyond its existing order book
Rating and Target Price:
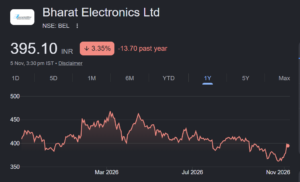
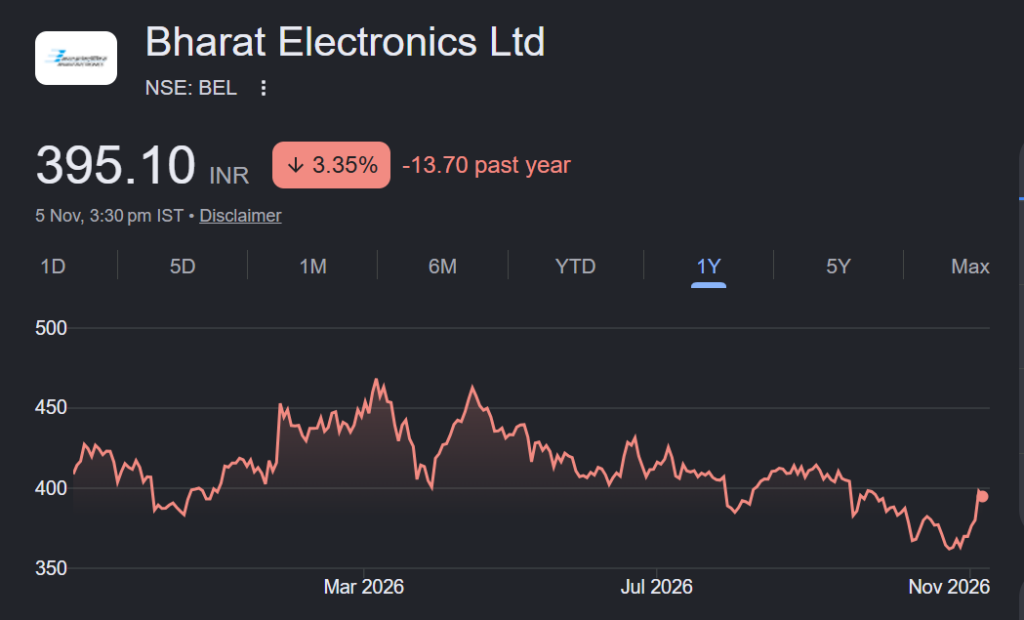
• With healthy order-backlog, robust pipeline and improving execution led by increasing indigenisation, we believe that BEL provides strong earnings visibility. We maintain BUY on BEL with a target price of ₹ 530 per share (based on 45x FY28E EPS)