Deep capabilities, Strong growth runway …
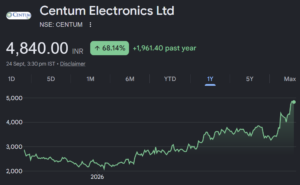
About the company – Centum Electronics (Centum) is a premier electronics system design and manufacturing (ESDM) company based in Bengaluru. Established in 1993, the company builds high-reliability electronic systems and microelectronics for critical fields like defence, space, aerospace, industrials, semiconductor, railways and healthcare. It partners with marquee entities like Indian Space Research Organisation (ISRO) and Defence Research and Development Organisation (DRDO) to deliver mission-critical parts for satellites, missiles, and radars.
Investment Rationale
• Decades of trust in regulated , high – barrier segments: Centum’s ~50% of revenue in FY26 is derived from Aerospace, defence and space which are highly critical and regulated segments. The company has decades of experience and relations with DRDO, ISRO and other large PSU defence players wherein Centum has contributed to mission critical products and participated in various missions such as Mangalyaan, Gaganyaan, Chandrayaan -3, etc. Around 70% of its products are single-sourced, while ~30% of revenue comes from customers with relationships exceeding 20 years and another ~40% from customers with 10-20 years relationships.
• Strong order book and structural sector tailwinds esp. in Defence and Semiconductors: Backed by structural government support and the “Make in India” program, Centum’s standalone order book stood at ~₹1800 crore as on Q1FY27 which grew 32% YoY. About ₹872 crore of order book is constituted by EMS (Build-to-print) while high margin BTS (Build-to- specification) orderbook stood at ~₹925 crore, growing at faster pace of ~42% YoY. Centum has developed various products under BTS which are expected to go into commercialisation beyond FY28. Segment wise, defence and aerospace (~50% of revenue) are in structural growth runway aided by government’s indigenisation measures. Transportation and Automotive: 11% of revenue, Healthcare: 7%, Industry & Energy including semiconductor related: 32% support diverse growth runway. Centum provides PCBA & Box builds to semiconductor equipment segment (~17% of revenue in Q1) which has increased from near-zero in FY25 to ~₹100 crore+ in FY26 and shall further scale to ~₹250 crore within 2 years.
• Profitability expected to witness uptick: Centum’s current revenue mix is EMS dominated with ~72% of its revenue (9-10% EBITDA margin) while high margin BTS (~20%+) contributes balance ~28% which we expect to increase to ~33% by FY28E considering the order book with potential to further scale from thereon. Also, utilization levels are currently low at ~50- 60% which shall bring operating leverage factor to play as revenue scales. Separately, Centum has exited the loss-making subsidiaries business which were exerting pressure on consol EBITDA margins.
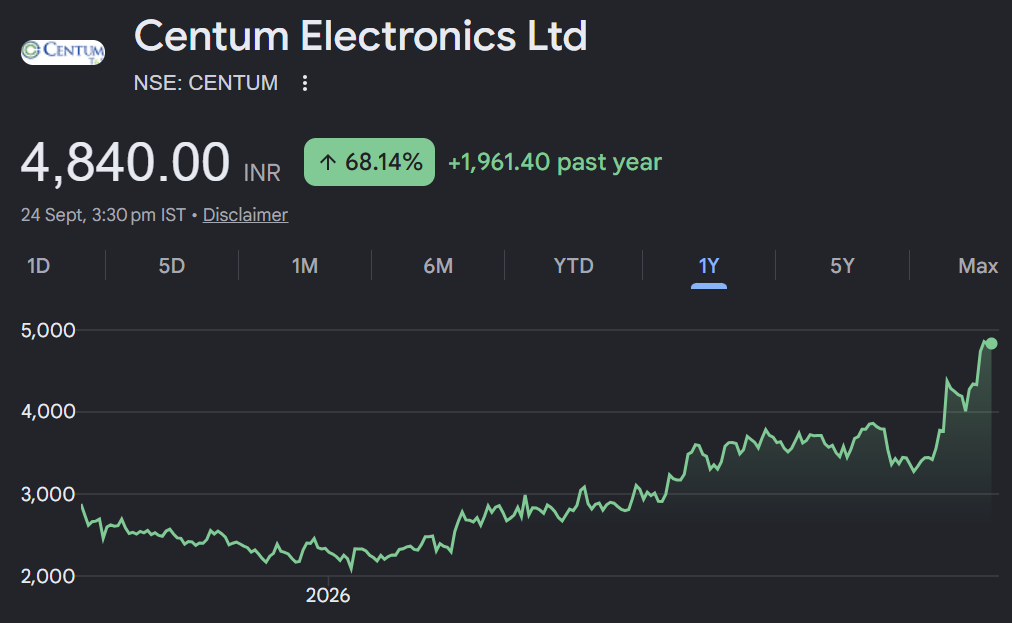
Rating and Target Price: Management has guided for 25-30% CAGR over medium term accompanied by healthy EBITDA margin of 13-15%. The overhang of European subsidiaries losses is now behind with Centum exiting them while management’s focus on core segments shall aid profitability improvement. Valuation to stay rich considering the long-term growth prospects owing to presence in defence, semi-conductor and such other segments. We recommend BUY rating on the stock with target price of 5,900, valuing at PE of 65x FY28E EPS.