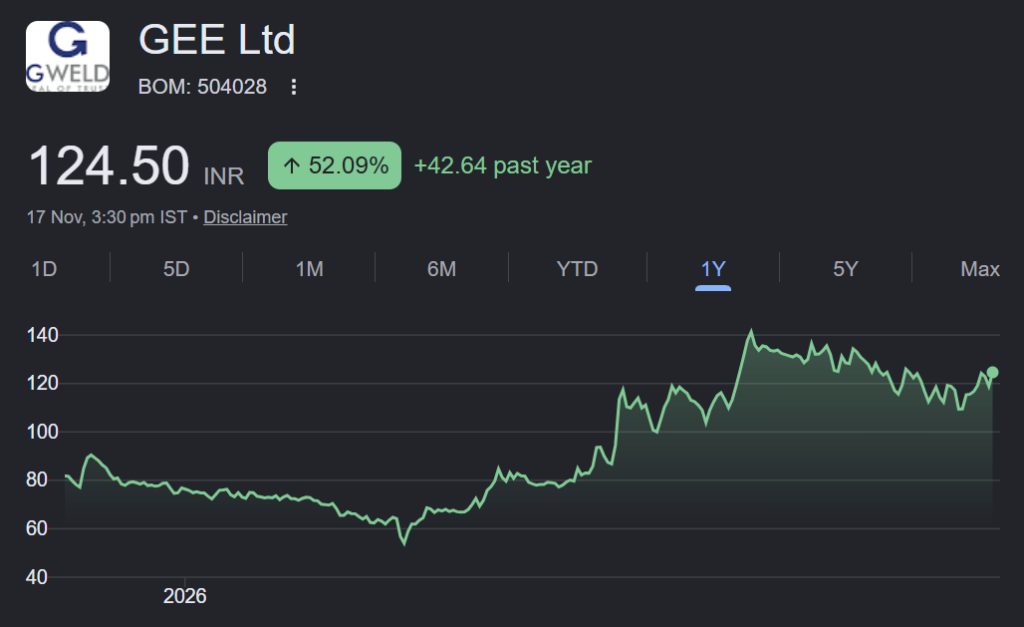
Capacity expansion & product premiumisation to drive earning growth …
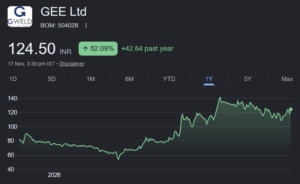
About the stock : GEE Limited is a leading manufacturer of welding consumables, with a diversified product portfolio spanning electrodes, MIG/TIG wires, submerged arc welding (SAW) wires and fluxes, and specialised welding consumables.
• GEE operates manufacturing facilities in Maharashtra and West Bengal, with an installed capacity of 59,075 MTPA, and is expanding its product portfolio into SAW and flux-cored wires to capture emerging opportunities in specialised welding applications.
Q2F Y27 performance: GEE Limited reported consolidated revenue growth of 18.6% YoY to ₹101.3 crore in Q2FY27 compared to ₹85.5 crore in Q2FY26. Gross margin contracted marginally by 39 bps YoY to 26.3% from 26.7%. However, operating EBITDA declined 11.9% YoY to ₹7.9 crore from ₹9.0 crore, with operating EBITDA margin contracting sharply by 271 bps to 7.8% from 10.5%. The disproportionate increase in employee expenses (+30.7% YoY) and other expenses (+37.9% YoY), both outpacing revenue growth, weighed on operating profitability. Consequently, PAT declined 6.4% YoY to ₹3.9 crore from ₹4.2 crore.
Investment Rationale:
• Capacity expansion and operating leverage to drive earnings growth : GEE is well positioned to benefit from improving capacity utilisation and expansion of its manufacturing footprint. The company plans to increase its installed capacity from around 59,000 MT to 71,000 MT, with utilisation targeted at over 90% by FY29–30. The planned capex of ₹35–40 crore over the next two years will primarily be directed towards expanding MIG wire capacity from 12,000 MT to 24,000 MT and scaling flux-cored wire capacity of around 250 MT per month to be operationalise by Q3FY27 and plans to scale it to 1,000 MT per month by FY28. Further, the existing capacity has the potential to support incremental revenue of around ₹300 crore over the FY26 revenue base of approximately ₹370 crore, with limited additional investment towards process streamlining. Higher utilisation is expected to drive economies of scale and reduce per-tonne operating costs, supporting margin expansion.
• Premium product mix and expanding end – market opportunities to support sustainable growth : GEE is focusing on increasing the share of specialized and value-added welding consumables, which currently account for around 27% of its product basket, to 35–40% over the coming year. Specialized products such as silver brazing alloy wires, nickel wires and specialized GTIG series command significantly higher realizations of ₹275– 1,500/kg compared with ₹100–125/kg for conventional consumables, providing scope for improved product realization and profitability. Management targets 25–30% annual revenue growth and revenue of ₹1,000 crore by FY30, while targeting EBITDA margins of 12–13% over the next 3–4 years, driven by product-mix improvement, pricing premium and operating leverage.
Rating and Target Price: We expect Revenue and PAT to grow at 29% and 66% CAGR over FY26 – FY28E . We maintain BUY on GEE with a Target Price of ₹170 (based on 25x on FY28E EPS)