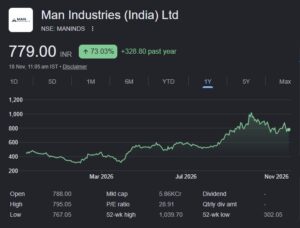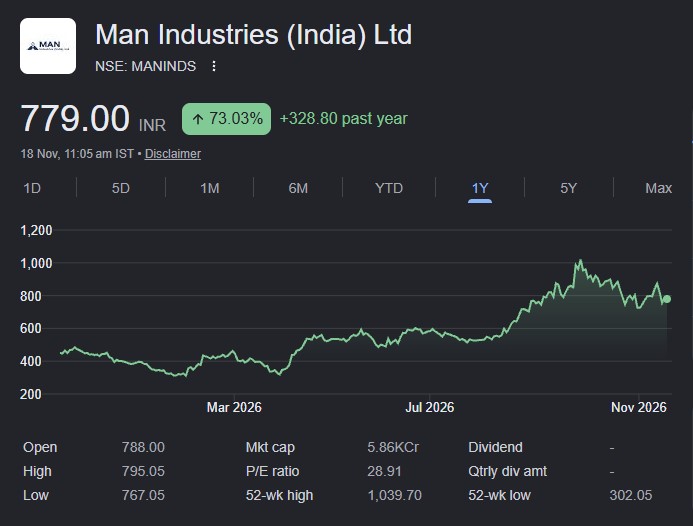
MAN Industries (India) Ltd. is emerging as an interesting play on the global pipeline infrastructure opportunity. The company has made a significant transformation from a domestic pipe manufacturer into an integrated, cross-border pipeline solutions platform, following its acquisition of National Pipe Company (NPC) in Saudi Arabia.
The improving business outlook has also attracted several well-known investors. Ashish Kacholia holds 3.04% of the company, while Suresh Kumar Agarwal owns 2.77%. Vikas Khemani holds 2.39%, and Carnelian Fund has a 1.02% stake.
The presence of these investors, coupled with an increasingly favourable business outlook, has brought MAN Industries into the investment spotlight.
Landmark Saudi Acquisition Transforms MAN’s Growth Prospects
FY26 was a landmark year for MAN Industries. The company reported its highest-ever standalone EBITDA margin of 14% on revenues of ₹3,508 crore while completing its first major international acquisition.
MAN acquired National Pipe Company in Saudi Arabia for approximately ₹1,000 crore at an attractive valuation of just 1.5x EV/EBITDA.
The acquisition is strategically important as it significantly enhances MAN’s manufacturing scale, geographical reach and addressable market. It also provides access to the Middle East, a region witnessing substantial investments in oil and gas pipelines and associated infrastructure.
The acquisition is expected to strengthen MAN’s competitive positioning and create opportunities to participate in larger international projects.
Management has guided for FY27 consolidated revenues of ₹5,000–5,500 crore, implying an impressive 40–50% growth over FY26, while maintaining EBITDA margins in the 13–15% range.
Strong Order Book and Pipeline Provide Multi-year Growth Visibility
One of the strongest arguments in favour of MAN Industries is its healthy order pipeline.
The company had a consolidated order book of approximately ₹3,000 crore at the end of Q4FY26. More importantly, its bid pipeline stands at a substantial ₹16,000 crore.
This provides significant opportunities for future order inflows and offers multi-year revenue visibility.
Choice Securities expects MAN to deliver an impressive financial performance over FY26–FY29:
| Financial metric | Expected CAGR |
|---|---|
| Revenue | 31% |
| EBITDA | 41% |
| PAT | 66% |
The significantly higher projected growth in EBITDA and PAT compared with revenue indicates the potential for substantial operating leverage and margin expansion.
Three Major Catalysts Could Drive Profitability
Choice Securities has identified three important growth catalysts.
1. Strong earnings trajectory
The combination of the Saudi acquisition, a healthy order book, a large bid pipeline and capacity expansion is expected to drive strong earnings growth.
The brokerage projects revenue, EBITDA and PAT CAGRs of 31%, 41% and 66%, respectively, between FY26 and FY29.
2. ₹800–900 crore potential from land monetisation
MAN Industries owns a non-core land parcel in Navi Mumbai, which could be monetised over the next three to five years.
Choice Securities estimates that the transaction could generate cash inflows of ₹800–900 crore.
This is a substantial amount, equivalent to approximately 20% of the company’s current market capitalisation, and could strengthen the balance sheet, improve liquidity and provide additional funding for future growth investments.
3. Significant EBITDA margin expansion
Choice Securities expects EBITDA margins to improve by approximately 301 basis points between FY26 and FY29.
The expected improvement will be driven by:
- Higher contribution from value-added products.
- Better capacity utilisation at existing and newly commissioned plants.
- Economies of scale arising from increased production.
- Operating leverage as revenues expand.
The combination of these factors could result in EBITDA and PAT growing substantially faster than revenues.
Q4FY26: Margin Improvement Despite Revenue Shortfall
MAN Industries reported mixed Q4FY26 financial performance. While revenue and profitability were below Choice Securities’ estimates, EBITDA margins showed year-on-year improvement.
| Particulars | Q4FY26 | YoY growth |
|---|---|---|
| Consolidated Revenue | ₹1,157.3 Cr | -5.0% |
| Consolidated EBITDA | ₹139.7 Cr | +4.5% |
| EBITDA Margin | 12.1% | +110 bps |
| Consolidated RPAT | ₹50.8 Cr | -25.4% |
Revenue declined 5% YoY to ₹1,157.3 crore, although it increased 39.4% sequentially.
EBITDA increased 4.5% YoY to ₹139.7 crore, with margins improving by 110 basis points to 12.1%. However, PAT declined 25.4% YoY to ₹50.8 crore.
The results were below the brokerage’s estimates, particularly on revenue and profitability. Nevertheless, the year-on-year improvement in EBITDA margins is encouraging.
The consolidated order book stood at approximately ₹3,000 crore, compared with around ₹4,000 crore in Q3FY26. The reduction in the order book makes conversion of the substantial bid pipeline into fresh orders an important factor to monitor.
Choice Securities Raises Target Price to ₹690
Choice Securities has reiterated its BUY recommendation on MAN Industries and raised its target price substantially.
| Particulars | Details |
|---|---|
| Earlier Target Price | ₹535 |
| Revised Target Price | ₹690 |
| Valuation methodology | EV/EBITDA |
| Multiple assigned | 6x FY28E EV/EBITDA |
| Recommendation | BUY |
The brokerage has assigned an EV/EBITDA multiple of 6x on FY28 estimated EBITDA.
Choice Securities considers this valuation multiple conservative, particularly in view of the company’s improving return on capital employed (ROCE) trajectory and growth prospects.
The revised target price reflects the improved business outlook, strong earnings visibility, expected margin expansion and capacity-led growth.
Risks Investors Should Monitor
Despite the encouraging outlook, there are risks that investors should not overlook.
- Order conversion risk: The company’s ability to convert its ₹16,000 crore bid pipeline into confirmed orders will be crucial.
- Capacity ramp-up: Delays or slower-than-expected utilisation of upcoming capacities could affect projected growth.
- Acquisition integration: The successful integration of National Pipe Company and the realisation of expected synergies will be important.
- Execution risk: Delivering the management’s ambitious FY27 revenue guidance while maintaining margins of 13–15% will require strong operational execution.
Conclusion: Is MAN Industries Entering a New Growth Phase?
MAN Industries appears to be at an important inflection point. The Saudi acquisition has significantly expanded its geographical footprint and addressable market, while the existing order book and substantial bid pipeline provide opportunities for sustained growth.
The potential monetisation of its Navi Mumbai land parcel could provide an additional financial cushion, while higher capacity utilisation, value-added products and operating leverage could drive meaningful margin expansion.
The presence of prominent investors such as Ashish Kacholia, Vikas Khemani and Carnelian Fund adds to the market interest surrounding the company.
Choice Securities’ projections of 31% revenue CAGR, 41% EBITDA CAGR and 66% PAT CAGR over FY26–FY29 are particularly noteworthy. Its revised target price of ₹690 reflects confidence in MAN’s evolving business profile.
However, investors should remember that these are brokerage estimates, not guaranteed outcomes. The ability to secure fresh orders, execute the Saudi acquisition successfully and ramp up capacities will determine whether the company can deliver on its ambitious growth targets.
The key investment question is no longer just whether MAN Industries can grow its domestic pipe business, but whether it can successfully transform itself into a global pipeline solutions company.
Editorial note: The article uses the financial figures and projections supplied from the Choice Securities report. The ₹690 target price is a brokerage estimate, not an assurance of returns. The actual upside depends on the prevailing market price.