Robust volume-led growth, partially offset by higher purchases of stock-in trade.
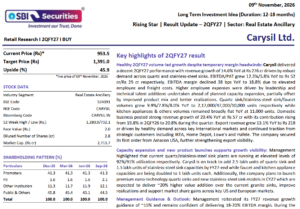
Hi-Tech Pipes Ltd. (HITECH) during the quarter reported Revenue/EBITDA/PAT growth of 70.7%/27.6%/34.5% YoY to Rs 1,466 cr/Rs 57 cr/Rs 27 cr, respectively driven by healthy sales volume growth of 31.8% YoY to 1,65,016 MT led by ramp- up of new capacities. However, EBITDA/t for the quarter stood at ~Rs 3,429, down 3.2% YoY, impacted by higher purchases of stock in trade (Rs 290 cr in 2QFY27 vs Rs 74 cr in 2QFY26).
Project updates: The DFT facility at Sanand Unit-2 is expected to be commissioned by 4QFY27, alongside the API pipes facility (which will mark HITECH’s foray into API-grade Oil & Gas pipe manufacturing). Additionally, the fully integrated ERW pipes & specialized solar pipes production facility at Hindupur, Andhra Pradesh, is also expected to be operationalized by 4QFY27. Overall, these facilities are expected to add 3,00,000 MT of annual capacity, taking the company’s total installed capacity to 13,50,000 MTPA by FY27-end. Going ahead, as these 3 facilities ramp-up in FY28, the share of value-added products in the company’s sales mix is expected to increase from the current 39% to ~55%. Further, management has reiterated its target to scale the total capacity to 20,00,000 MTPA by FY29.
Solar market opportunity: With India adding 40–50 GW of solar capacity annually (requiring 20–22 tonnes of steel per MW), the domestic market represents a ~1 million tonnes annual opportunity, as per management. The company is also experiencing rising demand for specialized structural pipe applications from data center infrastructure applications.
Guidance: For FY27, management has guided for sales volume guidance of more than 6,50,000 MT, followed by 8,50,000 to 9,00,000 MT in FY28. Further, for FY29, management expects EBITDA/t to inch up to Rs 4,000 to 4,500, with sales volume of 11,00,000 to 12,00,000 MT.
Maintain BUY- Target Rs 106/-
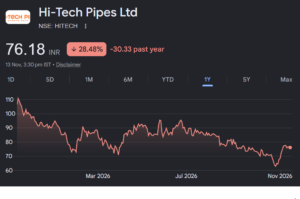
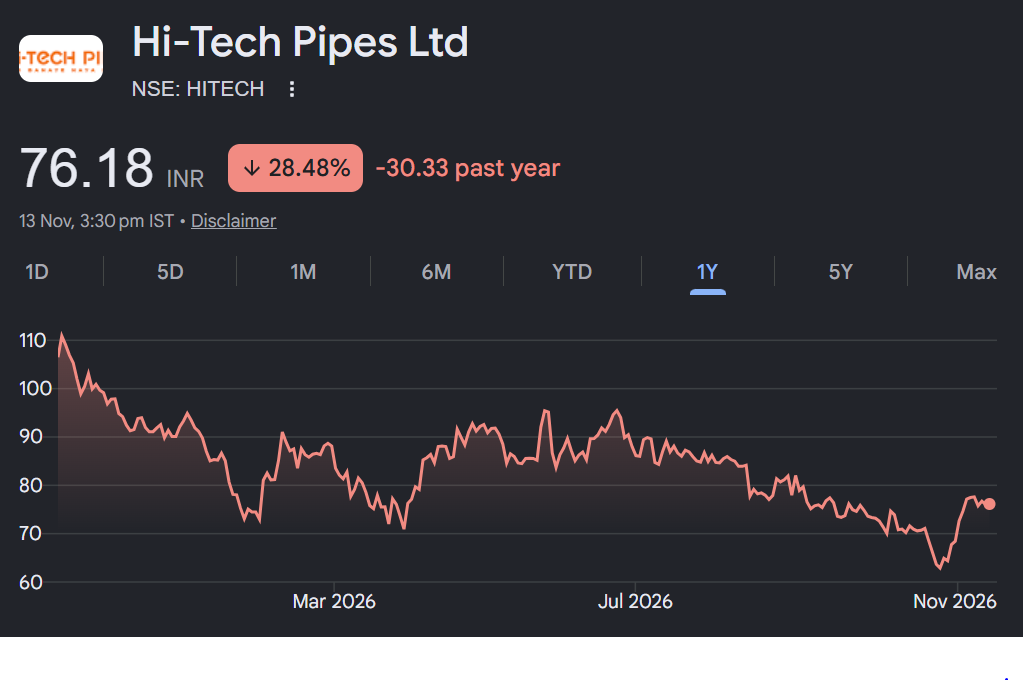
We estimate FY27E/FY28E sales volumes of 6,51,000/7,72,500 MT respectively implying a CAGR of 20.5% over the FY26A-FY28E period. Revenue/EBITDA/PAT is forecasted to grow at a CAGR of 24.6%/27.1%/27.9% respectively between FY26A-FY28E period; with EBITDA/t expected to reach Rs 3,345/Rs 3,631 in FY27E/FY28E. At the CMP of Rs 78, the stock is currently trading at a P/E multiple of 17.1x/13.3x based on its FY27E/FY28E EPS of Rs 4.6/Rs 5.9 respectively. We value the stock at a P/E multiple of 18.0x based on FY28E EPS to arrive at our target price of Rs 106, implying an upside of 35.9%.