Healthy Performance; robust growth outlook!
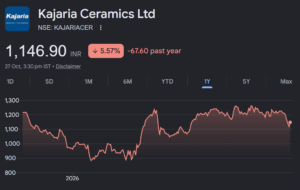
About the stock: Kajaria Ceramics is the largest manufacturer of ceramic/vitrified tiles in India with current annual capacity of 87.8 million. square. metres (MSM) spread across India and Nepal.
• The company enjoys industry leading margins and returns ratios.
Q2FY27 performance: Kajaria Ceramics delivered healthy volume growth, tile sales volumes rose 10% YoY to 31.8 MSM in Q2 FY27 and 8% YoY to 60.6 MSM in H1 FY27, reflecting improved demand and market-share gains. Tile realization increased ~11.4% YoY, given the price hikes. Consolidated revenue grew 23.7% YoY to ₹1,468.3 crore in Q2, supported by higher volumes and improved realizations. EBITDA rose 34.6% YoY to ₹286.5 crore, with margins expanding 157 bps to 19.5%, while PAT increased 42.5% YoY to ₹189.5 crore, driven by strong operating performance.
Investment Rationale:
• Maintains guidance of double – digit Tiles volume growth : Management expects to sustain double-digit volume growth of ~10% over H2FY27 with double-digit volume expansion continuing into the next year as well. Furthermore, given the lower price differential between organised and unorganised players (20-25% currently vs. 40%, earlier), they expect market share gains to sustain ahead. With this, we expect Tiles revenues CAGR of 11.3% over FY26-FY28E to ₹5,299 crore, as we conservatively bake in volume CAGR of 8.5% over the same period to ~135.9 MSM with overall topline growing at 12.1% CAGR over FY26-28E to ₹6,073 crore.
• Capex revised upwards: The company revised the planned GVT expansion capacity in Andhra Pradesh upward from 10 MSM to 12.5 MSM, with project cost estimate up from ₹210 crore to ₹340 crore. In Rajasthan, the GVT brownfield expansion has been revised from ₹165 crore to ₹180 crore for 11 MSM capacity due to higher civil costs and an enlarged warehouse, with completion expected by April 2027. The above capacity expansion provides a sufficient headroom for growth sustenance in FY28. Additionally, the board approved a new ₹34 crore tile adhesive facility with a capacity of 9,000 MT/month thereby increasing existing capacity by 50%.
• Margins to base at new levels: The company has maintained their EBITDA margin guidance at 18-19% for FY27 with EBITDA reaching the level of ~₹1000+ crore for the year. With the new GVT capacities coming up at Srikalahasti (12.5MSM) and Gailpur (11MSM), it will bring in improved mix thereby supporting existing margins. We conservatively bake in margins for FY27 and FY28 at 18.6% and 18% respectively, as we believe that volume growth would result in some rise in operating expenses including sales & marketing
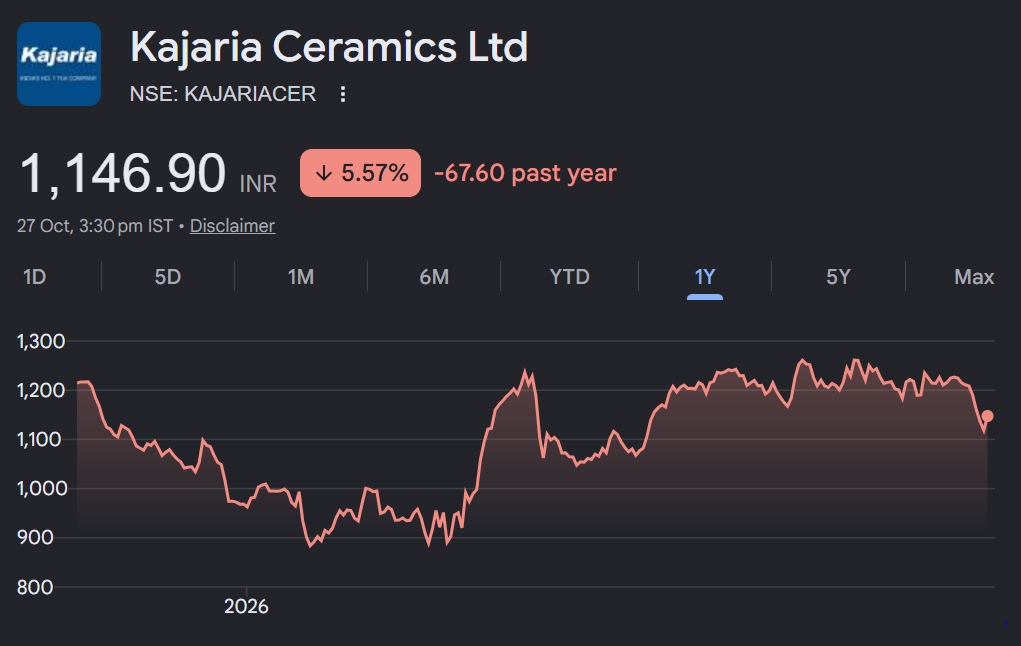
Rating and Target Price: We maintain a BUY rating for Kajaria Ceramics with a revised price target of ₹1540, valuing it at 34x its FY28E EPS.