Sustained EEI growth; Alucast recovery key to earning upside…
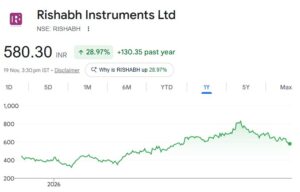
About the stock : Rishabh Instruments Limited is a leading global engineering and energy efficiency solutions provider specializing in the design, development and manufacturing of products that support electrical automation, energy measurement, industrial instrumentation, and precision die-casting.
• Revenue Mix for FY26: Electrical and Electronic instruments (EEI) ~70% and High Pressure Die Castings ~30%.
Q2FY27 performance : Rishabh Instruments reported Q2FY27 revenue of ₹212.8 crore, up 8.4% YoY and 7.3% QoQ. EBITDA declined 2.8% YoY to ₹32.4 crore, with EBITDA margin contracting 175 bps YoY to 15.2%, while PAT declined 17.9% YoY to ₹18.2 crore. Gross margin declined 350 bps YoY to 58.5%, reflecting an adverse product mix.
Investment Rationale:
• EEI -led growth provides strong earnings visibility: Rishabh’s EEI business continued to drive growth, with Q2FY27 revenue increasing 24.9% YoY to ₹172 crore and H1FY27 revenue growing 29.3% to ₹326 crore. H1 adjusted EBITDA increased 29.9% YoY to ₹75 crore, with margins remaining stable at 23.1%. Growth is supported by demand across energy measurement, power infrastructure, renewable energy, industrial automation and electronic manufacturing. The company is also expanding its product portfolio in solar inverters, power quality and data-centrerelated applications, supported by the Nashik facility and enhanced manufacturing capabilities. Management has retained FY27 EEI revenue growth guidance of 20–25%, with adjusted EBITDA margin guidance of 20–22%, providing visibility for sustained growth.
• Global diversification and Alucast turnaround provide additional earnings levers : Rishabh is positioned across structural growth areas such as grid modernization, renewable energy, energy efficiency, industrial automation and AI-driven data centres. Lumel SA revenue grew 24.8% YoY to ₹134 crore in H1FY27, with adjusted EBITDA increasing 44.1% to ₹29 crore, while the US business doubled its H1 revenue to ₹26 crore. In parallel, Lumel Alucast revenue declined 36.6% YoY to ₹86 crore in H1FY27 following the planned exit from low-margin contracts, with adjusted EBITDA loss narrowing to ₹3 crore. Management expects the business to achieve adjusted EBITDA breakeven in FY27, supported by higher-value orders, improved utilization and better cost control. This combination of international growth opportunities and the Alucast turnaround provides scope for revenue growth and margin-led earnings improvement, although execution and recovery in Alucast remain key monitorables.
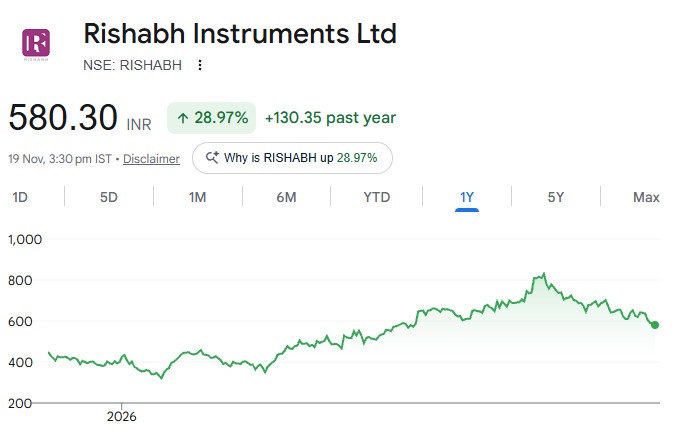
Rating and Target Price: We expect Revenue and PAT to grow at 14% and 24% CAGR over FY26-FY28E. We recommend BUY on Rishabh Instruments with a target price of ₹825 per share (based on 25 x FY28E EPS).