Soft H1; launches to drive H2 sales…
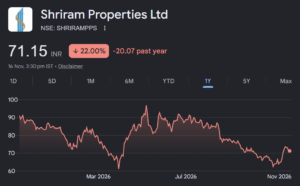
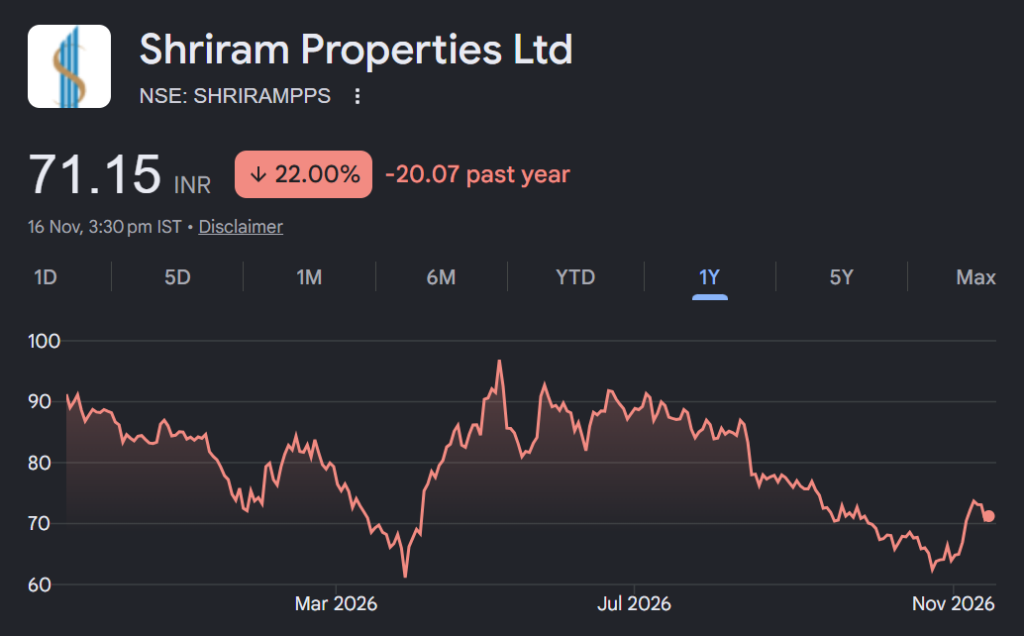
About the stock : Shriram Properties (SPL) is among the top 5 residential real estate developer in south India primarily focused on the mid-market & mid-premium housing categories.
• It has established a strong presence in Bengaluru, Chennai, Kolkata and recently expanded to Pune. It has a project pipeline of more than 33 msf (15.5/17.7 msf – ongoing/upcoming) with a mix of Owned, Joint Development Agreement, Joint Venture & Development Management projects.
Q2F Y27 performance : SPL reported a muted Q2FY27, pre-sales down 15% YoY to ₹ 583 crore (0.91 msf), in absence of project launches during Q2FY27. Collections increased 11% YoY to ₹ 431 crore. Revenue fell 11% YoY to ₹ 184 crore, significant other income led to 2.35x EBITDA growth at ₹ 62.4 crore (₹ -26.3 crore after adj. for other operating income) and PAT at ₹ 21.6 crore vs ₹ 8.6 crore in Q2FY26. Operating cash flow came in at ₹ 47 crore. The company took over partner share in three JVs which together brought in debt of ₹ 300 crore. The net debt position increased to ₹ 761 crore from ₹ 432 crore in June 2026 and net debt/equity climbed to 0.51x.
Investment Rationale:
• FY27 guidance retained anticipating strong H2 : SPL retained ₹ 3300-3500 pre-sales growth (40-49% YoY) guidance for FY27 led by strong launch pipeline of ~₹ 6000 crore launch pipeline (~10% launched in H1), which is expected to generate ~₹ 2000 crore pre-sales. Further, sustenance sales is expected to contribute ~₹ 1400-1500 crore for FY27. Its H2FY27 launch pipeline of ~5.2+msf is well diversified across Bengaluru (50%), Pune (32%) and Chennai (17%), providing uptick in realisations (higher Bengaluru share). It has unsold inventory of 2.2 msf (GDV of ₹ 1400 crore) in ongoing projects and 17.7 msf (GDV of ₹ 12110 crore) in upcoming projects, scheduled to be launched over the next 4-5 years. Hence, overall, its unsold GDV potential stands at ₹ 13,510 crore, providing a strong pre-sales growth trajectory going ahead. We estimate its pre-sales to grow at 31% CAGR over FY26-FY28E to ₹ 4030 crore.
• Business development of ₹ 5000 – 6000 crore for FY27 retained : SPL has secured business development of ~41 msf (GDV of ~₹ 20,775 crore) since FY19 (H1FY27 – ₹ 650 crore). For FY27, it retained new project additions of 7-8 msf with GDV potential of ₹ 5000-6000 crore. Currently, it has 8.8 msf projects worth ₹ 7500 crore likely addition in ~6 months and 21+ msf projects at various stages of evaluation. The company retained its FY28 mission target of pre- sales (₹ 5000+ crore), revenues (₹ 2500+ crore) and PBT (₹ 250+ crore). Overall, it has ~₹ 14,000 crore of revenues (~₹ 4800+ crore – launched/ongoing, ~₹ 9000+ crore – Upcoming projects) to be recognised in 5- 7 years.
Rating and Target Price :
• Shriram properties is expected to remain on a strong pre-sales growth trajectory over the next 2-3 years. We maintain our Buy rating on the stock with revised price target of ₹ 110 (factoring in increase in interest rates)