Fermentation at the fore- Moving into high-value extensions…
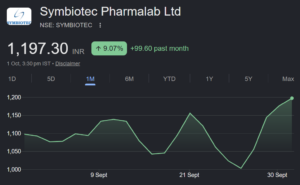
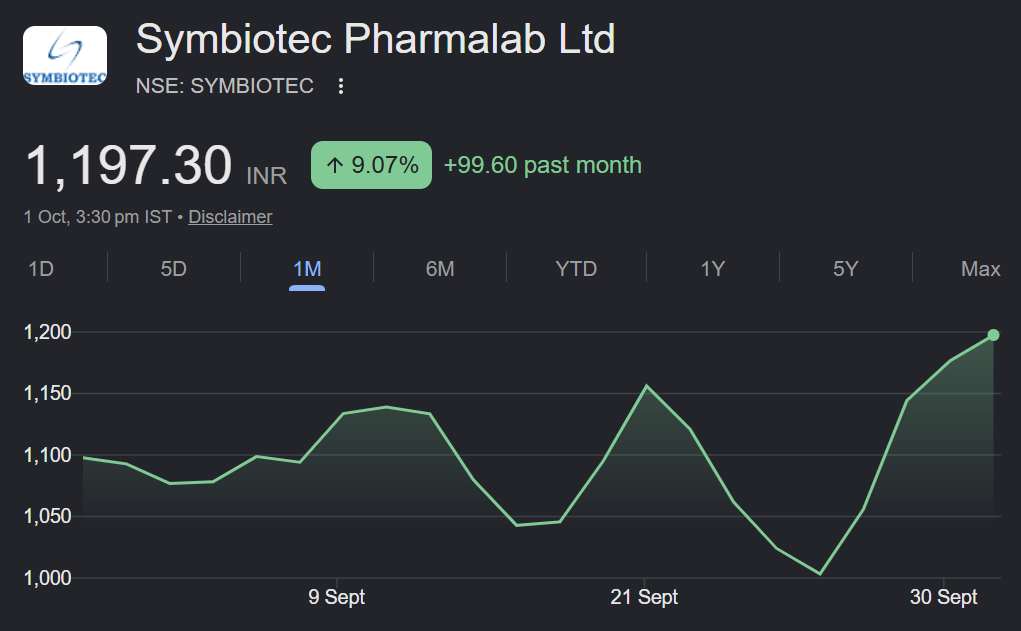
About the company – Madhya Pradesh (MP) based Symbiotec Pharmalab Limited (SPL) is an API company with focus on corticosteroid (man-made drugs that copy natural cortisol) and steroidal-hormone APIs with a global leadership. It manufactures these products using fermentation and multi-step complex chemical reactions.
• The company has two API manufacturing facilities the Rau Facility, and the Pithampur Facility. Further, the company has commissioned two additional manufacturing facilities in Ujjain and Mhow.
• Capacity: Chemical Synthesis – ~585 MT, Fermentation – 700 KL, Double Chamber Vials – 20 million units per annum.
Investment Rationale
• Long standing leadership in global corticosteroid and steroidal hormone APIs : Symbiotec enjoys a strong global leadership position in corticosteroid and steroidal hormone APIs, with a global volume market share of 38.2% and 23.8%, respectively. Its portfolio comprises of ~60 products across sterile and non-sterile formats, catering to a diversified customer base of 200+ clients across 40+ countries, including 150+ export customers. Strong customer stickiness is reflected in an average relationship tenure of nearly 10 years with its top 10 customers. The corticosteroid and steroidal hormone APIs segment is expected to grow at ~8–10% CAGR during FY26- FY29E to be driven by a stable base business growth and traction from new products such as Vegan D3, Docosahexaenoic Acid (dietary supplement), UDCA (Gastrointestinal medication) and Premarin (conjugated estrogens). The segment remains a stable cash generator for new ventures in future.
• Significant investments to extend the current platform towards complex injectables and CDMO : SPL has been on a capex drive over the past 3–4 years and has invested ~₹1,000+ crore in the new businesses, including ₹376 crore towards Complex Injectables and ₹584 crore towards CDMO. In CDMO, the company has multiple contracts with Take-or-Pay arrangements, providing greater revenue visibility, and in Complex Injectables, which represents a natural forward integration of its existing API capabilities, the company is developing double-chamber vial products and has already partnered for the commercialisation of its first two products, with milestones expected in FY27E and commercial revenues from FY28E. We believe these businesses can be value-accretive over the long term and support a structural improvement in the company’s margin profile from ~27% currently to ~32% by FY29E, alongside an estimated revenue CAGR of ~23% over FY26–29E.
Rating and Target Price: we initiate Buy on SPL with a price target of ₹ 1570 (valuing at 19x FY29E EBITDA of ₹542.4 crore). We believe the company has the required wherewithal to transition from a legacy API to complex APIs / CDMO model.