Fund raise deleverages balance sheet, EPS accretive …
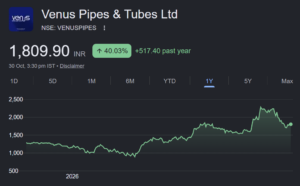
About the stock: Venus Pipes and Tubes (VPT), established in 2015, is engaged in manufacturing of stainless-steel pipes and tubes with total installed capacity pegged at ~48,000 metric tonnes per annum (MTPA), located in Gujarat.
• Within this, it has a capacity of, 20,400 MTPA- Seamless stainless-steel pipes and tubes and 27,600 MTPA- Welded stainless steel pipes tubes.
Investment Rationale:
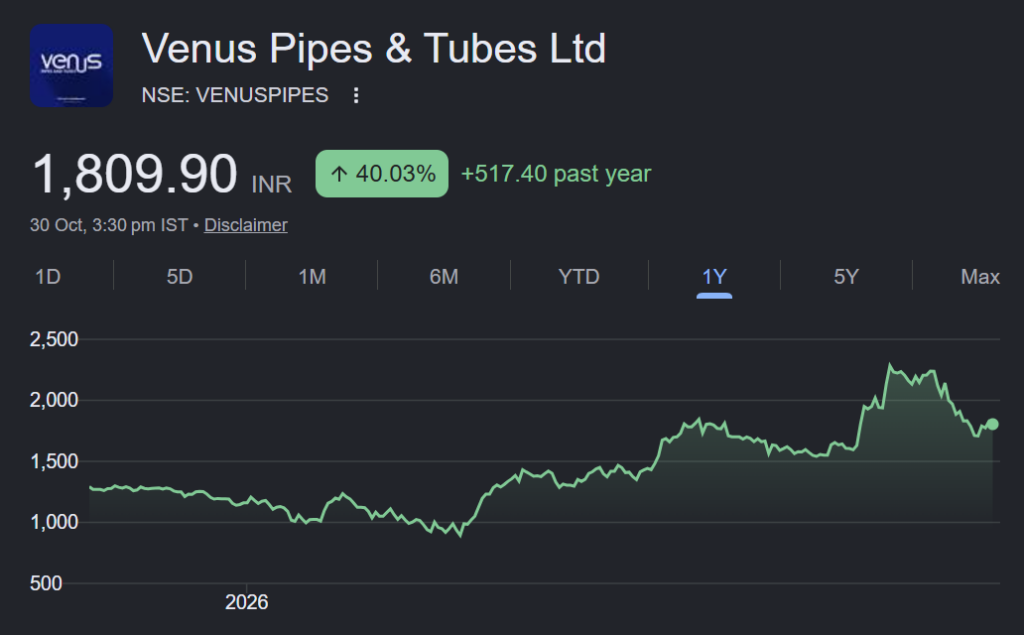
• Venus to turn net debt free post recent equity raise: In the recent past, VPT has approved & executed fresh equity raise in the form of preferential allotment from marquee investors worth ₹ 372 crore at ₹ 1,670 per share. It was primarily aimed at retirement of debt on B/S which as of FY26 end stood at ~₹ 286 crore. With equity raise in place, we expect Venus to turn net debt free in FY27E, thereby leading to substantial savings of interest expenses and turns out to be EPS accretive from our modelling perspective.
• Capacity expansion led growth to support long – term earnings growth : As per industry sources, domestic stainless-steel pipes and tubes industry is expected to grow at 6-8% CAGR over FY24-29E. VPT has capitalised on this opportunity by expanding its capacity ~4x over the past five years, from 12k MTPA in FY23 to current 48k MTPA. Notably, seamless pipes and tubes capacity has increased ~6x to 20.4k MTPA, strengthening its presence in higher-margin segment & increasing its market share to ~10%. Consequently, VPT delivered strong Sales and PAT CAGRs of ~32% and ~34%, respectively, over FY22-26. Going forward on the back of revival in private capex cycle domestically coupled with VPT’s capability in sunrise sectors, we bake in Sales/PAT CAGR of 17%/33% over FY26-28E.
• Expanding into high – value applications; data centre play: VPT is expanding its end-market exposure towards high-growth sectors such as data centres, semiconductors, and nuclear power, thereby reducing its dependence on traditional cyclical industries. The strategy is already gaining traction as the spooling facility has commenced commercial operations ahead of its scheduled timeline of Dec’26, supported by a Letter of Intent worth ₹185 crore from a leading data-centre customer for the supply of stainless-steel spools for cooling applications. Along with this, the current order book stands at ~₹600 crore supported by power, engineering, chemicals, oil & gas and other sectors. Also, the recent commissioning of fittings capacity will help increase the contribution of value-added products and support margin expansion. Accordingly, VPT’s EBITDA margins are expected to improve to 17%+ levels by FY28E.
Rating and Target Price: We maintain a positive view on Venus (VPT), supported by healthy double-digit volume-led earnings growth over the medium term, along with increasing presence in high-growth segments such as Data Centre, along with a growing portfolio of niche value-added product offerings, a net debt free/cash surplus B/S and healthy double digit return ratios. We reiterate our BUY rating on stock with a target price of ₹2, 34 0, i.e. 30x PE on FY28E.