Good H1; Festive season to strengthen performance in H2FY27
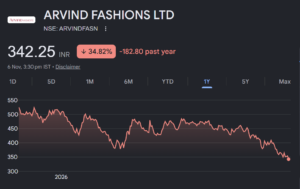
About the stock : Arvind Fashions Ltd. (AFL) is a multi-brand apparel company and has 5 brands: US Polo, Tommy Hilfiger, Arrow and Calvin Klein under license agreement and own in-house leading denim brand Flying Machine.
Q2FY27 performance: AFL’s revenues grew by 10% YoY to Rs.1559cr in Q2FY27. Growth was supported by 16% YoY growth in retail and 28% YoY growth in retail channel. LTL stood at 7.3% in Q2FY27 (Adjusted for festive season, LTL was at 10%). Gross margins improved 137bps YoY to 53.9% led by lower discounting and better channel mix. EBITDA margin improved by 67bps YoY to 13.9%. EBITDA grew by 16% YoY to Rs.216.4cr while Adjusted PAT grew by 29.6% YoY to Rs.48.9cr in Q2FY27.
Investment Rationale:
• H2FY27 revenues to grow in mid – double digits: AFL’s revenues grew by 12.4% in H1FY27 to Rs2,837cr, driven by healthy growth across retail (+17% YoY) and online B2C channels (+33% YoY). Retail LTL stood at high single digit in H1FY27 (Q1: 11.6% and Q2: 7.3%). Going ahead in H2FY27, Management indicated that the overall demand environment remains stable and positive despite geopolitical uncertainty and inflationary pressures. Consumer sales across channels have seen encouraging offtake in Oct,26, with festive sales tracking ahead of expectations thereby aiding high double digits LTL growth. On brand front, US Polo continues to deliver strong growth, while Tommy Hilfiger and Calvin Klein are gaining momentum following recovery from the GST-related disruption. With festive demand remaining healthy and key brands showing strong traction, management remains confident of delivering mid-teens revenue growth in H2FY27.
• EBITDA margins to expand by 30 – 40bps in H2FY27: AFL’s gross margin expanded by ~115bps to 55.1% in H1FY27, equally driven by lower discounting and a favourable channel mix. Subsequently, EBITDA margin improved by 55bps to 13.2% YoY as the company continued to invest in marketing (+24bps YoY) for its brands. In H2FY27, the management expects lower-cost inventory to support margins through Q3. Further, it expects ~5% input cost inflation from January as summer season 27 products will get introduce. It plans to offset it through MRP hikes of ~1.5–2%, along with continued focus on lower discounting, product innovation and premiumisation. Strong festive demand, with festive sales tracking ahead of expectations, is also expected to support sales and improve pricing. Hence, management expects 30– 40bps EBITDA margin expansion in H2FY27. Over the medium term, the company plans to increase the share of retail and online B2C channels from 53% currently to ~65%, which should further add on to profitability along with better product mix.
• AFL announces ~Rs. 100cr capex to strengthen focus on domestic sourcing : AFL incurred approximately Rs.100cr of capex in H1FY27 towards a new shirt manufacturing facility in Madhya Pradesh, a new corporate office and retail expansion. The shirt facility is aimed at strengthening India-based sourcing and reducing dependence on Bangladesh imports, which have faced geopolitical disruptions. The facility will have a monthly capacity of 3 lakh units and meet 25– 30% of the company’s total shirt requirements, with an expected payback period of 3–3.5 years. The facility will also help shorten production cycles, improve response to changing trends and provide better supply-chain control.
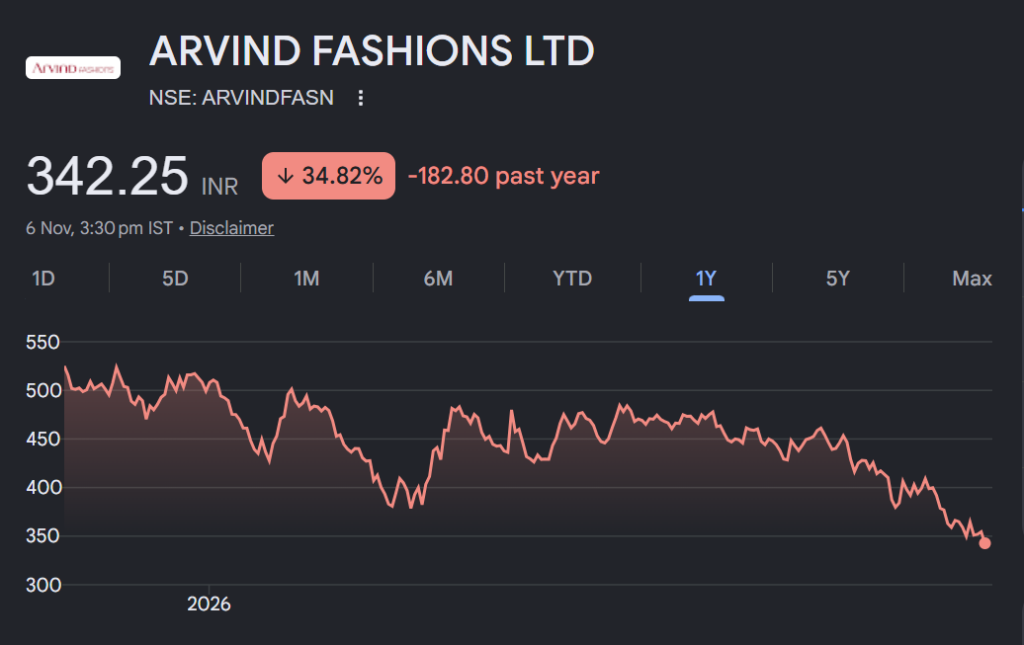
Rating and Target Price: We recommend Buy with a revised price target of Rs. 470 (valuing at 8x its FY28E EV/EBIDTA)