Strong deal momentum supports upgraded FY27 revenue outlook
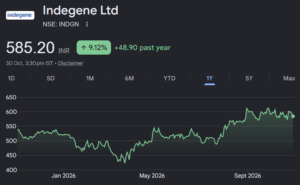
About the stock: Indegene is a digital-first commercialization partner focused on the global life sciences industry. It serves 20/20 top biopharma companies and operates across 80+ markets in 11+ countries.
Q2FY27 performance: Revenues came at ₹1,122.3 crore (US$117.5 million), up 5.6% QoQ/39.5% YoY in INR terms (4.4% QoQ/27.5% YoY in USD terms). EBITDA margin was up 20 bps QoQ/ down ~100 bps YoY at 16.5% impacted by wage hikes (-150 bps). PAT declined 3.4% QoQ but increased 10% YoY to ₹112.3 crore.
Investment Rationale:
• Strong deal wins and deeper client penetration to drive sustained growth: Indegene is witnessing broad-based growth across large and emerging clients, with active clients increasing to 107 (vs 76 YoY) and $1 million+ clients rising to 59 (vs. 40 YoY). During Q2FY27, it secured 9 deals with ACV >US$1 million, including 3 large deals, with expansion of existing engagements. Management expects commercial business to outpace medical over the next couple of quarters with stronger H2FY27 growth, supported by deal ramp – ups and healthy pipeline . It also expects organic growth rate for FY2 7 to be stronger than FY26. We expect US$ revenue to grow at CAGR of 14.2 % over FY26 – 29E.
• GenAI – led transformation and operating leverage to drive margin expansion: Indegene’s integrated GenAI capabilities, including Tectonic and Agentic AOR, enable it to move upstream across the pharma commercialisation value chain, creating opportunities for higher-value, outcome-based engagements. Tectonic’s quarterly revenue run rate increased to US$1.7 million, with contracted business exceeding US$2 million per quarter. Further, over 60% of revenue is outcome-aligned, supporting productivity-led scalability. Management expects m argin growth in H2 to outpace revenue growth and w ith wage hikes fully absorbed, it remains confident of achieving 19%+ quarterly EBITDA margin by Q4FY27, aided by operating leverage, productivity gains and ramp-up of outcome-based contracts. We bake in EBIT DA margins of 1 7.4 % /19%/19% in FY27E /FY28E /FY29E .
• Strong industry tailwinds and favourable outsourcing opportunity : The life sciences industry is benefiting from a favourable demand environment, driven by a recovery in pharma and biotech funding (+85% YoY), higher M&A activity, record drug approvals and an expanding late-stage development pipeline. Convergence across service offerings such as Agentic AOR, Tectonic and production points to an integrated, AI-led content model across the commercialization value chain. Rising GenAI adoption is further accelerating the shift towards partners combining deep domain expertise, proprietary data and technology capabilities, positioning Indegene to capture a larger share of the growing outsourcing opportunity
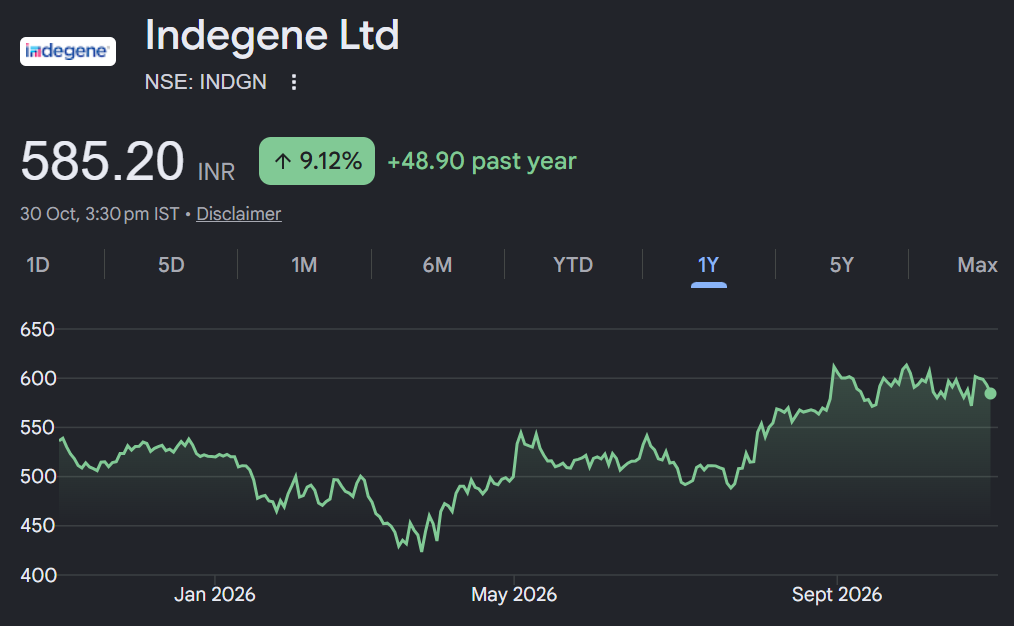
Rating and Target Price: Given sustained revenue momentum, expanding client relationships and management’s H2 margin expansion outlook, we maintain our BUY rating , with a target price of ₹750; valuing it at 27x P/E on FY28E EPS.