Strong Q2FY27; Guidance upgrade reinforces confidence
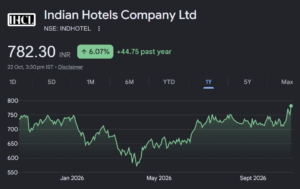
About the stock: Indian Hotels Company (IHCL) and its subsidiaries bring together a group of brands and businesses that offer fusion of warm Indian hospitality and world class services. It has 390 operational hotels and 280 hotels under development.
Q2FY27 performance: IHCL reported consolidated revenue growth of 21.7% YoY to Rs.2484cr led by 26% YoY growth in Standalone revenues. Standalone RevPAR stood at Rs.13680 growing by 28% YoY led by 700bps YoY expansion in occupancy and mid-teens ADR growth. Consolidated EBITDA margins expanded by 47bps YoY to 28.4% and EBITDA grew by 24% YoY to Rs.705.8cr. Adjusted PAT grew by 20.3% YoY to Rs.382.3cr in Q2FY27.
Investment Rationale:
• FY27 Revenue guidance revised upwards by 300bps to 15-17%: IHCL’s consolidated revenues grew 18% YoY in H1FY27, driven by 22% growth in standalone revenues and 19.8% growth in subsidiaries. Domestic performance was supported by strong leisure demand in Q1 and MICE-led traction in Q2. H2FY27 demand is expected to benefit from MICE events, alongside concerts, sporting events and ~40 wedding dates aiding F&B revenues. 30+ hotel openings, acquisition ramp-ups and renovation-led pricing power should complement LFL growth in H2FY27. International business recovery offers further upside, with London recording double-digit growth in October, San Francisco expected to recover fully over the next quarter and New York performing well. Management fee revenues grew ~53% in H1FY27, supported by additions to managed rooms, with further growth expected as the portfolio expands. Hence, management has revised its revenue guidance by 300bps to 15-17% for FY27 (from 12-15% earlier). Further, Management expects FY28 to outperform FY27, driven by acquisition ramp-ups, continued LFL growth, international recovery and 6-7% incremental revenues from Oriental Hotels merger. Management fee revenues are also expected to grow at a 15-20% CAGR ahead. Overall, we expect IHCL’s revenues to grow at a CAGR of 13% over FY26–29E to Rs.14,107cr.
• Asset upgrades, recovery in airline catering and international business to aid margin expansion: IHCL’s consolidated EBITDA margin expanded by 50bps YoY in H1FY27. Standalone margins expanded by 400bps, driven by strong domestic hospitality performance, operating leverage and improved pricing power following asset upgrades. However, subdued performance in Taj SATS and the international portfolio weighed on consolidated margin expansion. In H2FY27, sustained MICE demand, improved leisure travel and higher F&B revenues should support hotel business profitability. Management fee income is expected to grow by 15–20%, while better performance at international portfolio and Taj SATS, should further add to margins. We expect consolidated EBITDA margins to expand by 100bps YoY to 34% in FY27. Over FY26–29E, continued asset upgrades, sustained domestic demand and improving international performance should drive ~200bps margin expansion to ~35% by FY29E.
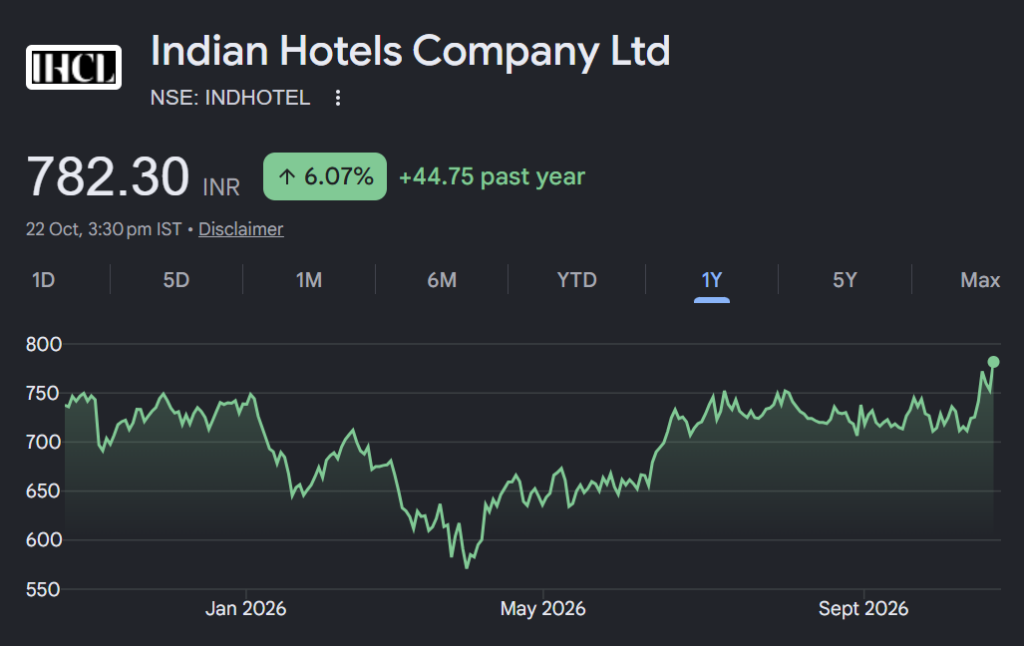
Rating and Target Price: In view of strong demand for luxury hotels and lower supply in tier I towns, IHCL is well place to maintain double digit revenue growth momentum ahead. We recommend Buy with revised price target of Rs.950 (rolling it over to average of FY28E-29E EBIDTA; valuing at 29x EV/EBIDTA).