Q2 unlocks NCR region…
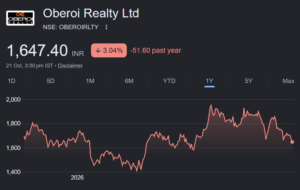
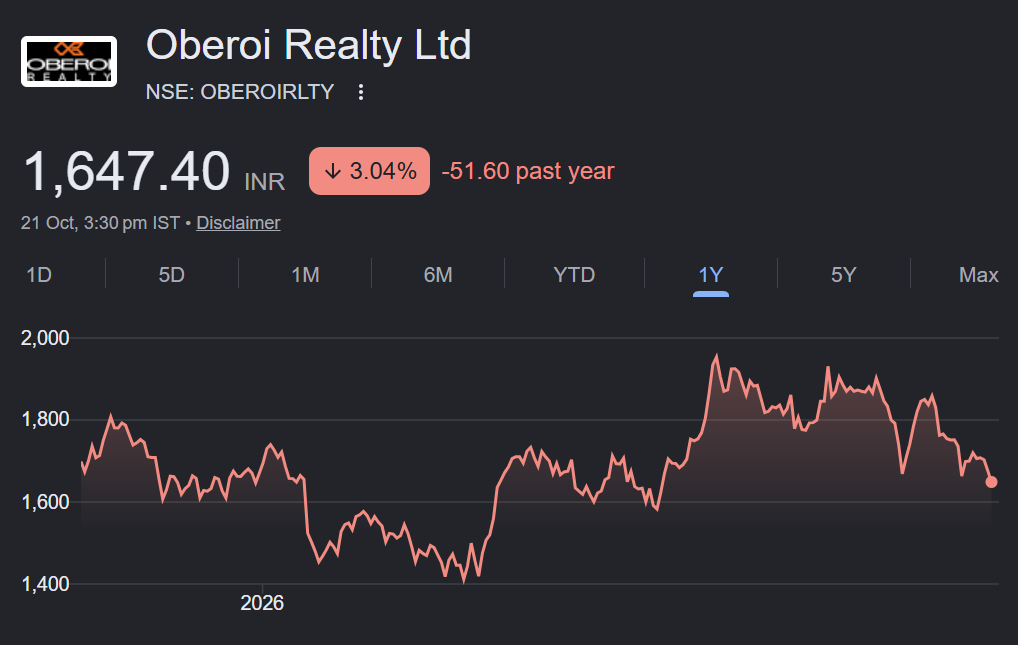
About the stock: Oberoi Realty Limited (OBEREA), is a Mumbai-based premium real estate developer focused on residential, office, retail and hospitality verticals.
• It has ~₹ 14,000 crore inventory across nine ongoing residential projects
• It is developing office, retail and hospitality assets at Borivali, Worli and Thane.
Q2FY27 performance: Oberoi Realty reported strong pre-sales for Q2FY27 at ₹ 9149.7 crore (up 7x YoY, 8x QoQ) led by robust response for project 360 North (Gurugram) phase 1 launch booking value of ₹ 7891 crore (~86% of Q2FY27 pre- sales). Collections stayed healthy at ₹ 2277 crore (up 68% YoY, 120% QoQ). Consolidated revenues for Q2FY27 were down 6% YoY at ₹ 1671 crore (up 28% QoQ) owing to high base (residential revenue booking had increased 34% YoY to ₹ 1409 crore during Q2FY26 vs ₹ 1248 in Q2FY27). EBITDA margins continue its improving trend in Q2FY27 to 61% (higher 364 bps YoY and 456 bps QoQ) led by residential business (higher 546 bps YoY and bps 956 QoQ to 60.5%). Consolidated net profit was at ₹ 762 crore (flat YoY, up 40% QoQ).
Investment Rationale:
• Robust launch pipeline to drive pre-sales growth: The company received an overwhelming response for its maiden luxury residential project launch, Three Sixty North, recording gross booking value of ₹ 8109 crore (13.52 lakh square feet carpet area). The phase 2 (~₹ 7500 crore) of the said project is expected to be launched in FY28 (awaiting additional approvals and resolution of Punjab and Haryana High court’s restraining order for fresh allotments). It has a strong launch pipeline for FY27 which includes 1) Pedder Road 2) Tower D, Forestville 3) Tower A, Jardine 4) Ralliwolf Mulund, 5) Enigma commercial strata sale 9) Adarsh Nagar, Worli, 10) Alibaug 11) Bandra, RLDA and 12) Borivali SRA project. We estimate its pre-sales to grow at 70+% CAGR over FY26-FY28E assuming entire phase 2 launch of Three Sixty North in FY28E.
• Investment properties remain steady QoQ: The company saw lease rentals rising by ~16% YoY (up 2% QoQ) during Q2FY27 to ₹ 370 crore. Occupancies at Oberoi Mall/ Commerz I, Commerz II and Commerz III remained steady at 99%/ 96%/ 100%/ 98% while Sky City Mall (83% Vs 82% in Q1FY27) marginally improved. Further, its hospitality business saw revenue growth of 2% YoY to ₹ 46 crore while EBITDA declined 6% YoY to ₹ 17 crore, owing to lower occupancy while Average Room Rates saw 15% YoY growth. It plans to open Marriott Hotel, Sky City during Q3FY28 and Ritz Carlton, Worli during Q1FY28. We estimate its rental income from both retail and office spaces to grow at ~17% CAGR over FY26-FY29E.
Rating and Target Price:
• Oberoi realty is expected to register robust pre-sales over the next two years led by a sturdy launch pipeline. Further, its scale up in annuity generating assets remain on track.
• We retain Buy on the stock with an unchanged SOTP based price target of ₹ 2200.