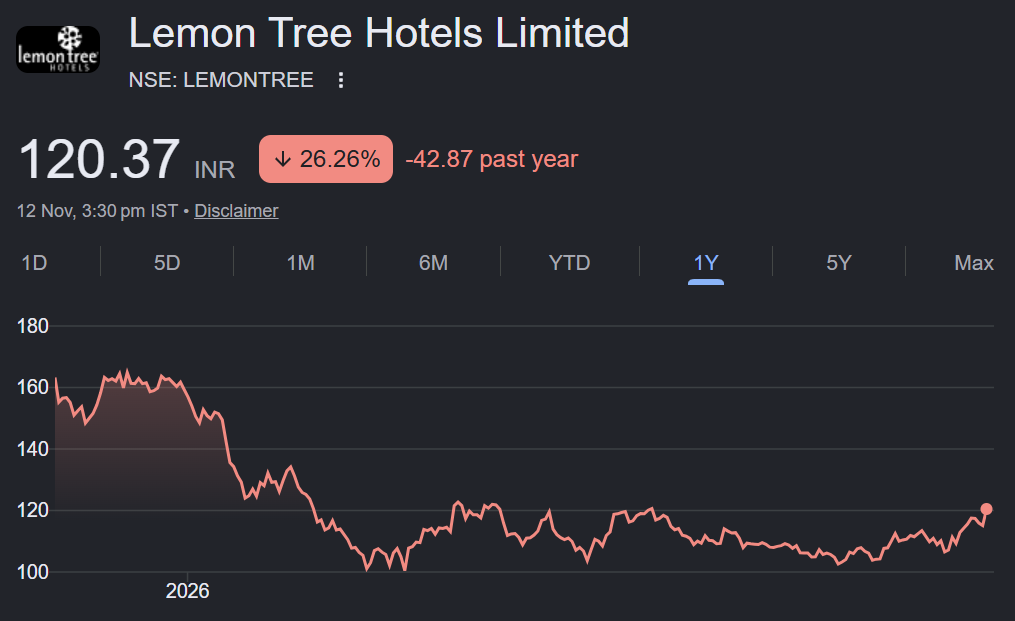
Healthy demand-led operating leverage and strong pipeline to drive earnings
Operating performance above our estimate
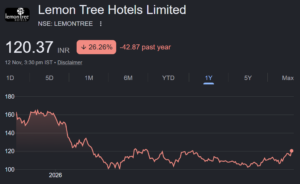
Lemon Tree Hotels (LEMONTRE) reported healthy revenue growth of 18% YoY in 2QFY27, led by 17%/31%/39% YoY growth in room revenue/ management fees/FnB revenue. Average room rate (ARR) grew 8% YoY to INR6,751, with occupancy rate (OR) expanding 633bp YoY to 76.1%. RevPAR growth was driven by stronger retail demand, while F&B growth was led by MICE, group business, banqueting, and weddings.
EBITDA margin stood at 44.2% (up 152bp) in 2QFY27, despite the combined impact of GST changes and stock appreciation rights (3.2% of sales)
Going forward, we expect LEMONTRE to show healthy growth, led by aggressive expansion through Fleur (pipeline of ~3,400 keys by FY30), accelerating asset-light management fee income, premiumization via Aurika, and improving operating leverage as renovation, GST, and technology- related cost pressures normalize.
We largely maintain our FY27/FY28 EBITDA estimates and reiterate our BUY rating on the stock with an SoTP-based TP of INR140. Healthy RevPAR growth drives performance
LEMONTRE’s revenue grew ~18% YoY to INR3.6b (est. in line). OR expanded 633bp YoY to 76.1%. ARR increased 8% YoY to INR6,751. Management fees grew 31% YoY to INR187m.
The company’s EBITDA grew 22% YoY to INR1.6b (est. INR1.5b). EBITDA margin expanded 152bp YoY to ~44.2% (est. 43.9%) Adj. PAT grew ~16% YoY to INR401m (est. INR496m)
For 1HFY27, LEMONTRE’s revenue/EBITDA/Adj PAT grew 13%/14%/18% to INR7.1b/INR3.1b/INR861m
Gross debt stood at INR14.3b vs INR15b as of Mar’26. The company’s CFO stood at INR3.1b vs INR2.3b as of Sep’25.
Exceptional items stood at INR220.9m in 2QFY27, including a property tax provision (INR158.3m), impairment of investment in an associate (INR334.7m) and acquisition-related expenses (INR36.6m), partly offset by a lease termination gain of INR416.4m. Highlights from the management commentary
Development pipeline and expansion: The company expects to open ~2,000 rooms on a gross basis in FY27, compared with ~1,523 rooms in the previous year, with the opening rate expected to accelerate further from FY28 onwards. During 2QFY27, it opened eight managed and franchised hotels comprising 523 rooms and signed 11 hotels with 825 rooms. The company is working towards adding ~2,300 rooms through a combination of operational brownfield acquisitions and greenfield developments by FY30–31.
Omaxe: The partnership covers ~4,000 rooms across 10 properties, primarily in Tier-2 and Tier-3 cities, including Lucknow and Greater Noida. These locations offer access to residential, transit and commercial demand, with bus stations typically situated in prime city-center locations. Nine of the 10 properties are greenfield developments, with Omaxe owning the land and undertaking the development, while Lemon Tree will act as the hotel manager and brand owner without any capital investment
Bandra East, Mumbai: LEMONTRE acquired land in Bandra East, adjoining the Bandra-Kurla Complex (BKC), for ~INR1.2b to develop an upscale Lemon Tree Premier hotel with ~172 rooms, targeted to open in FY30. This will be the company’s seventh hotel in Mumbai and its first in Bandra. The project is expected to entail an investment of ~INR20m per key, with management targeting an opening ARR of ~INR12,000. The hotel will primarily target corporate demand from BKC rather than relying on the broader Mumbai market
Valuation and view
The company is expected to maintain a healthy growth momentum going forward, fueled by: 1) accelerated growth in management contracts (with a pipeline of ~10,846 rooms), 2) rebranding of existing hotels, 3) expansion of the Aurika portfolio, 4) strong backing from Warburg Pincus, 5) improved yields following the completion of renovations across brands, and 6) the addition of owned hotels through Fleur (3,400 keys).
We expect LEMONTRE to post a CAGR of 10%/14%/22% in revenue/EBITDA/adj. PAT over FY26-28, with RoCE improving to ~18% by FY28 from ~13.1% in FY26. We reiterate our BUY rating on the stock with an SoTP-based TP of INR140.