Capex momentum intact, ROW delays temper near term capitalisation
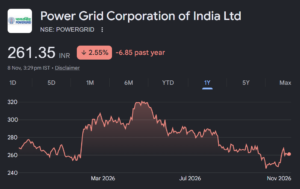
About the stock : PowerGrid is India’s largest power transmission utility with transmission lines of 187,576 circuit km (ckm) and 6,49,116 MVA of transformation capacity.
• Powergrid transmits ~45% of the total power generated in India on its transmission network & owns ~84% of Inter-State transmission system.
• It also undertakes transmission related consultancy to more than 150 domestic clients and owns & operates ~100,000 km of telecom network.
Q2FY27 performance : Power Grid Corporation of India (PGCIL) reported a subdued Q2FY27 performance, with revenue from operations remaining largely flat at ₹10,048 crore (+0.5% YoY). EBITDA increased 2.8% YoY to ₹8,237 crore, while EBITDA margin expanded 190 bps YoY to 82.0%. Adjusted PAT grew 7.4% YoY to ₹3,819 crore.
Investment Rationale:
• Strong transmission capex pipeline to drive sustained asset growth : PGCIL remains well positioned to benefit from India’s expanding transmission infrastructure, supported by a substantial ₹2.20 lakh crore works-in-hand and a ₹67,233 crore TBCB bidding pipeline. The company has revised its FY27 capex guidance upwards to ₹37,000–40,000 crore from the earlier ₹37,000 crore. However, capitalisation guidance has been moderated to ₹25,000–30,000 crore from ₹30,000 crore earlier, primarily due to right-of-way (RoW) and land acquisition delays. H1FY27 capex stood at ₹16,864 crore, up 10% YoY, whereas capitalizations were ₹9,300 crore compared with ₹3,888 crore in H1FY26. The higher capex guidance reflects continued investments in the transmission network, while the revised capitalization range indicates some moderation in expected asset commissioning. Nevertheless, the sizeable project pipeline provides healthy visibility for asset creation over the medium term.
• Structural transmission investment opportunity to support long – term earnings visibility : PGCIL is a key beneficiary of the country’s energy transition and rising electricity demand, with the ₹1.86 lakh crore Green Energy Corridor-III scheme expected to facilitate evacuation of 135 GW of renewable energy and deployment of 50 GWh of BESS by FY33. Additionally, the ₹67,233 crore TBCB bidding pipeline, comprising 28 projects under bidding and three projects yet to be floated, provides visibility for incremental order wins. Emerging investments in renewable energy evacuation, green hydrogen, data centres and hydro-power projects are expected to sustain transmission infrastructure spending.
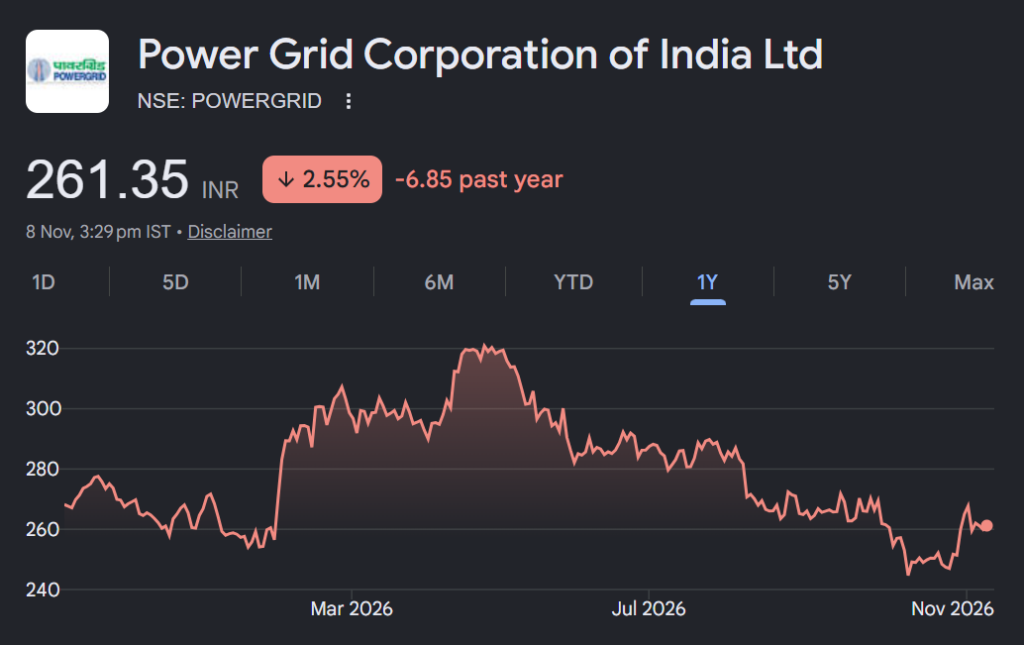
• Rating and Target Price: We expect revenues and PAT to grow at CAGR of 9.0% and 2.6% over FY26-FY28E. We recommend BUY on POWERGRID with a target price of ₹325 per share (based on 17 x F Y28E EPS).