Capacity expansion to drive the next leg of growth!
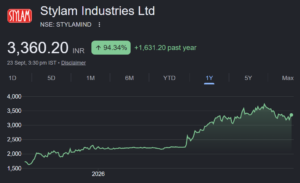
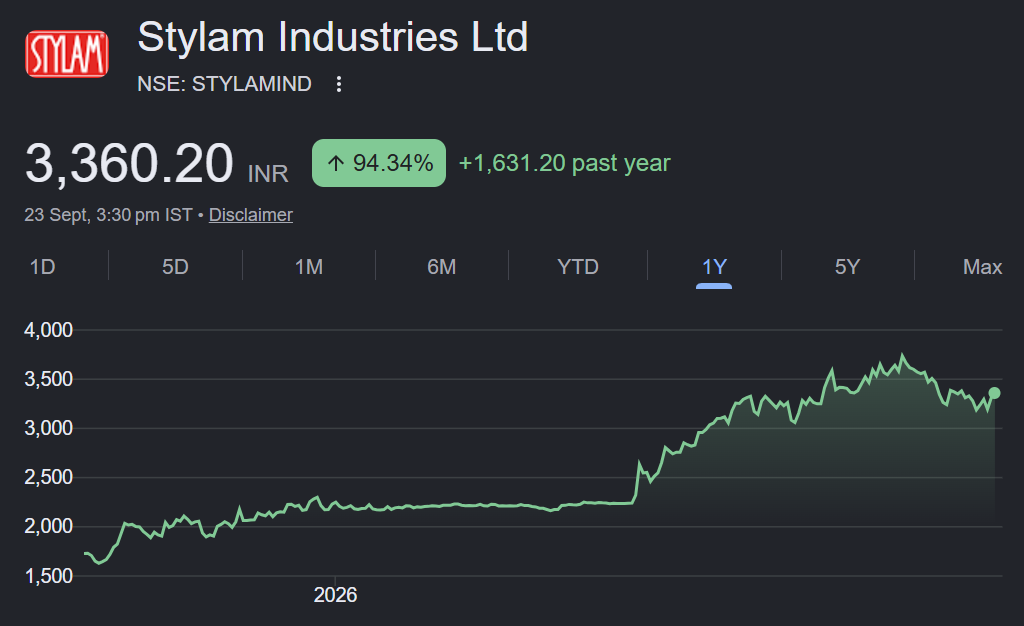
About the stock : Founded in 1991 and headquartered in Chandigarh, India, Stylam Industries Limited manufactures decorative laminates and premium surfacing solutions for residential, commercial, and infrastructure applications.
• Over the years, the company has evolved from a regional manufacturer into an international surface solutions player, with a presence in more than 80 countries. Its export-led business model, manufacturing capabilities, and expanding product portfolio position it to participate in the growing global demand for premium decorative surfaces.
Investment Rationale:
• Capacity expansion and pricing actions to drive 1 9.4 % revenue CAGR over FY26 – 28E : Stylam is entering a new phase of growth with the commissioning of its Manak Tabra manufacturing facility (~52.5MSM), which has now commenced production in September 2026. Management is targeting ~₹300 crore in additional revenue in FY27, with the facility expected to generate ₹700-1,000 crore in incremental annual revenue as utilization scales up over the subsequent two to three years. In addition, it has announced a 3-5% price hike. Hence, we estimate Stylam’s revenue to grow at a CAGR of ~19.4% over FY26-28E, supported by incremental capacity, pricing actions, and the gradual ramp-up of the new facility.
• Healthy Balance sheet & strong promoter pedigree: Stylam maintains an exceptionally robust balance sheet characterized by a net debt-free status, strong liquidity, and conservative financial leverage, which has enabled Stylam to fund major capital expenditure initiatives, including the ~₹334 crore expansion, primarily through internal accruals. The strong cash balance positions Stylam to seamlessly navigate raw material price cycles, support working capital needs during rapid revenue scaling, and reward shareholders. We note Aica Kogyo’s presence as a promoter group (40% stake) adds a potential strategic dimension with experience in materials and surface – related businesses, while giving a closure to earlier promoters’ family dispute
• Margins to remain in a healthy band: Stylam has demonstrated healthy profitability alongside improvements in asset utilization. EBITDA margins stood at 21.1% in Q1FY27 vs. 18.1% in FY25, while gross block turnover improved to 2.8x in FY26 from 2.1x in FY22. We estimate EBITDA margins of 19% in FY27E and 20% in FY28E, factoring in the initial underutilization of the new facility and the potential for operating leverage as production scales up. The margin outlook also reflects ongoing raw material cost pressures and the company’s ability to sustain pricing discipline
Rating and Target Price: Stylam’s capacity expansion, established export franchise, and conservative balance sheet provide the foundation for its next phase of growth. The ramp-up of the Manak Tabra facility remains the key earnings catalyst with operating margin resilience and capital allocation discipline, while Aica Kogyo’s presence as a promoter group adds a potential strategic dimension. We initiate coverage with a BUY rating and a target price of ₹400 0 at 31x FY28E EPS, providing an upside potential of ~ 22%.