QC Shifts Gears to Growth; Margin Reset by Design
Key Points
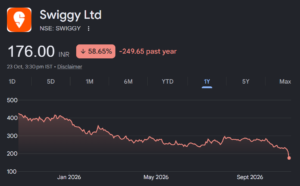
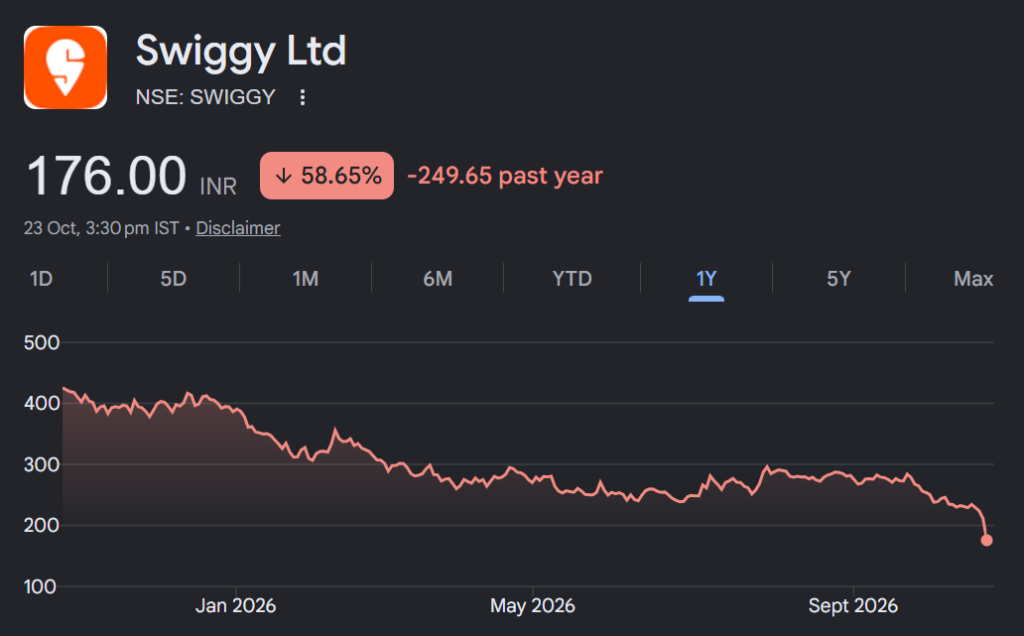
Swiggy reported consolidated revenue of Rs75,710mn (+36% YoY / +11% QoQ), 2% above our estimates and 2.8% above consensus. EBITDA loss of Rs7,700mn (-10.2% margin; +410bps YoY, -63bps QoQ) was ~41% wider than our estimate of Rs5,470mn, and 33% below consensus, as Instamart stepped up growth investment and losses from Platform Innovations (incl. Toing) increased. PAT at -Rs9,220mn narrowed 16% YoY but widened 17% QoQ. B2C GOV came in at Rs207,930mn (+24.6% YoY); platform MTUs at 27.8mn (+21% YoY).
Food delivery — record margin, acceleration continues: GOV grew 17.7% YoY / 5.9% QoQ to Rs100,540mn, exiting Sep-26 at over 20% YoY. Adj. EBITDA of Rs3,410mn (+42% YoY) is at a best-ever 3.4% of GOV (+58bps YoY, +32bps QoQ); take rate is at a record 26.1%. MTUs are at 19.8mn (+15% YoY) and contribution margin is 7.7% of GOV. Management reaffirmed 18-20% GOV growth (ex-Toing) and the ~5% steady-state Adj. EBITDA margin target.
Quick commerce — growth inflects, margin reset: GOV grew 31.4% YoY / 16.7% QoQ to Rs92,300mn on strong retention/frequency gains. But, contribution margin slipped to -1.0% of GOV (+157bps YoY, -82bps QoQ) and Adj. EBITDA loss widened to -Rs8,950mn (-9.7% of GOV; +Rs1,180mn QoQ) as Swiggy deliberately re- prioritised growth. Addition of 69 net dark stores for a total of 1,240 across 133 cities, with differentiated assortment (Noice/Nectar now ~1 in 8 orders). Guidance: double- digit sequential GOV growth, contribution margin held at 0 to -1% with ~100bps QoQ EBITDA improvement in 3Q.
Out-of-Home and others: Dineout GOV was Rs15,080mn (+34.9% YoY / -1.4% QoQ), Adj. EBITDA was Rs80mn (0.5% of GOV) — a seventh straight profitable quarter. The active restaurant base stood at 66,000. Supply chain & distribution revenue rose +44% YoY to Rs36,900mn with Adj. EBITDA loss of Rs510mn. Platform Innovations Adj. EBITDA loss widened to Rs1,620mn, mainly due to the Toing new- user acquisition.
Toing – affordability optionality: Swiggy is scaling Toing, a standalone value food- delivery app now in 50+ cities, as a purpose-built affordability platform on its existing tech chassis (near-zero incremental fixed cost; spend is discretionary new-user acquisition). Two of three Toing users are new-to-Swiggy or long-dormant, and dual-app users transact ~25% more frequently; early cities are turning unit-economics positive for repeat users. Management frames Toing as both insurance of, and option on, a large profit pool, and sees it lifting combined food-delivery market growth at 25-30% (vs 18-20% standalone). Investment to stay range-bound; a scale-up call is expected in 1-2 quarters.
Outlook and valuation: Food delivery segment is at record profitability and Instamart growth sharply re-accelerated but 2QFY27 confirms Swiggy is now firmly in Instamart’s pivot-to-growth phase, where quick-commerce contribution margin and consolidated losses move backwards in the near-term by design. We trim FY27E/FY28E EBITDA (deeper QC losses, higher Platform Innovations burn), pushing out the consolidated loss glide-path. The quick-commerce reset is deliberate and quality led (record Month-1 retention, differentiated assortment), and the IOCC-enabled 1P inventory transition starting mid-3Q over 2-3 quarters should add a ~80bps contribution-margin lever. Net- cash balance sheet intact.
We retain our BUY rating with a reduced target price of Rs340 from Rs355 (valuing food delivery at ~30x Sep-28E EV/EBITDA, Instamart at ~0.5x EV/GOV on a mid-30s % GOV CAGR). Quick-commerce competitive intensity and the contribution-margin trajectory, Toing scale-up economics, IOCC/1P execution, and the Platform Innovations burn remain key monitorables.