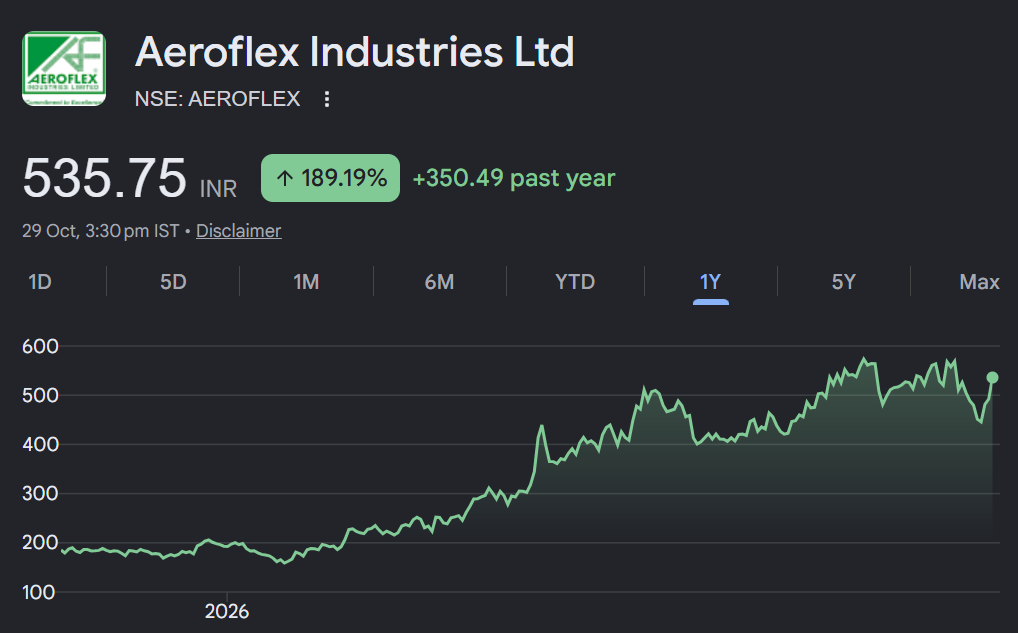
Strong growth outlook; capacity expansion to support scale up…
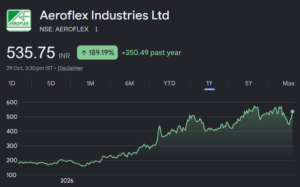
About the stock: Aeroflex Industries Limited (AERIND), incorporated in 1993, is engaged in the business of manufacturing and supply of metallic flexible flow solutions made with stainless steel.
• FY26 revenue Mix: ~69% from exports, ~31% from domestic markets.
• Segmental Revenue Mix Q2FY27: SS Flexible Hoses (34%), Assemblies & Others (41%), Data Centre SFN Skid Assemblies (25%).
Q2FY27 performance: Aeroflex Industries reported strong quarterly performance in Q2FY27, with consolidated revenue from operations increasing 87.0% YoY to ₹207.4 crore. EBITDA grew 94.5% YoY to ₹50.3 crore, with EBITDA margin expanding 93 bps YoY to 24.3%. PAT surged 156.9% YoY to ₹36.6 crore, with PAT margin improving to 17.6% from 12.8% in Q2FY26. PAT growth was partly supported by lower depreciation following the change from WDV to SLM, which reduced depreciation expense by ₹8.4 crore in Q2FY27.
Investment Rationale:
• Strong growth in liquid cooling solutions and value – added products to drive revenue expansion: Aeroflex Industries is increasingly positioning itself as a supplier of integrated flow-control and liquid cooling solutions, beyond its core stainless-steel flexible hose business. Liquid cooling skid assembly revenue is targeted at ₹150–200 crore in FY27, up from the initial target of ₹125 crore, reflecting faster-than-expected business ramp-up. With global liquid cooling markets estimated by management at US$4–5 billion and growing at over 30% annually, rising AI-led data-centre investments provide a structural growth opportunity. Aeroflex is also exploring international skid supplies through discussions with existing and new global customers, which could create an additional growth avenue beyond domestic demand.
• Capacity expansion and operating leverage to support earnings growth and margin sustainability: Aeroflex has expanded stainless-steel hose capacity to 20 million metres per annum and plans to increase it to 30 million metres, alongside liquid cooling skid capacity expansion to 30,000 units per annum by March 2028, through a planned investment of ₹202 crore. Management expects the incremental capacity to offer annual revenue potential of ₹500–550 crore at peak utilisation, with the expanded facilities expected to reach peak utilisation in FY30. The company targets FY27 revenue of ₹715–725 crore, implying approximately 60% growth, and has outlined a longer-term revenue ambition of around ₹1,500 crore by FY30, while targeting EBITDA margins of approximately 25% or higher. Higher utilisation, a richer product mix could support profitability as the business scales.
• Rating and Target Price: We expect the company to deliver a strong CAGR of 40.6% and 52.7% in revenues and PAT, respectively over FY26-FY29E. We value the company at 50 x FY2 9E EPS to arrive at a fair value of Rs. 765 with a Buy Rating.