Strong order book and diversification to drive growth…
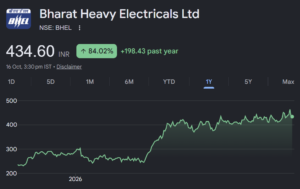
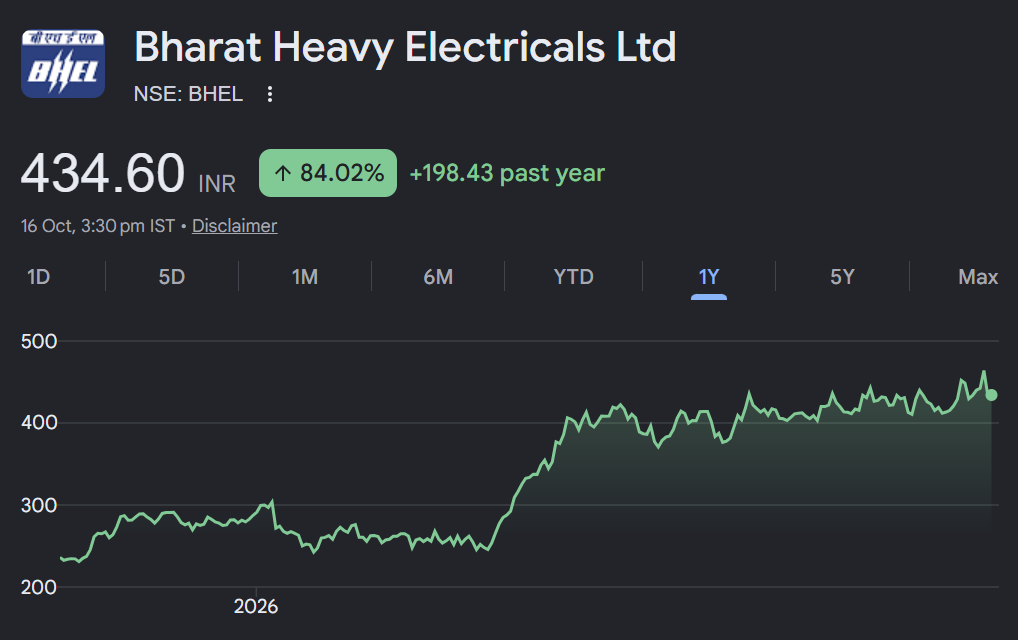
About the stock: BHEL is one of the largest engineering and manufacturing company of its kind in India engaged in design, engineering, construction, testing, commissioning and servicing of a wide range of products and services with over 180 product offerings to meet the ever-growing needs of the core sectors of economy. It operates in Power (~75% revenue mix) and Industrial (~25%) sector largely in India. Q 2F Y2 7 performance : Bharat Heavy Electricals Ltd. (BHEL) reported a strong Q2FY27 performance, with revenue increasing 23.8% YoY to ₹9,300.4 crore (vs. ₹7,511.8 crore). EBITDA increased 76.6% YoY to ₹1,026 crore (vs. ₹581 crore), with EBITDA margin expanding to 11.0% from 7.7%. PAT increased 120.1% YoY to ₹808.9 crore (vs. ₹367.7 crore), with net profit margin improving to 8.7% from 4.9%.
Investment Rationale:
• Record order book and diversified order pipeline provide strong multi – year revenue visibility: BHEL reported H1FY27 order inflows of ~₹30,000 crore, including ~₹4,000 crore in Q2FY27, taking its outstanding order book to a record ₹2.58 lakh crore (book to bill of 7.6x FY26 revenue) as of September 2026 (+17.3% YoY). The order book remains diversified beyond conventional thermal power, with sizeable non-thermal orders across transportation (~₹16,400 crore), transmission (~₹13,600 crore), nuclear (~₹12,800 crore), defence (~₹7,300 crore), hydro (~₹6,400 crore) and coal gasification (~₹9,000 crore). This diversification, supported by ongoing investments in power generation, grid expansion, rail mobility and defence indigenisation, provides a strong platform for sustained execution over the medium term.
• Execution – led turnaround with structural margin expansion potential: BHEL’s Q2FY27 performance reflects improving operating leverage, with EBITDA margin expanding to 11% from 7.7% in Q2FY26, while PAT increased 120% YoY to ₹809 crore. We believe sustained execution of the record ₹2.58 lakh crore order book, better fixed-cost absorption and a rising contribution from higher-value businesses such as spares and services, transmission, nuclear and defence can support further profitability improvement. Operational progress remains encouraging, with 2,260 MW of capacity addition achieved in H1FY27 against the FY27 target of 4,790 MW, alongside improved receivable days of 94 versus 120 days a year ago. Continued execution discipline, timely billing and collections should support cash generation and the conversion of revenue growth into sustainable earnings; however, margin sustainability and working-capital efficiency remain key monitorable.
• Rating and Target Price: We expect the revenues and PAT to grow at a CAGR of ~31% and 95% over FY26-FY28E. This will also improve ROCE from mid-single digit to ~17.5% ROCE in FY28E. Hence, we rate the stock BUY with fair value of ₹605 (35x FY28E EPS)