Healthy outlook maintained!
About the stock: Carysil stands as a global leader in kitchen solutions, specializing in premium quartz and stainless-steel sinks, faucets, and built-in appliances. Headquartered in India, with subsidiaries in the UK, Germany, and the UAE, Carysil’s reach extends to over 58 countries.
• With the ramp up of its new capacities, Carysil has guided for a 15-20% topline growth in medium term.
Q2FY27 performance: Carysil reported 14.6% YoY growth in consolidated revenue to ₹275.7 crore in Q2FY27, driven by healthy volume growth across its key product categories. Quartz sink and stainless-steel sink volumes grew 9.9% and 7.8% YoY to 217,000 units and 47,000 units, respectively, while faucet volumes increased 8% to 10,000 units. Capacity utilisation remained healthy at 92% for quartz sinks and 91% for steel sinks. Kitchen appliances volumes remained largely flat at 11,000 units. EBITDA grew at a slower pace of 12.3% YoY to ₹51.8 crore, with margins contracting 38 bps to 18.8%, impacted by elevated sea freight and raw material costs, which together affected margins by ~150–200bps. PAT increased 4.3% YoY to ₹28.4 crore.
Investment Rationale:
• Healthy outlook maintained: The Management retained its FY27 revenue growth guidance of 15% and EBITDA margin guidance of 18–20%, with an aspiration to remain at the upper end of the margin band. Revenue growth could exceed guidance if pending large deals materialise. Domestic revenue is targeted to reach ₹500 crore over the next 3–4 years, supported by improving profitability as input and freight costs normalise. The company implemented a 5% price hike across product categories last month. With raw material prices stabilising and freight rates cooling off, management expects gradual margin recovery. With this, we maintain our consolidated revenue growth projection at a CAGR of 16.3% over FY26-28, with margins at 19.5% and 19.7% for FY27/FY28, respectively.
• Capex on schedule: To fulfill the growing demand, major capacity additions remain firmly on schedule for commissioning by the end of FY27. These expansions include 250,000 new units for quartz sinks, 150,000 units for stainless steel sinks, and the doubling of both kitchen appliances and faucet capacities to 100,000 units each. The company indicated that it is managing surge orders by implementing strategic employee incentive schemes and optimizing production cycles to run over 100% capacity during peak demand periods, till the new capacities come online, ensuring that global supply chain opportunities are fully capitalized upon.
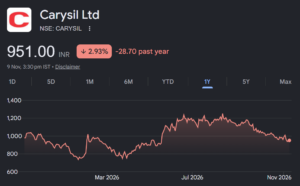
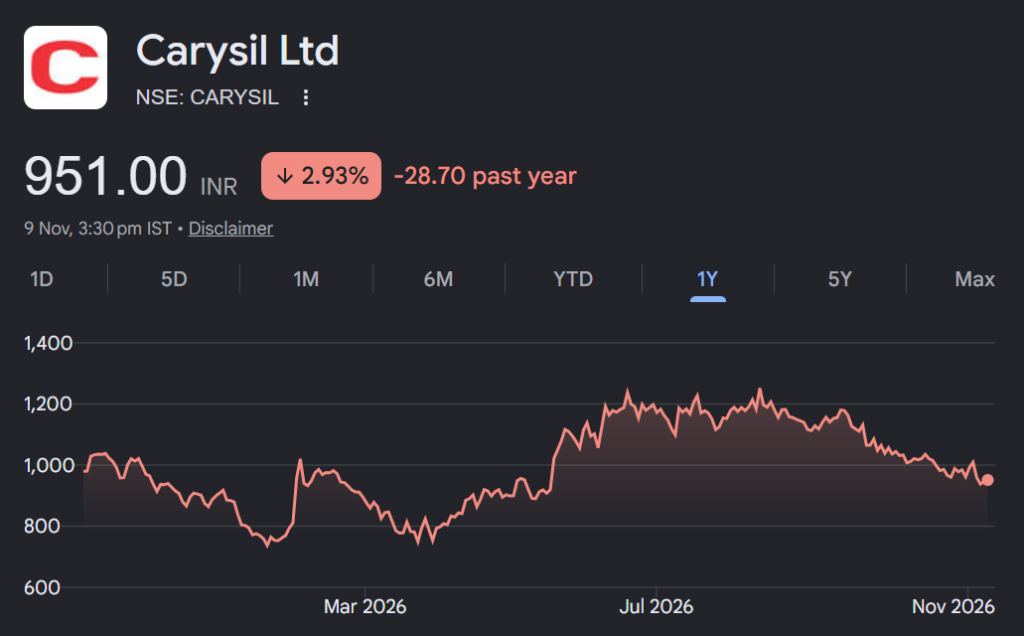
Rating and Target Price: We maintain BUY rating for Carysil with a revised price target of Rs.1250 valuing it at 25x its FY28E EPS