BEML is emerging as a key player in India’s railway, metro and defence manufacturing ecosystem, with ICICI Direct and Elara Capital maintaining a Buy outlook amid a robust order pipeline and improving growth prospects.
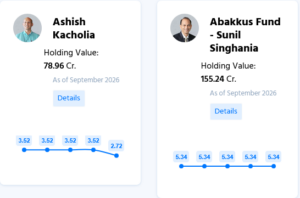
BEML Ltd has attracted investor attention after Sunil Singhania’s Abakkus Flexi Cap Fund acquired a 1.08% stake in the company, valued at approximately ₹179 crore. The investment comes as the state-owned engineering company undergoes a strategic transformation, expanding beyond its traditional mining and rail equipment businesses into a broader indigenous mobility, railway and defence manufacturing platform.
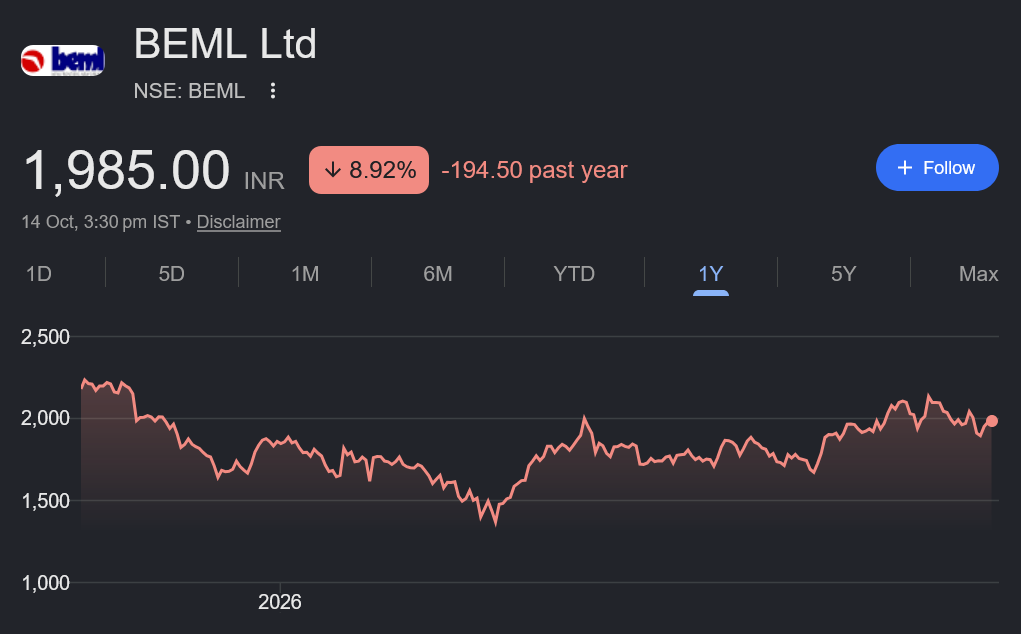
The development has added to the interest surrounding BEML, with domestic brokerage firms ICICI Direct and Elara Capital maintaining positive views on its long-term growth prospects. ICICI Direct has recommended a Buy rating with a target price of ₹2,765, implying an upside of approximately 40% from the reference market price. Elara Capital has also retained its Buy recommendation, with a revised target price of ₹2,700.
The optimism is underpinned by BEML’s sizeable order book, the anticipated ramp-up in railway and metro execution, expanding defence opportunities and the potential for margin improvement over the coming years.
BEML’s transformation: From mining equipment to mobility and defence
BEML is increasingly positioning itself as an important domestic engineering platform benefiting from India’s investments in railway modernisation, urban transportation, strategic defence systems and aerospace manufacturing.
Historically associated with mining equipment and heavy engineering, the company is now seeing a growing contribution from its Rail & Metro and Defence & Aerospace businesses. This shift could improve revenue visibility by reducing its dependence on traditional mining-related demand and increasing exposure to large, multi-year government and infrastructure programmes.
According to ICICI Direct, BEML’s order book stood at ₹16,285 crore, with Rail & Metro accounting for approximately 65% of the total. This provides a substantial base for future execution, particularly as railway and metro projects move into more active delivery phases.
The company’s expanding role across Vande Bharat sleeper trains, metro coaches, LHB coaches, commuter rail and high-speed rail projects could support a sustained growth trajectory over the medium term.
ICICI Direct: Rail & Metro to drive the next phase of growth
ICICI Direct believes Rail & Metro will be the principal growth driver for BEML as the business transitions towards a more diversified engineering and manufacturing model.
The brokerage estimates that Rail & Metro revenue could rise from ₹1,044 crore in FY26 to ₹2,067 crore in FY27 and ₹3,101 crore in FY28. Consequently, the segment’s contribution to overall revenue is projected to increase from approximately 24% to around 45% by FY28.
This anticipated growth is supported by multiple programmes, including Vande Bharat sleeper trains, metro rail projects, LHB coaches, commuter rail systems and high-speed rail initiatives.
ICICI Direct also expects Rail & Metro to account for approximately 65–70% of BEML’s targeted FY27 order inflows. The opportunity pipeline includes six commuter-rail tenders, Vande Bharat-related opportunities, bullet trains and several metro projects.
Capacity expansion is another important factor. BEML’s ADITYA facility is expected to support annual production of approximately 100 metro coaches and 50–70 high-speed rail coaches. The upcoming BRAHMA facility is expected to add capacity for another 300–350 coaches annually.
These investments could help the company handle a larger order pipeline, improve execution capabilities and strengthen its position in India’s expanding rail manufacturing market.
Defence business offers another growth engine
Beyond railways, BEML’s Defence & Aerospace division is emerging as an important contributor to its future growth.
The company is moving beyond conventional mobility equipment towards indigenously developed, higher-value defence platforms. Its portfolio includes 12×12 high-mobility vehicles (HMVs), light armoured mobility vehicles (LAMVs), armoured recovery vehicles (ARVs) and other strategic systems.
ICICI Direct notes that BEML’s 12×12 HMV has completed trials and is qualified for programmes associated with Pinaka, BrahMos and the Long Range Surface-to-Air Missile (LRSAM) system.
The brokerage identifies potential defence order inflows of ₹4,000–5,000 crore in FY27, excluding Pinaka-related opportunities. An additional opportunity worth approximately ₹600–700 crore could arise from QRSAM supporting vehicles.
BEML’s participation in the Advanced Medium Combat Aircraft (AMCA) consortium also provides a longer-term opportunity in aerospace manufacturing. The prototype programme carries an indicative outlay of approximately ₹15,000 crore, although the scale and timing of any potential benefits to BEML will depend on programme development and the company’s eventual role.
ICICI Direct estimates Defence & Aerospace revenue to increase from ₹1,523 crore in FY26 to ₹2,120 crore in FY28, supported by higher defence procurement and increasing localisation.
The combination of mobility platforms, strategic defence equipment and aerospace opportunities could broaden BEML’s addressable market and support a more diversified earnings profile.
Elara Capital expects double-digit revenue growth from FY27
Elara Capital also sees the potential for BEML to enter a stronger growth phase from FY27, supported by improving execution across its railway, metro and defence order books.
The brokerage highlights the company’s order book of approximately ₹16,000 crore, with a significant proportion linked to Rail & Metro and defence projects. As execution accelerates, Elara expects revenue growth to move into double-digit territory.
However, the brokerage remains cautious about near-term execution risks. Although management retained its FY26 revenue growth target of 20%, along with an anticipated 150-basis-point improvement in margins, Elara considers this target challenging given that revenue declined 1% year-on-year in the first half.
The brokerage has also factored in a slight delay in the execution of the Vande Bharat sleeper train order during FY26, prompting it to revise its target price to ₹2,700, based on 37 times its September FY27 estimated earnings per share.
Despite this adjustment, Elara has retained its Buy rating. Its positive outlook rests on the prospect of double-digit earnings growth over FY25–FY28, an expanding order pipeline, greater revenue visibility and the potential for margin expansion.
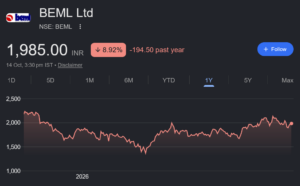
The brokerage also noted that BEML shares had underperformed the Nifty by approximately 25% over the preceding three months, a factor that could influence investor assessments of its valuation and recovery potential.
Railway projects could provide substantial order visibility
BEML’s railway and metro business is supported by a pipeline of large projects that could sustain demand beyond its existing order book.
One of the most significant prospective opportunities highlighted by Elara Capital is the Mumbai Rail Vikas Corporation’s air-conditioned electric multiple unit (AC EMU) project, estimated to be worth ₹35,000–40,000 crore. The brokerage expects the order to emerge over the following six months, although the actual award timing and BEML’s potential share remain uncertain.
Other opportunities include additional LHB coach orders, commuter rail projects and a sizeable metro pipeline comprising approximately 1,200–1,300 cars over the next two years.
Execution across existing projects is also expected to gather pace. BEML anticipates delivering two Vande Bharat sleeper trainsets per month following the necessary clearance from the Commissioner of Railway Safety.
For LHB coaches, the company expects around 20% of the associated revenue to be recognised in FY26, with the remaining portion expected in FY27.
In the metro segment, the Chennai Metro prototype is expected to be rolled out in FY27. Bengaluru Metro deliveries are expected to reach eight to ten trains during the year, with execution approaching peak levels in FY27. Mumbai Metro execution is also expected to resume from FY27, with activity reaching a peak in FY28.
Together, these programmes could provide a meaningful boost to revenue as production and deliveries increase.
BEML share price target: How much upside do brokerages see?
The brokerage recommendations indicate that analysts remain constructive on BEML’s medium-term prospects, although their valuations differ slightly.
– **ICICI Direct:** Buy recommendation with a target price of ₹2,765, implying approximately 40% upside based on the reference price cited.
– **Elara Capital:** Buy recommendation with a revised target price of ₹2,700, based on 37 times September FY27 estimated earnings.
The difference in target prices reflects the brokerages’ respective valuation assumptions and assessments of project execution. Neither target is a guaranteed outcome, and the potential upside will depend on the market price used for comparison, earnings delivery, order conversion and prevailing market conditions.
Investors should also monitor the pace of new order wins, the timing of Vande Bharat sleeper deliveries, capacity utilisation, working capital requirements and the company’s ability to deliver the anticipated margin improvement.
What should investors watch next?
BEML’s investment case increasingly rests on its ability to convert a strong order pipeline into consistent revenue and earnings growth.
Three factors will be particularly important over the coming quarters.
First, execution across railway and metro projects will determine whether the expected revenue acceleration materialises from FY27. Delays in approvals, manufacturing or deliveries could shift revenue recognition and affect near-term performance.
Second, defence order inflows could provide an additional source of growth and improve business diversification. However, potential opportunities must translate into actual orders and subsequent execution before they can materially contribute to earnings.
Third, margin expansion will be critical. A higher contribution from railway, metro and defence programmes could support profitability, but the extent of improvement will depend on product mix, production efficiency, project costs and execution discipline.
The investment by Abakkus Flexi Cap Fund adds another point of interest for market participants, but a fund’s stake purchase should not be treated as a guarantee of future stock performance.
Conclusion
BEML is at an important stage in its business evolution, with Rail & Metro and Defence & Aerospace increasingly shaping its growth outlook. A sizeable order book, opportunities across Vande Bharat and metro programmes, expanding defence prospects and investments in manufacturing capacity provide the foundation for a potential improvement in financial performance.
ICICI Direct’s ₹2,765 target and Elara Capital’s ₹2,700 target reflect a broadly positive analyst view, with both brokerages assigning a Buy recommendation despite differing assumptions about valuation and execution.
For investors, the key question is whether BEML can deliver the expected acceleration in revenue and earnings from FY27 while converting its expanding pipeline into profitable orders. If execution improves as anticipated, the company could strengthen its position as a domestic railway, mobility and defence engineering player. However, project delays, valuation risks and the timing of order inflows remain important considerations.
Disclaimer: This article is for informational and educational purposes only and is not investment advice. Brokerage estimates and price targets are analyst opinions, not assured returns. Investors should review the company’s latest disclosures, current valuation and individual risk tolerance before making investment decisions.