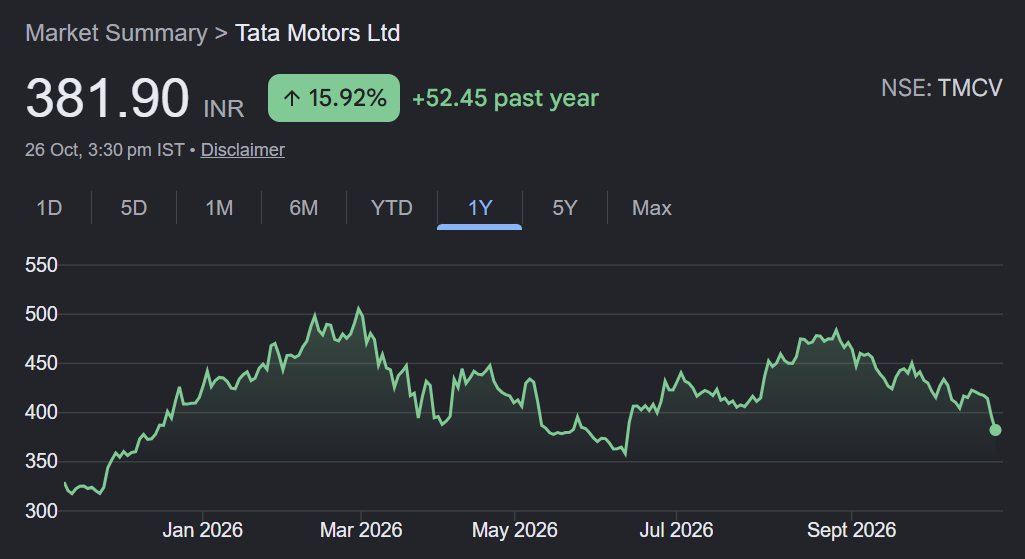
Robust execution amidst rising cost pressures…
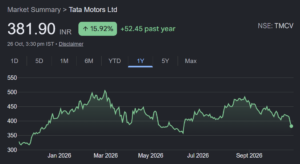
About the stock: Tata Motors Commercial Vehicles (TMCV) is an auto OEM from the house of Tata’s, operating in the domestic commercial vehicle (CV) space.
• Retail Market Share (FY26): ~36% in overall CV space, ~55% in Heavy CV domain, ~36% in Passenger (Bus) segment, ~27% in lights good vehicles
Q2FY27 Result: Tata Motors CV Q2FY27 results came in healthy. Consolidated topline for Q2FY27 stood at ₹25,338 crore (up 36% YoY) with EBITDA at ₹2,770 crore and EBITDA margins at 10.9% (down ~10 bps QoQ). PAT in Q2FY27 came in at ₹ 1,257 crore (up 245% YoY) because of one-time exceptional loss in base year.
Investment Rationale:
• Leadership in MHCV and Sustained Market-Share Gains: TMCV continues to strengthen its competitive positioning, supported by broad- based volume growth, improving freight activity and infrastructure-led demand. In Q2FY27, wholesales grew 42% YoY to 1.35 lakh units, with double-digit growth across all major segments. H1FY27 market share increased by 110 bps over FY26 to 36.2%, led by HCV market share of 55.7% and a 500 bps improvement in CV passenger vehicles to 41.1%. Improving fleet utilization, stronger freight rates and resilient replacement demand provide support to the domestic CV cycle. While industry growth is expected to moderate to high-single-digit levels in Q3FY27 amid a higher base, TMCV’s product portfolio, customer reach and market-share gains position it to capitalize on the underlying demand opportunity.
• Export Diversification, EV Growth and Strong Financial Position: TMCV is expanding its growth opportunities beyond the domestic CV cycle through international markets, electric mobility and downstream businesses. The ~70,000-unit Indonesia order provides volume visibility across FY27–FY28, while improving demand in other international markets offers scope to diversify exports beyond this order-led ramp-up. EV volumes grew 143% YoY in Q2FY27, with EV SCV retail volumes increasing 2.9x, and management expects EV penetration in SCV pickups to potentially reach ~20% in Q4FY27. Meanwhile, aftermarket services, digital fleet solutions and other non-cyclical businesses, which account for approximately 20% of revenue, provide opportunities to improve earnings resilience. Strong cash generation, with consol FCF of ₹3,000 crore in Q2FY27 and net cash of ₹15,900 crore, supports investments in growth and operational capabilities.
Rating and Target Price
• Strong volume momentum, market-share gains, export visibility and a robust balance sheet support TMCV’s medium-term growth outlook. Factoring in the core CV business, growth opportunities from the Iveco acquisition and the value of other investments, we maintain our Buy Rating on TML and value it at ₹ 515 on SOTP basis (12x EV/EBITDA on FY28E, 2x P/B on investments)