Building a healthcare giant
The Aster DM Healthcare–QCIL merger creates one of India’s largest hospital platforms, Aster DM Quality Care (AsterDM), with 39 hospitals and ~10,600 operational beds across 28 cities. The platform has capacity to scale beyond 15,000 beds by FY30 through a balanced brownfield/greenfield/asset-light approach.
A cluster-led strategy anchors the growth story, with Kerala’s mature, high- margin base complemented by a faster-growing Karnataka/Maharashtra and AP/Telangana footprint, providing both earnings stability and a long growth runway.
The QCIL merger meaningfully deepens regional diversification, bringing a complementary set of hospital networks under one roof and creating a genuinely pan-India platform with stronger potential for cross-cluster referrals.
Prior to the QCIL merger, AsterDM had already demonstrated a growth- plus-margin story (revenue +12% YoY in FY25/FY26 to INR41b/46b, alongside ~300bp/90bp margin gains), with momentum carrying into 1QFY27 (+22%/27% revenue/EBITDA YoY) and FY26 proforma combined revenue/EBITDA of INR92.7b/INR20b (+14%/21% YoY). We expect revenue/EBITDA/PAT to deliver 19.5%/25%/33% CAGR over FY26-28, reaching INR132b/INR30.7b/INR16.5, respectively, aided by procurement, clinical, and cost synergies.
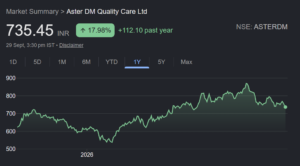
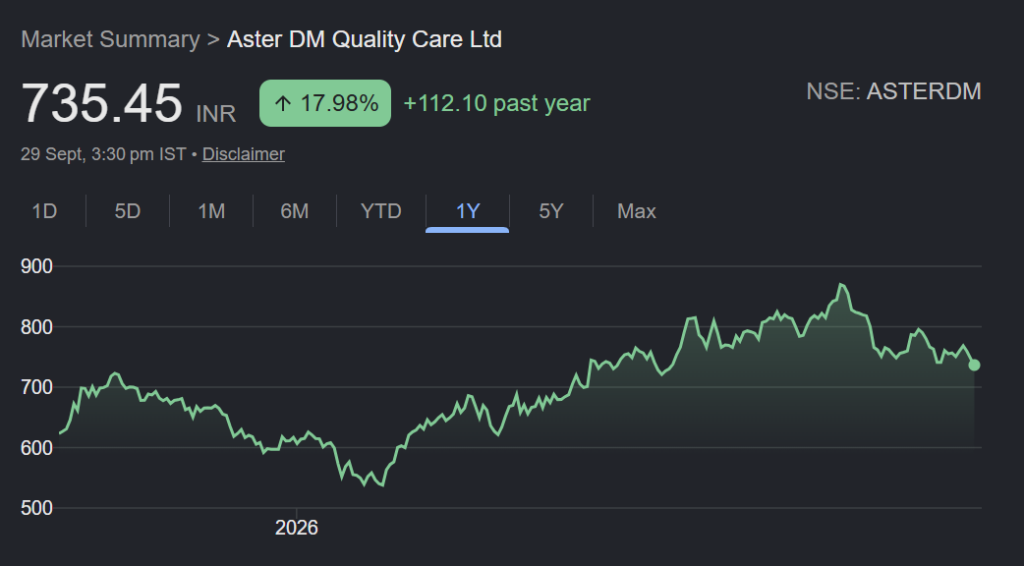
We initiate coverage with a BUY rating, valuing ASTERDM at 27x 12M forward EBITDA (INR27.7b) to arrive at a TP of INR910 (20% upside from INR759), with bull/bear scenarios of INR1,110/INR735 hinging on the pace of QCIL synergy realization and capacity ramp-up.